
Nvidia has reportedly agreed to pay $12.9 billion for the repository where three million open models live. The neutrality that made the platform worth buying was built out of preferred equity, and preferred equity converts to cash.
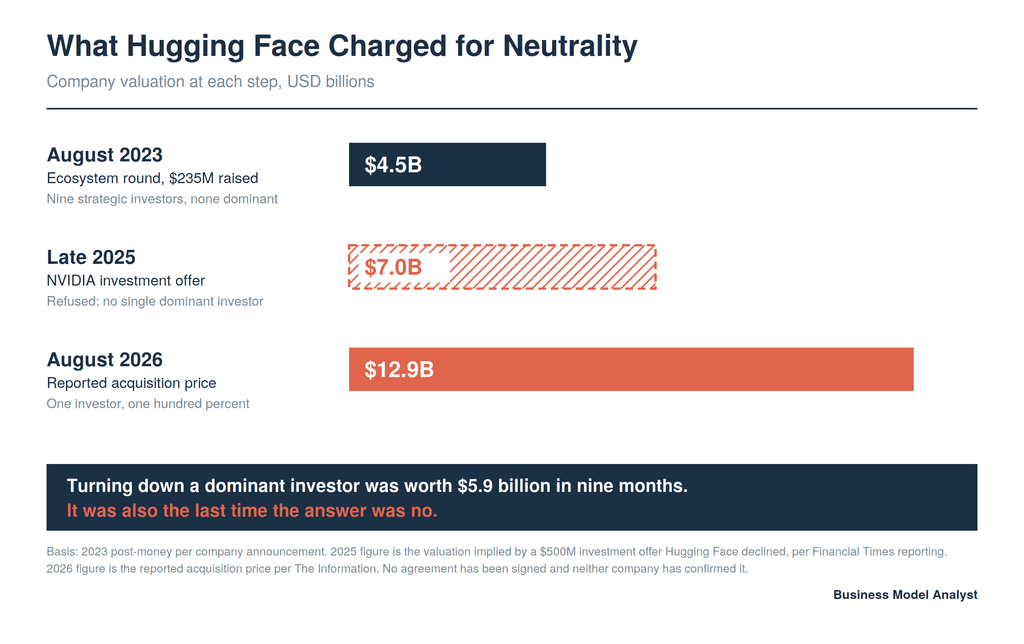
Nvidia agreed to buy Hugging Face for $12.9 billion, The Information reported on the night of August 26, 2026. Hugging Face generates roughly $150 million in annualized revenue, so the price works out near 86 times sales. Nvidia already owned a slice of the company from a 2023 round that Hugging Face designed to prevent any one investor from gaining control. That design worked for three years. Then one of the nine investors offered to buy all of it.
In August 2023, Clément Delangue raised $235 million from Salesforce Ventures, Google, Amazon, Nvidia, Intel, AMD, Qualcomm, IBM and Sound Ventures at a $4.5 billion valuation. He described the structure to Axios at the time as an ecosystem round, and said it confirmed Hugging Face as “a neutral platform, or the Switzerland” for AI. He also told Axios the money carried no special access or side terms for any backer. Delangue was not describing a marketing position. He was describing a governance mechanism, and he built it out of stock.
Eleven months ago, Meta’s engineers faced a version of the same problem with PyTorch and solved it a different way.
What Happened
The Information reported the agreement on Wednesday evening, citing a person with knowledge of the deal. Business Insider, which broke the sale process over the previous weekend, reported the same night that the parties had not signed anything and that talks could still collapse. Reuters and CNBC followed. Neither Nvidia nor Hugging Face has commented, which TechCrunch flagged as unusual for a company that moves fast to correct reporting it disputes.
The sequence matters. Business Insider reported that Hugging Face hired a bank to test buyer appetite at $13 billion or more. The Information reported that talks with Nvidia started after a different suitor approached the company. Delangue did not field an unsolicited bid from his largest hardware partner. He ran a process.
Nvidia reported fiscal second-quarter results the same afternoon. Revenue hit $96.2 billion for the quarter ended July 26, up 106% year over year and 18% on the prior quarter, against a $92.2 billion consensus. Data center revenue reached $89 billion. Gross margin held at 75% for a second quarter. CFO Colette Kress guided the current quarter to $108 billion and told analysts that capital spending across the top five hyperscalers should climb from $800 billion in 2026 to $1.3 trillion next year. Shares rose about 4% after hours.
Against that quarter, $12.9 billion buys twelve days of revenue.
The Backstory
Hugging Face started in 2016 as a chatbot app built by Delangue, Julien Chaumond and Thomas Wolf. It became the default place to publish model weights. As of August 14, the Hub held more than three million models and a million datasets, serving 13 million users. The company added roughly 1.18 million models during 2025 alone, more than the entire cumulative total from every year before it.
Meta, Google, Alibaba, DeepSeek and Z.AI all ship their open weights there first. Nvidia would own the shelf where its competitors stock their products.
The 2023 round was the first defense against exactly that outcome. Nine strategic investors, small positions, no side letters. In late 2025, Delangue defended the same principle a second time, turning down a $500 million investment from Nvidia at a $7 billion valuation because he did not want a single backer able to sway company decisions, according to Financial Times reporting.
Nine months later he agreed to sell the whole company to that investor. TechCrunch waved at the contradiction and moved on, suggesting a buyout differs from a giant backer because an outsized investor pressures a company while ceding it nothing. That reasoning runs backwards. A minority holder can lobby. An owner appoints the board.
Meta hit the same fork in September 2022 and chose a different container. Zuckerberg moved PyTorch out of Meta and into the Linux Foundation under a newly formed PyTorch Foundation, with AMD, AWS, Google Cloud, Meta, Microsoft Azure and Nvidia as founding members. The Linux Foundation’s stated reason was that platforms of that weight “benefit from a neutral home”. Meta gave up ownership. The founding members got board seats and no equity.
Compare the two rosters. Hugging Face assembled Google, Amazon, Nvidia, Intel, AMD, Qualcomm, IBM and Salesforce. PyTorch assembled AMD, AWS, Google, Meta, Microsoft and Nvidia. Nearly the same companies, the same neutrality goal, four years apart. One sits inside a nonprofit that nobody can buy. The other is being acquired by one of its own investors.
The Plan
Nvidia’s stated logic is defensive and reasonable. OpenAI, Google, Amazon and Anthropic are all building their own accelerators to reduce what they pay Nvidia. At Hot Chips on August 25, OpenAI and Broadcom presented benchmark claims for a custom inference part they say beats Blackwell rack systems. Every closed lab that ships silicon subtracts demand. A crowded open-model ecosystem does the opposite, because open weights run wherever developers put them, and most developers put them on Nvidia hardware. Our Nvidia competitors breakdown covers why six of the ten most serious threats to Nvidia are also its largest customers.
Owning the Hub also hands Nvidia a route back into cloud after it wound down DGX Cloud last year, plus somewhere to place capacity it may end up holding. Nvidia has committed to support the cost of tens of billions in customer compute deals, and our analysis of the $500 billion compute financing platforms covers how those obligations work. Hugging Face brings 13 million potential buyers for anything stranded.
What stands out is the structure. Nvidia spent 2026 perfecting a way to buy capability without buying companies. It paid Groq around $20 billion in December for a non-exclusive inference license plus the leadership team, with no entity changing hands and no merger filing. On August 21 it ran the same play on Poolside: $6 billion to license the Model Factory software, $1 billion of equity at a $12 billion pre-money valuation, and job offers to 109 engineers who move onto Nvidia’s Nemotron open-weight program. The founders stayed behind.
Hugging Face is the one asset that structure cannot reach. Groq had chip designs. Poolside had training software. Both are licensable. The Hub is a network, and you cannot license a network or hire it away, because its value sits in the three million files that 13 million strangers uploaded. Buying the corporation is the only route in, which also means an antitrust filing that the Groq and Poolside structures avoided.
The Business Model Angle
Most of the coverage treats $12.9 billion for $150 million of revenue as evidence of a bubble. Run the comparison against Hugging Face’s own history and the opposite shows up.
TechCrunch reported in 2023 that the $4.5 billion mark represented more than 100 times annualized revenue, which puts 2023 sales somewhere under $45 million. Today’s reported price is 86 times $150 million. Price climbed 2.9x. The multiple came down.
Nvidia is buying total control at a lower multiple than a consortium paid for minority slices three years ago. Control normally costs a premium. Delangue is selling the whole company for less per dollar of revenue than his own investors accepted for scraps.
Two readings survive. Either the 2023 ecosystem round overpriced the asset, or the ecosystem round contained a neutrality premium that a control sale destroys, so it cannot be included in the control price. The second reading fits the facts better, and it explains why Delangue could refuse $7 billion for a minority stake and accept $12.9 billion for the entire thing. Those transactions are pricing two different assets.
Revenue growth complicates the arithmetic in Hugging Face’s favor. The Information reported roughly $100 million in annualized revenue about two months before the $150 million figure. Growth at that rate compresses the multiple hard before any deal closes, and Delangue told TechCrunch last month the company sits near profitability. Compare the Stripe and OpenRouter deal at more than $7 billion on roughly $140 million: 50 times sales for a company Stripe already used as a vendor. Buyers are paying for position in the AI stack, and each one is paying a different number for it.
Nvidia’s 10-Q for the quarter tells you what room it has. As of July 26, the company disclosed $366 billion of future commitments, including $279 billion of supply and capacity, $29 billion of cloud service agreements and $25 billion earmarked for equity investments, $18 billion of that falling in the remainder of fiscal 2027. Hugging Face at $12.9 billion consumes about half the equity-investment line on its own. The purchase sits inside a company that generated $96.2 billion in ninety-one days at 75% gross margin. Our Nvidia business model teardown covers where that margin comes from.
The Risk
The neutrality argument cuts against itself in several places, and the honest version of this story includes all of them.
Hugging Face already leaned toward Nvidia. Delangue spent 2026 publicly backing Nvidia’s open-source position. He signed the August letter urging Washington to support open-weight models alongside Jensen Huang and 24 other signatories. On CBS this month he described using an Nvidia-modified Chinese open model to defend the company after a cyberattack. Nvidia may be paying $12.9 billion for ground it already held.
Switching costs are low. The Hub runs on git. Weights are files. ModelScope, Kaggle and direct object storage all work, and any lab annoyed by the new owner can mirror elsewhere on release day. That constrains how much Nvidia can extract, which also constrains what the asset is worth. A platform that punishes you for leaving is valuable. A platform you can leave in an afternoon is a habit.
Microsoft bought GitHub for $7.5 billion in 2018 and the predicted developer exodus never arrived. Microsoft ran it at distance and the product improved. Nvidia has kept its word before, continuing to distribute Slurm as open source after buying SchedMD. The disanalogy is that Microsoft does not sell the thing GitHub hosts. Nvidia sells the compute that every model on the Hub consumes.
Nothing is signed. Business Insider says the deal could still fall apart, and neither company has confirmed a number.
Watch this after any close: whether Google, Alibaba and DeepSeek keep publishing to the Hub first. If release-day weights start appearing on ModelScope or the labs’ own endpoints before Hugging Face gets them, the neutrality was load-bearing and Nvidia bought a depreciating asset. If those labs keep shipping to the Hub as before, the neutrality was decoration and Nvidia bought a genuine network at 86 times sales.
Quick Questions
How much is Nvidia paying for Hugging Face? $12.9 billion, per The Information on August 26, 2026. Business Insider reported a figure above $13 billion and said no agreement had been signed.
What is Hugging Face worth on a revenue basis? About 86 times annualized revenue of roughly $150 million. Its 2023 round priced it above 100 times sales, so the multiple has fallen even as the price nearly tripled.
Why does a chip company want a model repository? Open models give buyers an alternative to closed labs, and those closed labs are the customers designing their own chips. Wider open-model use keeps more workloads on Nvidia hardware. The Hub also gives Nvidia a path back into cloud after it scaled down DGX Cloud.
Did Hugging Face turn Nvidia down before? Yes. It rejected a $500 million investment at a $7 billion valuation in late 2025, saying it did not want one dominant investor, per the Financial Times.
How does this compare with Nvidia’s other 2026 deals? Groq and Poolside were non-exclusive technology licenses plus hiring, structured so no company changed hands. Hugging Face is a full acquisition, because its value is a network rather than technology.
The Business Model Analyst Take
Delangue built a real thing and got paid for it. Anyone who assembled the world’s model registry from a failed chatbot app deserves the outcome, and his shareholders will be thrilled.
He also sold the same asset twice. In 2023 he sold slices of it and priced neutrality into the round, telling reporters the ownership structure was the product. In 2026 he sold the whole thing, and the buyer is the one participant whose ownership makes the 2023 promise void. Both sales priced the same commitment: that he would never do the second one.
If your product is neutrality, keep it out of the equity. A consortium cap table is a standstill agreement with no expiry date and nobody to enforce it. It holds until one member wants control more than the others want to block him, and at that point the only question left is price. The structures that survive contact with a real offer are the ones with nothing to sell. Foundations, mutuals, purpose trusts, golden shares. Meta understood this in 2022 and handed PyTorch to a nonprofit rather than trust six competitors to hold each other still.
Ask yourself which promises in your own business live in a contract and which live in a share register. The ones in the share register are for sale, whatever you told customers when you made them.