The top 10 Nvidia competitors are AMD, Google, Broadcom, Amazon, Huawei, Intel, Microsoft, Meta, Qualcomm, and OpenAI. Six of those ten are also Nvidia customers, which is the single most important fact about the AI chip market in 2026: the companies with the best shot at taking Nvidia’s share are the ones writing it the biggest checks.
Nvidia reported $75.2 billion of data center revenue in the quarter ended April 26, 2026, up 92% from a year earlier. That one segment, in one quarter, is larger than the combined AI chip revenue of AMD, Intel, and Broadcom for their most recent quarters. Any list of Nvidia rivals has to start by admitting the gap.
The gap is closing at the edges, though, and not from where most competitor lists look. Merchant GPU vendors are growing at roughly 16% this year. Custom accelerators built by the hyperscalers are growing at roughly 45%. The threat to Nvidia comes from its own order book.
What Counts as an Nvidia Competitor
An Nvidia competitor is any company whose product can absorb AI or graphics workloads that would otherwise run on Nvidia silicon. That covers merchant chip vendors who sell to anyone, hyperscalers who design accelerators for their own data centers, and Chinese vendors serving a market Nvidia can no longer ship into. It does not cover suppliers, board partners, or server assemblers, however often they appear on competitor lists.
The distinction matters because most published lists conflate three different relationships. A foundry that manufactures Nvidia’s chips is a supplier. A company that buys Nvidia GPUs and screws them into a chassis is a channel partner. Neither takes revenue away from Nvidia when it wins.
A company that designs an accelerator to run its own inference workloads does take revenue away, even if it never sells a single chip to anyone else. Google is the clearest case. It has never sold a Tensor Processing Unit on the open market, and it is the most serious threat on this page.
The Scoreboard: Nvidia Against the Field
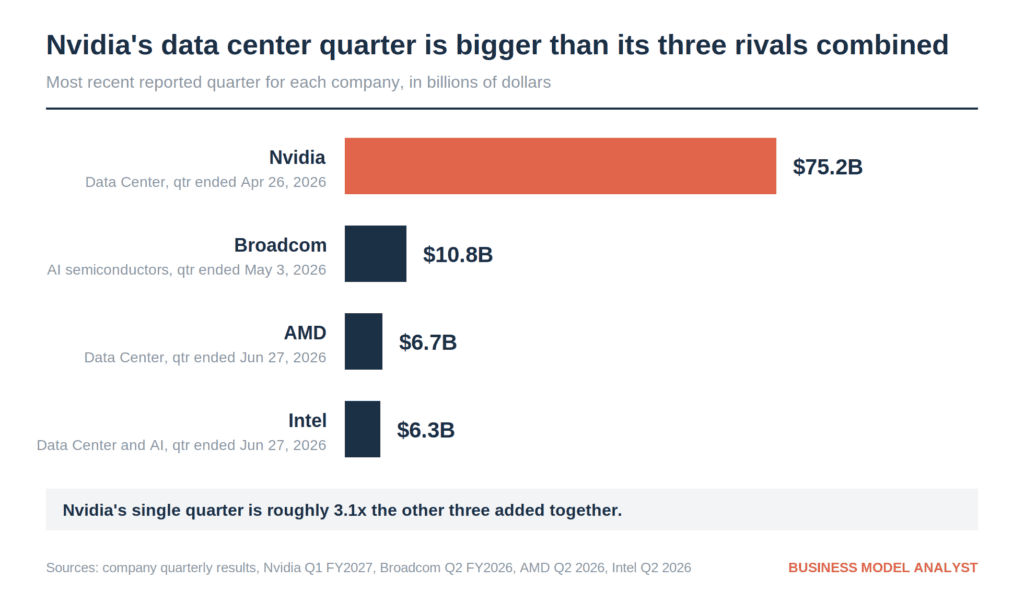
Nvidia’s quarter ended April 26, 2026. Broadcom’s ended May 3, AMD’s and Intel’s ended June 27. Google and Amazon fold custom silicon into cloud revenue and disclose no chip-level figures, which is itself a competitive advantage: neither has to explain a bad chip quarter to anyone.
Top 10 Nvidia Competitors and Alternatives
1. AMD
AMD is the only company selling a general-purpose AI accelerator to the open market at scale. Its Instinct line runs against Nvidia’s data center GPUs, its EPYC server CPUs run against Intel, and its Radeon cards run against GeForce in gaming.
Data center revenue reached $6.7 billion in the June 2026 quarter, more than double a year earlier and 58% of company revenue. The MI450 and the Helios rack-scale system, specified with input from Meta, are aimed squarely at Nvidia’s NVL72 racks. AMD has told investors it wants $100 billion in annual data center revenue by 2030.
The business model underneath is worth naming plainly: AMD sells insurance against single-vendor dependence. Its addressable market is buyers large enough to fear being locked to one supplier. OpenAI has committed to 6 gigawatts of AMD capacity, Meta to 6, and Anthropic to 2. AMD is also financing that book, having granted OpenAI a warrant covering up to 160 million shares and committed up to $5 billion to Anthropic. We covered how the market misread that dynamic in our analysis of AMD’s record quarter and the 8% selloff.
Buyers weighing a switch usually find that the hardware is the easy part and the software migration is not. Firms working through that kind of change often bring in outside product and design partners such as Langate to handle the interface layer while their own engineers focus on the model stack.
The full revenue breakdown sits in our AMD business model teardown.
2. Google (Alphabet)
Google has designed Tensor Processing Units since 2015 and never sold one as a standalone product. That changed in 2026.
The seventh-generation TPU, Ironwood, is generally available on Google Cloud and scales to 9,216 chips in a single pod. Anthropic was an early anchor customer. In February 2026, Meta signed a multibillion-dollar agreement for TPU capacity through Google Cloud, and reporting since has pointed to talks about Meta buying TPUs outright for its own data centers from 2027. Google has told partners it believes it can take up to 10% of Nvidia’s data center revenue.
Two things make Google the most credible long-term threat. It is the only competitor with a frontier model, a hyperscale cloud, and a mature accelerator under one roof, so it can tune all three against each other. And it does not need the chip business to be profitable on its own, because the return shows up in Google Cloud margins. Alphabet’s cloud segment grew 82% year over year in the second quarter of 2026 on a $514 billion backlog.
The eighth generation is already split across two suppliers, with Broadcom on the training part and MediaTek on inference, both targeting TSMC’s 2nm node. See our Google business model breakdown for how the cloud segment monetizes.
3. Broadcom
Broadcom does not sell a competing GPU. It sells the ability to stop needing one.
Its custom accelerator business, which it calls XPUs, designs chips to a customer’s own architecture. Broadcom builds Google’s TPUs, Meta’s MTIA parts, and OpenAI’s forthcoming accelerator, and it has six confirmed custom AI customers. AI semiconductor revenue hit $10.8 billion in the quarter ended May 3, 2026, up 143%, with management guiding to $16 billion for the following quarter and more than $100 billion for fiscal 2027.
The number that should worry Nvidia is the backlog. Broadcom booked more than $30 billion of AI orders in a quarter where it shipped $10.8 billion, and told investors its visibility now extends into fiscal 2028. Those orders represent workloads that will never touch an Nvidia GPU.
Broadcom also sells the Tomahawk and Jericho switching silicon that connects large clusters, which competes with Nvidia’s networking business. Nvidia’s data center networking revenue was $14.8 billion in its latest quarter, growing 199%, so both companies are fighting over a fabric layer that is expanding faster than compute.
4. Amazon (AWS)
Amazon designs Trainium for training and Inferentia for inference through its Annapurna Labs unit, and it has the largest non-Nvidia AI cluster in operation. Project Rainier in Indiana runs close to 500,000 Trainium2 chips across an $11 billion campus built for one tenant.
In April 2026, Anthropic committed more than $100 billion over ten years to AWS technologies and secured up to 5 gigawatts of capacity spanning Trainium2 through Trainium4. Anthropic already runs more than a million Trainium2 chips. Amazon put $5 billion more into Anthropic alongside the deal, with up to $20 billion to follow against commercial milestones.
Amazon competes on cost per token rather than peak performance, and it competes inside its own cloud, where it controls pricing, availability, and which instance type a customer sees first. Our Amazon business model analysis covers how AWS margins absorb that investment.
5. Huawei
Huawei is Nvidia’s only competitor with a protected home market. Nvidia’s guidance for the quarter ending July 2026 assumed no data center compute revenue from China at all.
In May 2026, China’s security certification bodies approved nine domestically designed AI processors for state procurement, including Huawei’s Ascend 310 and 910 series, Alibaba’s T-Head parts, and chips from Biren, Hygon, Iluvatar CoreX, MetaX, and Moore Threads. Nvidia is not on the list.
Huawei planned roughly 600,000 Ascend 910C units for 2026 and up to 1.6 million dies across the Ascend line, manufactured with SMIC. The constraint is high-bandwidth memory rather than logic, since domestic HBM production remains limited and the leading suppliers are Korean and American. Analysts at the Council on Foreign Relations have noted that Huawei’s own published roadmap puts the 2026 Ascend 950 parts below the 910C on some performance measures, which suggests the manufacturing side is harder than the design side.
Judge Huawei on availability rather than benchmarks. For a Chinese state buyer, a chip that can be bought beats a chip that cannot.
6. Intel
Intel is having its best year in a decade, and almost none of it comes from competing with Nvidia’s GPUs.
Second-quarter 2026 revenue rose 25% to $16.1 billion, the fastest growth in more than fifteen years. Data Center and AI revenue grew 59% to $6.3 billion, driven by server CPUs that sit alongside Nvidia accelerators rather than replacing them. CFO David Zinsner told analysts the company cannot make enough of them.
The accelerator story is still ahead of Intel. Gaudi never gained traction. Crescent Island, an inference GPU designed around cheaper LPDDR5X memory and air-cooled racks, only reaches customer sampling in the second half of 2026. Intel is targeting the enterprises that want inference without rebuilding a data center for liquid cooling, which is a real market and a smaller one than training.
Intel’s ownership structure now reads like a policy document. The US government holds roughly 10% after buying close to $9 billion of stock through a CHIPS Act agreement, Nvidia holds about 4% after a $5 billion investment, and SoftBank put in $2 billion. A $12.5 billion mark-to-market loss on those escrowed government shares produced an $11 billion GAAP net loss in a quarter that was operationally strong.
Nvidia owning a slice of Intel while Intel tries to sell against it is the kind of arrangement that only makes sense once you accept that Nvidia’s real interest in Intel is foundry capacity. More detail in our Intel business model analysis and the broader Intel competitors breakdown.
7. Microsoft
Microsoft designs the Maia accelerator and the Cobalt CPU for Azure, and has been reported to be working with Broadcom on future custom parts. It remains one of Nvidia’s largest buyers.
Microsoft’s competitive weight comes from allocation rather than silicon. Enterprises buying AI capacity through Azure take whatever Microsoft puts in front of them, and Microsoft decides how much of that is Nvidia. Satya Nadella has been publicly blunt about the dangers of depending on a single AI supplier, which is easier to say when you are building the alternative in house.
8. Meta
Meta has planned capital expenditure of $115 billion to $135 billion for 2026, roughly double the prior year, which makes it one of the two or three buyers whose procurement decisions move the whole market.
It is spending that budget in four directions at once: Nvidia GPUs, a five-year AMD MI450 commitment reported at around $60 billion starting in the second half of 2026, Google TPU capacity signed in February 2026, and its own MTIA accelerators plus a training chip known internally as Artemis. Meta is not trying to replace Nvidia. It is trying to make sure no supplier can set its prices.
9. Qualcomm
Qualcomm entered the data center in October 2025 with the AI200 and AI250, rack-scale inference systems built on its Hexagon neural processing cores. The AI200 reaches availability in the second half of 2026, with 768GB of LPDDR memory per accelerator card and a rack-level power target around 160kW. The AI250 follows in 2027 with a near-memory architecture.
Its first customer is Humain, the Saudi state-backed AI venture, which committed to 200 megawatts starting in 2026. Humain is also taking Nvidia Blackwell systems and AMD hardware, so the deployment is a bake-off rather than a defection.
Qualcomm still dominates mobile graphics through Adreno cores in Snapdragon, a market Nvidia left years ago. It also bought Alphawave for $2.4 billion to strengthen its interconnect position and signed an NVLink Fusion agreement with Nvidia, which makes it a competitor and a partner in the same product cycle. See our Qualcomm business model teardown.
10. OpenAI
Listing a model developer among chip competitors looks odd until you check what it has ordered. OpenAI is designing its own accelerator with Broadcom under a collaboration covering 10 gigawatts of deployment, has committed to 6 gigawatts of AMD capacity with a warrant attached, and buys Nvidia systems at scale.
OpenAI does not need to build a better GPU. It needs a chip that runs its own models at a lower cost per token than renting Nvidia silicon does, on workloads it already knows in detail. That is a narrower engineering problem, and it removes demand from Nvidia either way, because the threat of a working in-house part is itself a pricing lever.
The Specialists Worth Watching
Outside the top ten, a smaller group builds architectures that abandon the GPU model entirely. Cerebras builds wafer-scale processors. Tenstorrent, led by chip architect Jim Keller, licenses RISC-V based designs. SambaNova targets enterprise inference.
Groq belonged on this list until Christmas Eve 2025, when Nvidia agreed to pay about $20 billion in cash for its assets.
Companies That Are Not Actually Nvidia Competitors
Four names show up on almost every competitor list and belong on none of them.
TSMC manufactures Nvidia’s chips. It also manufactures for AMD, Google, Amazon, and Qualcomm. TSMC captures value from AI regardless of who wins the accelerator war, which makes it a supplier with pricing power rather than a rival. It has never designed a GPU and does not intend to.
ASUS and Gigabyte buy Nvidia GPUs, mount them on boards, and sell them under their own brands. Board partners are distribution. When Gigabyte sells more graphics cards, Nvidia sells more chips.
HP and HPE assemble and integrate servers containing other companies’ accelerators. Offering an AMD configuration alongside an Nvidia one makes HPE a channel with choice, not a competitor.
Texas Instruments makes analog and embedded processors for industrial and automotive systems. The overlap with Nvidia’s automotive platform is thin and the products serve different design requirements.
Apple deserves a more careful answer. Its M-series and A-series chips include GPU cores that displace demand for discrete graphics inside Apple hardware, and Apple has trained models on Google TPUs rather than Nvidia GPUs. In consumer silicon it competes. In the data center it abstains, which we examined in our piece on Apple’s capital discipline.
The Numbers Behind the Shift
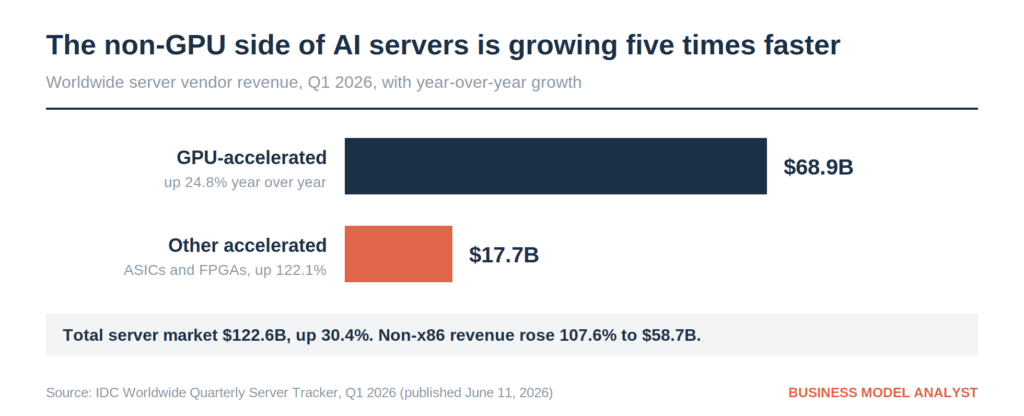
IDC’s server tracker separates GPU-accelerated systems from those built around other accelerators. In the first quarter of 2026, GPU-accelerated servers generated $68.9 billion in vendor revenue, up 24.8%. Systems using ASICs and FPGAs generated $17.7 billion, up 122.1%. The smaller category grew about five times faster.
The same quarter showed non-x86 server revenue rising 107.6% to $58.7 billion, or 47.9% of the market, while x86 revenue fell 2.9% under component shortages. The architecture mix of the server market is changing faster than the vendor mix.
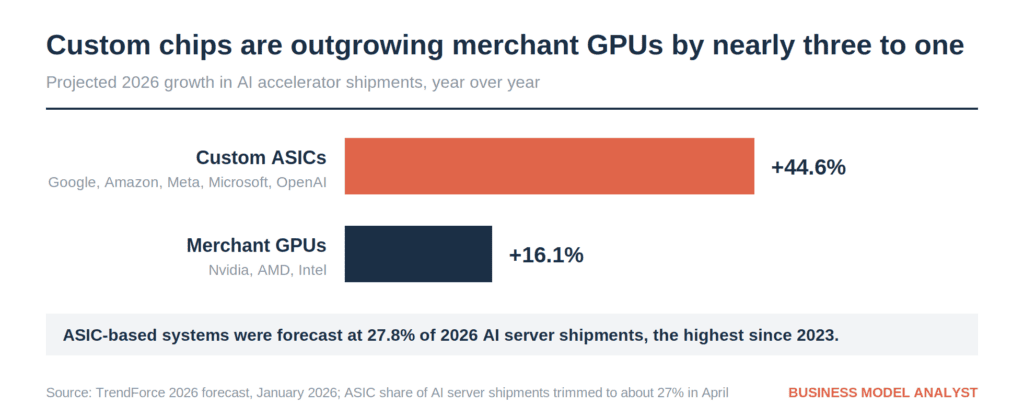
TrendForce forecast custom ASIC shipments growing 44.6% in 2026 against 16.1% for merchant GPUs, with ASIC-based systems reaching about 27% of AI server shipments. Bloomberg Intelligence expects Nvidia to hold 70% to 75% of the accelerator market through 2030 and AMD to reach at least 10%, with custom ASICs climbing from 8% of the market in 2024 to 19% by 2033.
Read those forecasts together and the picture is a market where Nvidia’s share erodes slowly while its absolute revenue keeps climbing, because the market is expanding faster than any single competitor can take share.
Nvidia’s Answer: Buy the Competition
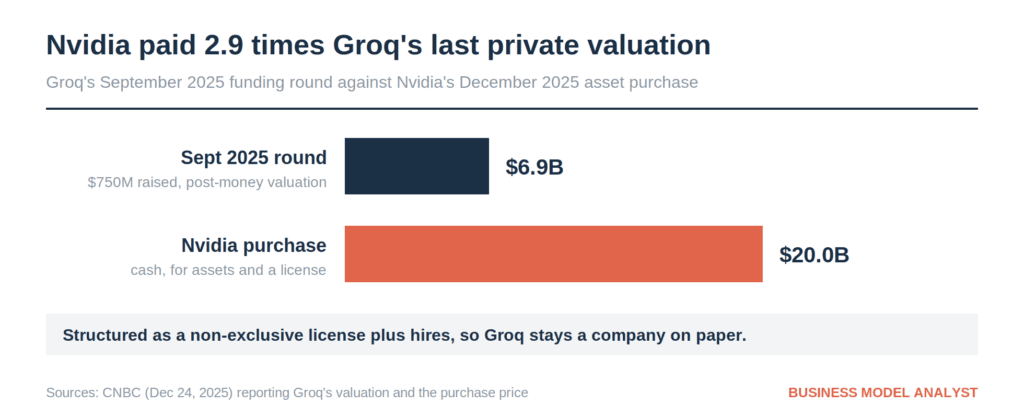
On December 24, 2025, Nvidia agreed to pay roughly $20 billion in cash for the assets of Groq, the inference chip startup founded by Jonathan Ross, who had helped create Google’s TPU. Groq had raised $750 million three months earlier at a $6.9 billion valuation. Nvidia paid about 2.9 times that, in its largest transaction ever, roughly three times what it paid for Mellanox.
The structure is the interesting part. Nvidia licensed Groq’s inference technology on a non-exclusive basis and hired Ross, president Sunny Madra, and other senior leaders. Groq continues as an independent company under a new chief executive, running its cloud business. No entity changed hands, so no merger filing was required. By March 2026, Nvidia was showing the Nvidia Groq 3 LPU at its developer conference.
Nvidia has run versions of this play repeatedly. It holds about 4% of Intel after a $5 billion investment, put $2 billion each into optical component makers Coherent and Lumentum, invested in Safe Superintelligence in exchange for research access, and committed capital to Anthropic. Jensen Huang told investors at GTC in March 2026 that he sees at least $1 trillion in Blackwell and Vera Rubin orders through 2027, double the figure he gave a year earlier.
A company with 75% gross margins and $48.6 billion of quarterly free cash flow can buy competitive threats more cheaply than it can out-engineer them. That is a business model advantage, and it does not show up on any competitor list.
Where Nvidia Is Genuinely Exposed
Three pressure points are worth tracking, and none of them is a better GPU.
Inference economics. Training rewards raw performance, where Nvidia leads. Inference rewards cost per token at steady state, where a chip tuned to one model family can win. Every hyperscaler custom accelerator targets inference first.
China. Nvidia now guides to zero data center compute revenue from the world’s second-largest economy. Domestic vendors have a certified, protected market, and the longer that lasts, the more capable the alternatives become.
Networking. Nvidia’s $14.8 billion networking quarter grew 199%, and Broadcom is attacking it with Ethernet switching that works with any accelerator. Networking is the part of Nvidia’s rack that has no CUDA moat.
For a fuller treatment of these threats and the offsetting strengths, see our Nvidia SWOT analysis and the Nvidia business model breakdown. The question of where the profit pool eventually settles is covered in our analysis of AI margin migration.
Frequently Asked Questions
Who is Nvidia’s biggest competitor?
Google, on a long enough horizon. It has the only custom accelerator with a decade of production history, a frontier model to tune it against, and a hyperscale cloud to sell it through. In near-term revenue terms Broadcom is the closest, at $10.8 billion of AI semiconductor revenue in its latest quarter.
Who competes with Nvidia in graphics cards?
AMD’s Radeon line is the only direct alternative at every price tier. Intel’s Arc series covers mid-range gaming and professional workloads at low volume. ASUS, Gigabyte, MSI, and Zotac sell graphics cards but do not design the chips inside them.
Which companies are challenging Nvidia in artificial intelligence?
AMD with Instinct accelerators, Broadcom with custom XPUs built for Google, Meta, OpenAI, and Anthropic, Google with TPU v7 Ironwood, Amazon with Trainium, Microsoft with Maia, Meta with MTIA, and Qualcomm with the AI200 and AI250 inference racks.
Which Chinese companies compete with Nvidia?
Huawei leads with the Ascend line, targeting roughly 600,000 units of the 910C in 2026. China’s state procurement certification, granted in May 2026, also covers Alibaba’s T-Head processors, Biren, Hygon, Iluvatar CoreX, MetaX, and Moore Threads. Cambricon serves large private buyers including ByteDance. High-bandwidth memory supply is the binding constraint for all of them.
Is TSMC a competitor to Nvidia?
No. TSMC manufactures Nvidia’s chips and those of most Nvidia rivals. It profits from AI demand regardless of which designer wins, which makes it a supplier with unusual pricing power rather than a competitor.
Can any company realistically replace Nvidia?
Not as a single replacement. The plausible outcome is fragmentation by workload, with Nvidia holding training and general-purpose compute while custom silicon takes a growing share of steady-state inference. Bloomberg Intelligence still models Nvidia at 70% to 75% of the accelerator market through 2030.
What is Nvidia’s competitive moat?
CUDA, the software layer that has accumulated more than fifteen years of libraries, tooling, and trained engineers. Rival hardware often benchmarks well and still loses on migration cost. AMD’s ROCm and Intel’s oneAPI both target this, and neither has closed the gap.
The Business Model Analyst Take
Competitor lists assume that rivals are separate companies fighting over the same buyers. Nvidia’s situation inverts that. Its ten most serious competitors include six of its largest customers, one company it owns a stake in, and one whose closest architectural rival it bought outright for $20 billion.
That structure produces a specific kind of competition. Google, Amazon, Meta, Microsoft, and OpenAI are not trying to build a business selling chips. They are trying to stop paying Nvidia’s margin on their own workloads, which they can justify at almost any development cost given what they spend. Broadcom monetizes that impulse without taking design risk, which is why its backlog runs to $30 billion in a single quarter.
Nvidia’s response has been to treat competition as an asset class. Buying Groq’s assets on Christmas Eve, taking 4% of Intel, funding optical suppliers, and investing in the labs that buy its systems are all the same move: convert a threat into a supplier, a customer, or a license. It works because 75% gross margins make acquisition cheaper than defense.
Watch the inference line rather than the training headlines. Training is where Nvidia’s lead is widest and where its narrative lives. Inference is where the cost per token gets audited every quarter by people who can build their own chip, and where its share will be decided.