
Partners were offered a revenue floor and half the upside. What they refused was a term sheet telling them which customers they were allowed to serve.
Nvidia has stepped back from parts of the AI Compute Partnership, the credit-support-for-revenue-share program it launched on July 1. Nvidia disclosed $36 billion of commitments under the program in its quarterly filing this week, on agreements that typically run six years. The reported sticking point was not the split. Nvidia told some cloud providers they could rent the chips only to approved customers, and said it preferred capacity spread across several smaller AI companies rather than leased to a single large one. Providers pushed back. Some Nvidia employees warned customers the terms could attract antitrust attention. The economics were small enough that Nvidia could have absorbed them without noticing. The control clauses were the part worth having.
Colette Kress spent Wednesday’s earnings call telling investors the revenue share could produce billions of dollars over the medium to long term. By the time she said it, the deal team had already put parts of the program on hold. Nvidia’s own filing, published the same day, describes a structure that shrinks whenever the cloud provider finds an outside tenant. The term sheet, as reported, restricted which outside tenants qualified. Those two documents describe different products.
What Happened
Nvidia paused some deals under the AI Compute Partnership last week, according to reporting from The Wall Street Journal citing people familiar with the arrangements. The program launched seven weeks earlier. Nvidia has left open the option of reworking it or folding it into another initiative.
The company did not confirm the pause. A spokesperson said the July business model is “still in place and continues to evolve due to high demand,” language that Tom’s Hardware treated as a denial and that stops short of addressing individual deals. Nothing in the 10-Q says any portion was suspended.
Two things landed in the same 48 hours. Nvidia reported a record quarter on Wednesday: revenue of $96.221 billion, data center revenue of $89.023 billion, net income of $59.688 billion, gross margin at 75.0%, third-quarter guidance of $108 billion, and a fiscal 2028 growth guide near 70%. The stock closed up 9% on Thursday. It gave back about 1% after hours once the pause was reported.
The same filing put a number on the program for the first time. Nvidia’s AI cloud commitments “decrease as capacity is used by third-party customers” or by Nvidia for its own research and development. If certain criteria are met, Nvidia participates in the revenue the AI clouds earn from those third parties.
The Backstory
The AI Compute Partnership solved a real problem. A cloud operator building an AI factory has to buy billions of dollars of GPUs and pour a data center before it has signed enough customers to borrow against. Lenders want contracted revenue. Contracted revenue requires capacity that does not yet exist.
Nvidia offered to be the tenant of last resort. If the provider could not sell the capacity, Nvidia would rent it. That commitment turned a speculative build into a financeable one. In exchange, Nvidia and the provider would set a base hourly rate covering the provider’s costs, including depreciation on the Nvidia chips, the data center, and staffing. Above that base, Nvidia would take 50% of the revenue.
Sharon AI and Firmus Technologies signed first, both announced July 1. Sharon AI is deploying up to 40,000 Grace Blackwell GB300 GPUs. Firmus is building a 360-megawatt campus in Batam, Indonesia, sized for up to 170,000 GPUs. The two deals cover roughly 210,000 GPUs.
This is the third distinct instrument Nvidia has built in a year for pushing capital toward its own customers. It follows the CoreWeave backstop signed in 2025, worth $6.3 billion through 2032, and the six-firm platform announced in August with Apollo, BlackRock, Blackstone, Brookfield, Goldman Sachs and KKR to mobilize more than $500 billion of third-party capital. On the earnings call, BofA’s Vivek Arya added up the commitments and guarantees in the CFO commentary and arrived at roughly $500 billion.
The Plan
Read the reported terms as a whole and the financing looks like packaging.
Start with what Nvidia was risking. Thirty-six billion dollars of commitments across six years averages about $6 billion a year, against a company that earned $59.688 billion of net income in the June-to-July quarter alone. The entire six-year book equals about 60% of one quarter’s profit. Nvidia can satisfy the obligation by taking the capacity and running its own workloads on it, which the filing names as one of two ways the commitment decreases.
Now look at what Nvidia was collecting. Kress sized the revenue share in billions over the medium to long term for a company guiding to roughly 70% revenue growth next fiscal year. Morgan Stanley modeled this stream in August assuming Nvidia captured 35% of the usage surplus, which produced about $51 billion of potential annual revenue at margins near 100%. The reported term is 50%. On the bank’s own assumption set, a 50% capture rate scales that figure past $70 billion. The sell side was conservative on the rate, and the program stalled anyway. Price was not the friction.
Finally, look at what Nvidia fought for. Approved-customers-only and a stated preference for several small tenants over one large one are not underwriting terms. A guarantor standing behind a revenue floor wants the most creditworthy tenant available, which in this market means the biggest. Nvidia wanted the opposite. That preference only makes sense if the objective is the composition of the buyer base rather than the recoverability of the guarantee.
The Business Model Angle
The clearest evidence sits in the gap between Nvidia’s filing and Nvidia’s term sheet.
The 10-Q describes third-party demand as the release valve. Every outside customer the provider signs retires part of Nvidia’s obligation. That is the disclosed de-risking mechanism, and it is the sentence a credit analyst reads to size the exposure. The reported operating terms then narrowed the set of outside customers the provider was allowed to sign. Nvidia built an escape hatch and put a lock on the door it opens onto.
A program cannot be optimized for shrinking Nvidia’s exposure and for controlling who the tenants are. Those goals pull against each other, and the version in the filing is the one investors were shown.
The fragmentation preference decodes cleanly once you look at who Nvidia’s threats are. Six of the ten firms on our ranking of Nvidia’s most serious competitors are also its customers. Google, Amazon, Meta, Microsoft, OpenAI and Broadcom’s XPU clients all crossed the same threshold: they got large enough that designing their own accelerator became cheaper than paying Nvidia’s margin on their own workloads. Below that threshold, a buyer rents. Above it, a buyer builds.
A term sheet that spreads GPU capacity across several small AI companies keeps buyers below that line. Nvidia argues the same position in public, lobbying for open weights and a broad, fragmented model layer because a wide buyer base cannot organize against its pricing. The AI Compute Partnership converted that argument into a contract clause. That is the part with no benign reading available, and it is why customer allocation by a dominant supplier makes lawyers nervous in a way that a revenue split does not.
There is a second cost, borne by the partner. Under a 50/50 split above cost recovery, the provider’s entire equity return is its half of the surplus, while it carries all of the utilization risk, the power price risk, and the obsolescence risk beyond whatever the floor covers. Huang published Nvidia’s own rate data this month: B200 cloud rates ran roughly $5.30 to $7.05 per GPU-hour in mid-2026. On these terms, every dollar of rate improvement a provider wins from a tight market is worth fifty cents to it and fifty cents to a supplier already paid in full for the hardware. Sharon AI and Firmus were being asked to run capital-intensive infrastructure businesses on half the upside and a restricted customer list.
The Risk
Nvidia paused the instrument designed for many small buyers in the same month it expanded the one designed for its largest single customer.
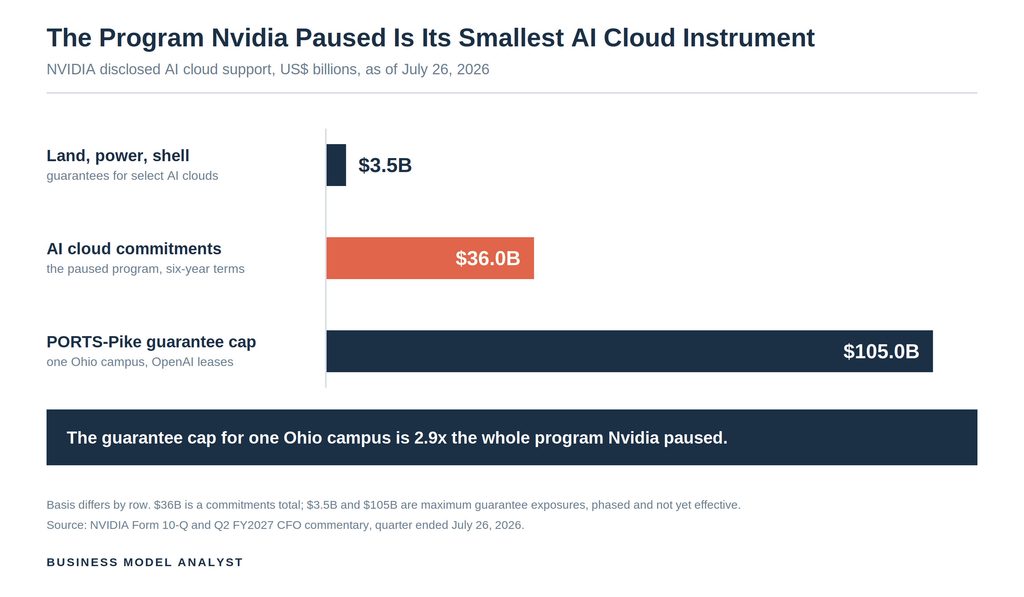
In August, Nvidia entered guarantees supporting the land, power and shell buildout for roughly 4.25 gigawatts at SB Energy’s PORTS-Pike Technology Campus in Ohio, a site that will host Nvidia infrastructure exclusively under 20-year leases to OpenAI. The guarantee obligations are capped at $105 billion, phased against conditions including data centers reaching service readiness, with the first tranche expected in fiscal 2029. Separate land, power and shell guarantees for other AI cloud partners carry a maximum gross exposure of $3.5 billion.
Set those against the $36 billion. Nvidia’s guarantee cap for one customer’s campus is 2.9 times the entire multi-partner program it stepped back from. If the concern driving the pause was Nvidia using its balance sheet to shape demand, the net effect of the last month is a balance sheet pointed harder at a single counterparty, not a diversified one.
The reallocation shows elsewhere too. Days sales outstanding moved from 45 to 60 in a quarter as Nvidia extended payment terms on large deals with investment-grade customers, pushing accounts receivable to $63.1 billion. Equity investment commitments stand at $25 billion, of which $18 billion falls in the remainder of fiscal 2027.
The counterarguments deserve room. Nvidia has not confirmed a pause, and its statement points at a program that keeps evolving rather than one being withdrawn. The credit-quality defence for customer approval is legitimate on its face, since a guarantor vets the tenants whose rent it is standing behind, though that logic argues for larger tenants rather than smaller ones. Immateriality cuts both directions: if $36 billion is small relative to Nvidia, so is pausing it, and seven-week-old commercial products get revised without anyone calling it a retreat. And employee anxiety about antitrust is not enforcement. No agency has moved on this program, and vertical restraints are judged under the rule of reason rather than banned outright.
Quick Questions
Did Nvidia cancel the program? No. The reporting describes a pause on some deals, with the option to rework the structure or fold it elsewhere. Nvidia says the July model remains in place.
Is the $36 billion an expense? No. It is a commitments total that shrinks as third-party customers take the capacity, or as Nvidia absorbs it for research and development. It is closer to a contingent purchase obligation than a cash cost.
Why is customer approval an antitrust question when a revenue share is not? Splitting revenue is a pricing term between two willing parties. Telling a buyer which customers it may resell to is customer allocation, and courts treat restraints imposed by a dominant supplier on downstream distribution with more suspicion than pricing terms. Nvidia already carries open files with the DOJ, the EU and China’s SAMR, a backdrop we covered in our Nvidia SWOT analysis.
How does this relate to the 25% residual backstop? They are two arms of the same shift from selling hardware to metering its use. We covered the first arm in Nvidia’s 25% backstop and the toll booth it bought. The AI Compute Partnership is the version aimed at smaller clouds rather than institutional capital.
What would prove this reading wrong? Watch what comes back. If Nvidia revives the program and drops the customer-approval right, the control was the product and it gave that up. If the revived version keeps the clause, the reporting overstated how much friction it caused.
The Business Model Analyst Take
Nvidia sells the best accelerator in the world at 75% gross margins and cannot make enough of them. It does not need $6 billion a year of committed cloud spend, and it does not need a revenue share that Kress can only size in billions against a business heading toward roughly $673 billion of revenue.
What Nvidia needs is a customer base that stays too small to build its own chips. That is the asset the AI Compute Partnership was buying, and the price was a revenue floor plus half the upside.
The lesson generalizes past semiconductors. When the thing protecting your margin is the shape of your customer base, and you have to write that shape into a contract to keep it true, the protection has already stopped working on its own. Fragmentation you have to purchase is not a market structure. It is a subsidy with a renewal date, and every renewal is a chance for the counterparty to ask for better terms or for a regulator to ask what the clause is doing there.
Nvidia’s own employees appear to have worked this out before its deal team did. Go read your standard commercial terms with one question in hand: which of them manage risk, and which of them manage your customers? The second group is where your lawyers and your competition authority will both start.
Reporting on the pause and the deal terms: Anissa Gardizy and Berber Jin, The Wall Street Journal, August 27, 2026. Financial data from NVIDIA’s Form 10-Q and CFO commentary for the quarter ended July 26, 2026.