
Apollo, BlackRock, Blackstone, Brookfield, Goldman Sachs and KKR signed letters to fund Nvidia’s customers. The two deals this copies both forced a chipmaker to guarantee what the silicon would be worth at the end. Nvidia’s announcement says nothing about that.
Nvidia announced memorandums of understanding with six of the largest capital allocators on earth to build financing platforms aimed at mobilizing more than $500 billion of third-party money for AI infrastructure. The number is not the story. The company also told bond buyers, in a press release, that its chips have the “longest life” in compute, which is the claim the entire structure rests on and the one nobody has priced.
Jensen Huang put four words at the center of the announcement: “In AI, compute is revenue.” Strip the marketing and that is a securitization pitch. Toll roads, fiber, and power plants get financed at scale because they throw off contracted cash for twenty years and nobody invents a better road. Huang is asking Apollo and KKR to treat a GPU the same way, and Nvidia’s own product calendar is the reason they might not.
What Happened
On Monday afternoon, Nvidia said it had signed MOUs with Apollo, BlackRock, Blackstone, Brookfield, Goldman Sachs and KKR to create independent compute financing platforms. The stated goal is more than $500 billion of third-party capital over time, deployed into dedicated capital pools that lend to Nvidia customers so those customers can buy Nvidia systems. Frontier labs, enterprises and neoclouds are the named targets. The Financial Times reported the talks first, and Bloomberg and Reuters confirmed them before the company release landed.
Two qualifiers sit in the document itself. These are memorandums, not contracts, and Nvidia says the partnerships remain subject to execution of final agreements. The $500 billion is a target “over time,” with no projects, no tenors, and no pricing attached.
Nvidia stock fell roughly 3% on the day. For a company whose announcements usually add market value, a selloff on a half-trillion-dollar capital commitment is the most informative part of the tape.
The Backstory
Nvidia does not need money. In its first fiscal quarter of 2027 the company reported $81.6 billion of revenue, up 85% year over year, with $75.2 billion of that in data center. Gross margin came in at 74.9%. Free cash flow hit $48.6 billion in a single quarter. Management raised the dividend twenty-five fold and authorized another $80 billion of buybacks. That balance sheet does not organize half a trillion dollars of outside lending because it is short of cash.
Its customers are short of cash. Moody’s counted $785 billion of hyperscaler capex for 2026 heading toward roughly $1 trillion next year, sitting on top of $1.2 trillion in data center lease commitments, more than $820 billion of which covers facilities nobody has finished building. Alphabet posted negative free cash flow of $5.9 billion in a $44.9 billion capex quarter, a shift we covered in Google’s $514 billion cloud backlog. Microsoft moved AI spending off its headline capex line through a lease reclassification, which we took apart in Microsoft’s $15 billion capex “cut”.
So the binding constraint moved. For three years Nvidia’s problem was fabricating enough silicon. The problem now is that the marginal buyer of an AI factory has run out of balance sheet, and Nvidia has decided to manufacture one.
Bond investors noticed before the equity market did. Since June, lenders have doubled the extra yield they demand to hold Nvidia paper, to about 0.40 percentage points over comparable Treasuries, according to pricing service Solve. Credit repriced Nvidia while the stock was still making highs.
The Plan
Read Huang’s quote as a credit memo rather than a keynote line. He argues Nvidia compute is “broadly adopted, flexible across models and workloads, fungible and transferable across customers and operators,” and that CUDA keeps “extending its useful life and improving its economics over time.” Each clause maps onto a lender’s checklist. Fungible and transferable means the collateral has a resale market. Extending useful life means the asset outlives the loan. Broadly adopted means the buyer pool survives a default.
Every one of those claims is contested, and the contest is expensive. Michael Burry’s argument, which moved from accounting newsletters to CNBC over the past year, is that hyperscalers depreciating GPUs over five and six years while Nvidia ships a new architecture annually are understating depreciation by something like $176 billion across 2026 to 2028. Amazon already shortened the life on a subset of its servers, citing the pace of AI development, and took a $700 million hit to operating income for the privilege. Meta went the other way in the same window. Two audit committees, the same hardware, opposite answers. We ran the same test on SpaceX’s numbers in its AI capex payback claim.
Nvidia controls the variable in dispute. Hopper landed in 2022, Blackwell in 2024, Vera Rubin arrived in March 2026, and Rubin Ultra is slated for 2027. Each generation drops the cost per token enough to make the prior one uncompetitive for frontier training inside two or three years. The company selling the obsolescence is now underwriting the durability.
The Business Model Angle
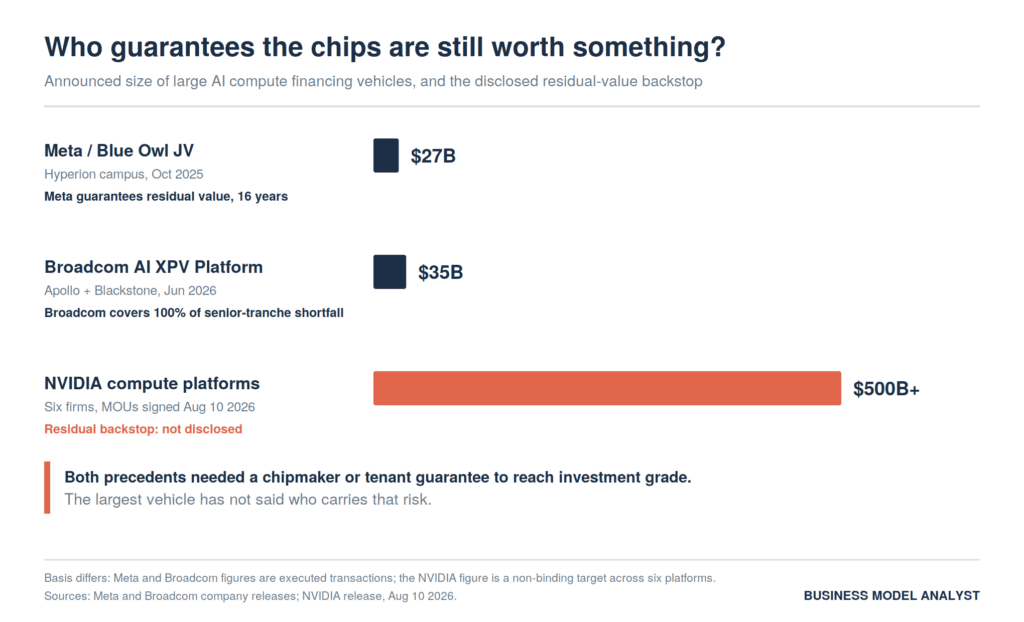
Two deals already built the structure Nvidia is copying, and both answer the residual question in writing.
Meta financed its Hyperion campus in Louisiana through a joint venture with Blue Owl, keeping 20% of the equity and pushing roughly $27 billion of debt off its own books. PIMCO anchored the paper and S&P stamped it A+. Meta got that rating by handing the venture a residual value guarantee covering the first sixteen years of operation, promising a capped cash payment if the campus lost value after a lease terminated. BlackRock later took 80% of a similar El Paso structure, which we covered in the $12 billion Texas data center deal.
Broadcom did the same thing two months ago with the same two firms now sitting at Nvidia’s table. Apollo led a $35 billion tranche alongside Blackstone’s credit and insurance arm to fund Anthropic’s compute expansion through the AI XPV Platform. Reporting on the structure describes the SPV selling the chips to repay lenders on a default, with Broadcom covering 100% of any shortfall to the senior tranches. That guarantee is what dragged the top of the capital stack up near Broadcom’s own investment-grade rating without landing on Broadcom’s balance sheet.
Nvidia’s release contains no equivalent sentence. It contains adjectives.
Which leaves two paths when the final agreements get written, and they lead to different companies. If Nvidia guarantees the residual, the $500 billion becomes a contingent liability attached to a business that has never carried one at this scale, and the “independent” and “third-party” framing collapses into vendor financing with more counterparties. If Nvidia refuses, the senior paper prices wide of investment grade, insurance balance sheets cannot hold much of it efficiently under current capital rules, and the $500 billion target shrinks to whatever equity-like return the market demands for owning three-year silicon.
Anyone reading the announcement as a de-risking of the Nvidia business model should hold that view lightly until they see which one Nvidia signed.
The Risk
The word “independent” is doing heavy work. Nvidia is a founding investor in KKR’s Helix Digital Infrastructure, launched in June with more than $10 billion of committed capital and Adam Selipsky as CEO. Nvidia joined BlackRock’s AI Infrastructure Partnership last year as a technical adviser. Brookfield announced a $100 billion AI infrastructure program with Nvidia in November. Four of the six firms already had capital deployed alongside Nvidia before Monday. A financing platform whose sponsor holds equity in the platform, sells the collateral, and owns stakes in the borrowers is not a clean transfer of risk. It is a longer chain.
The other end of that chain is where this gets uncomfortable. Apollo owns Athene. KKR owns Global Atlantic. Barclays put private credit at roughly 10% of US life insurer assets and above 15% at private-equity-affiliated insurers, and the NAIC gave its valuation office new authority this January to challenge ratings it considers generous. Private credit lending to AI companies went from near zero to more than $200 billion in a few years, and Morgan Stanley projects another $800 billion of data center financing from that channel over the next two. Nvidia’s single announcement is more than half of that projection. Retirement money with thirty-year liabilities is being asked to fund assets Nvidia replaces every two.
History gives the pattern a name. McKinsey put combined vendor financing exposure across nine telecom equipment suppliers at about $25.6 billion by the end of 2000. Lucent alone committed roughly $8.1 billion and then wrote off $3.5 billion in customer loan losses across fiscal 2001 and 2002. Nvidia’s target is close to twenty times the entire telecom-era total in nominal terms, and roughly ten times after inflation.
The honest counterargument deserves space, because the analogy is imperfect in Nvidia’s favor. Lucent lent its own money and booked the receivables. Nvidia is signing MOUs with allocators deploying client capital, which is a different legal animal and a real distinction. Nvidia’s customers are also not the revenue-free CLECs of 1999. OpenAI and Anthropic collect billions in actual subscription and API revenue. And the residual data is better than the bears allow: American Compute’s June report, built on more than 76,000 completed secondary-market transactions, argues GPU useful life can reach eight years and that lenders can book residuals above 10% of equipment cost over a five-year term. Both of those points are real. Neither of them tells you who eats the gap in a downside, which is the only question the final agreements will settle.
Quick Questions
Is Nvidia lending its own money? Not under this announcement. The six firms would raise and deploy third-party capital through platforms Nvidia describes as independent. Nvidia’s exposure depends on guarantees that have not been disclosed.
Is the deal final? No. Nvidia signed memorandums of understanding and states the partnerships remain subject to execution of final agreements. No projects, tenors or pricing have been announced.
Why did the stock fall on good news? A supplier with 75% gross margins organizing customer credit reads as a demand signal, not a supply one. Investors also cannot tell yet whether Nvidia will end up backstopping the paper.
What is residual value and why does it decide this? It is what the hardware fetches at the end of a loan. Lenders size and price debt against it. If a GPU holds value for six years, the paper works at investment grade. If it holds for three, the same paper is high yield.
Who ultimately holds the risk? Insurance and retirement portfolios, in large part. Apollo’s Athene and KKR’s Global Atlantic sit behind a growing share of private credit, and regulators started asking about it this year.
When will we know more? Nvidia reports second-quarter results on August 26, and the final agreements will define the guarantees. Watch for any contingent-liability language in the filings rather than the press releases.
The Business Model Analyst Take
Nvidia spent a decade convincing the world that its chips were scarce. It now needs to convince a different audience that they are durable, and those two arguments pull against each other. Scarcity comes from the annual cadence that makes last year’s rack a poor bet. Durability is what makes a rack financeable for eight years. You can sell either story. Selling both to the same room is harder.
The company has a real answer available, and it is the one Broadcom and Meta already gave: put the guarantee in writing and take the residual risk onto its own balance sheet, where 75% gross margins and $48 billion of quarterly free cash flow can absorb it. That would be the strongest possible statement of confidence in the product. It would also convert Nvidia from a chip company into a leasing company with a fab-less design arm attached, and the market would reprice it accordingly. The margin migrates toward whoever owns the constrained input, which is the argument we made in the AI bubble margin migration piece, and residual risk is how that ownership eventually gets paid for.
The alternative is that nobody guarantees anything, the platforms fund the credits that already work, and $500 billion turns out to describe a ceiling rather than a plan. Nvidia has done this before. It committed up to $100 billion to OpenAI as a non-binding letter of intent, put $5 billion into Safe Superintelligence for research access rather than returns, and is reportedly discussing a $250 billion backstop for an OpenAI data center project. Announced capital and deployed capital have been running on separate ledgers for a year.
Read the final agreements, not the headline. The number that matters is not $500 billion. It is whatever percentage of a shortfall Nvidia agrees to cover, and that number is currently blank.