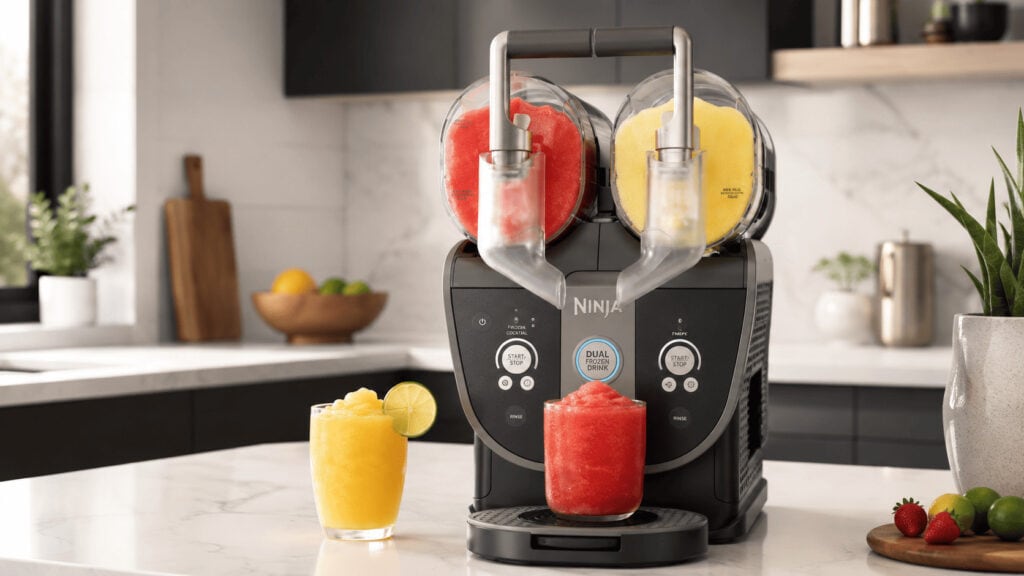

Reviewers are calling the Ninja Slushi Twist a summer lifesaver. Inside SharkNinja, it is something less charming: a rescue mission for the one product line that stopped growing.
The frozen drink maker went on sale in May 2026 at $399.99, sold out almost immediately, and has spent the last two months collecting glowing coverage from outlets testing it through a brutal East Coast heat wave. TechCrunch published its review on July 11. The machine has two independent 48-ounce chambers, senses what is in each one, and can swirl two flavors into a single glass.
That is the consumer story. The business story is buried in SharkNinja’s Q1 filing, and it is more interesting.
What Actually Happened
SharkNinja (NYSE: SN) launched the original Ninja Slushi in 2024 at $269.99. It used a technology called RapidChill to freeze liquid without ice, which meant no watered-down margaritas and no crunchy blender texture. TikTok did the rest. Retailers could not keep it in stock. The company followed with the Slushi Max, and now the Slushi Twist, which quietly went on sale and sold out on SharkNinja’s own site before most of the tech press noticed.
Three SKUs, roughly two years, and a price ladder that climbed from $269.99 to $399.99. That is a 48% increase in the top-of-line price of a product category that did not exist inside SharkNinja before 2024.
Meanwhile, the original Slushi has been discounted aggressively in 2026. Amazon dropped it to $259, and Best Buy has run it at $199.99 against a $349.99 list price. Deep, repeated discounting on the hero SKU of a viral franchise is rarely a sign of a category that is still accelerating.
The Number That Explains the Launch
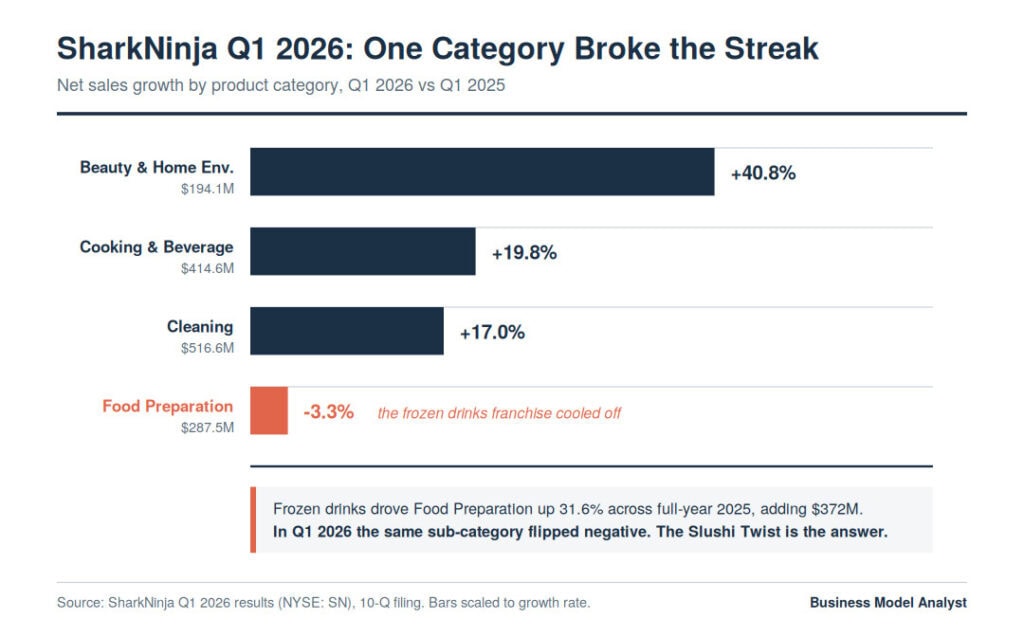
SharkNinja reports revenue across four product categories. In Q1 2026, three of them grew and one did not.
Cleaning Appliances rose 17.0% to $516.6 million. Cooking and Beverage Appliances rose 19.8% to $414.6 million. Beauty and Home Environment Appliances rose 40.8% to $194.1 million. Food Preparation Appliances fell 3.3% to $287.5 million.
The company’s own filing names the culprit: the decline was driven by weakness in the frozen drinks sub-category, partially offset by strength in blending.
That is a reversal, not a wobble. Across full-year 2025, Food Preparation was SharkNinja’s fastest-growing category in dollar terms, up 31.6% and adding $372 million in net sales, and the filing credits frozen drinks specifically. The Slushi carried the category. One year later it is dragging it.
Why It Matters
SharkNinja is a $21 billion company that grew from roughly $250 million in revenue in 2008 to $6.4 billion in 2025, a compound annual growth rate of about 21%. It has now posted 12 consecutive quarters of double-digit organic net sales growth. The stock trades near $152, close to its 52-week high of $154, and analysts at BofA and Guggenheim raised price targets in early July, to $165 and $175 respectively, citing strong Q2 sell-through.
That streak is the entire investment thesis. And the streak depends on a specific mechanic: SharkNinja does not defend categories, it manufactures new ones, rides the viral spike, then extends the franchise before the spike decays. The company competes in 39 sub-categories and commits to launching roughly 25 new products a year.
The Slushi is the cleanest example of the mechanic working. It is now also the cleanest example of the mechanic’s weakness. Viral hardware categories have a half-life. The Creami did this. The Slushi is doing it now. The question every SharkNinja investor should be asking is whether the sequel is enough to reset the clock, or whether it just harvests the existing installed base at a higher price.
The Business Model Underneath
Strip away the slushies and SharkNinja runs a fairly ruthless three-part engine.
Adjacency attack. The company enters categories where an incumbent has grown lazy on margin, ships a product at 60 to 80% of the premium price with most of the performance, and takes share. Vacuums against Dyson. Blenders against Vitamix. Espresso against the traditional machine makers, via the Ninja Luxe Cafe, which is now a named growth driver in Cooking and Beverage. Most recently, skincare, where Beauty and Home Environment grew 40.8% in Q1 on the back of new skincare SKUs.
Virality as a distribution channel. These products are engineered to be filmed. The original Slushi launched with a “Will It SLUSHi?” influencer campaign across 26 creators. CEO Mark Barrocas has told analysts the company is “becoming part of culture.” That is not a soft brand statement, it is a customer acquisition cost statement.
The sequel ladder. Launch, go viral, then extend upward with a premium follow-on before the original commoditizes. Slushi at $269.99, Slushi Max, Slushi Twist at $399.99. Same playbook the company ran with the Creami.
The Twist is step three of a playbook the company has run many times. What is new is that the filing shows step three arriving after the franchise had already turned negative, not before.
The Supply Chain Advantage Nobody Talks About
SharkNinja began moving manufacturing out of China in 2018, during the first round of US tariffs. By 2025 it had shifted nearly all US-bound production to Vietnam, Thailand, Indonesia, Malaysia and Cambodia, and it dual-sources most SKUs across multiple factories.
That head start is now a structural advantage. Barrocas has told analysts the company can shift orders between plants when a factory pushes on price. Tariffs still bit: CFO Adam Quigley called them a sizable headwind, and gross margin compressed 100 basis points on an adjusted basis to 49.2% in Q1. But SharkNinja is absorbing that while still raising guidance, which is not something most consumer hardware companies managed this cycle.
For founders, this is the underrated lesson. The viral product gets the coverage. The five-year supply chain hedge is what lets the company keep shipping 25 new products a year while competitors are stuck renegotiating landed cost.
The Skeptic’s Case
Three things should make you uncomfortable.
The sequel may cannibalize rather than expand. A household that bought a $270 Slushi in 2024 is not an obvious buyer of a $400 Slushi in 2026. The addressable buyer for the Twist is either a new household or an upgrader, and the original is being discounted into the ground at the same time, which suggests the new-household pipeline is not what it was.
Novelty categories decay faster than core ones. Frozen drinks is a seasonal, discretionary, single-use appliance in a kitchen with finite counter space. The Twist is explicitly larger than the original. That is a real constraint on repeat purchase, and it is the reason SharkNinja keeps needing new categories rather than deeper penetration in old ones.
Margin is going the wrong way while opex goes up. Gross margin fell, advertising and R&D spend rose, and net income grew just 3.1% against 15.6% net sales growth. The growth is real. It is also getting more expensive.
The counter to all three: SharkNinja’s diversification is working exactly as designed. Frozen drinks went negative and total net sales still grew 15.6%, because skincare, espresso and carpet extractors picked up the slack. That is the whole point of running 39 sub-categories. No single viral hit needs to last forever.
What To Watch
August 6, 2026. That is the Q2 print, and it is the first quarter that will contain a meaningful contribution from the Slushi Twist.
The line to read is not the headline net sales number. It is the Food Preparation category and the sub-category commentary underneath it. Management said on the Q1 call that frozen treats remain a growth area with more innovation coming in the second half. The Twist is that innovation. If Food Preparation is still negative in Q2, the sequel did not work and SharkNinja’s franchise-extension playbook has a demonstrated failure case. If it swings back to growth, the playbook is validated and the company has proven it can resuscitate a decaying viral category on demand, which is arguably a more valuable capability than launching one in the first place.
Also worth tracking: the $750 million buyback authorization approved this year, of which only about $20 million had been executed through March. Management is holding fire.
Comparable Playbooks
The instinct is to compare SharkNinja to Dyson, and on the product level that is right. Strategically, the closer comparison is the Peloton business model: a hardware company that rode a cultural moment, then discovered that a viral installed base is not the same thing as a durable revenue base.
The difference is that Peloton bet the company on one category. SharkNinja bets on the rate at which it can enter categories. In Ansoff Matrix terms, SharkNinja lives permanently in the product development and diversification quadrants, which is the highest-risk pair on the grid. It survives there by running so many bets that no single failure is fatal.
The Slushi Twist is one of those bets. It is a good one, priced with a textbook premium pricing strategy. But it is a bet placed on a table that was already turning cold.
Frequently Asked Questions
How much is the Ninja Slushi Twist and what does it do? It sells for $399.99 and has two independent 48-ounce chambers that can produce two different frozen drinks at once, using what Ninja calls Dual SlushAssist technology to adjust freezing temperature per chamber. It can make slushies, frappes, milkshakes, frozen coffees and smoothies, and can swirl both flavors into one glass.
Is the frozen drinks business actually in trouble at SharkNinja? It declined in Q1 2026. SharkNinja’s filing attributes the 3.3% drop in Food Preparation net sales to weakness in the frozen drinks sub-category. Whether that is a permanent decay or a tough comparison against a very strong Q1 2025 will not be clear until the Q2 results on August 6, 2026.
How does SharkNinja make money? It sells small household appliances under two brands, Shark and Ninja, across four reported categories: Cleaning, Cooking and Beverage, Food Preparation, and Beauty and Home Environment. Full-year 2025 net sales were $6.4 billion. It is a hardware business with no meaningful subscription revenue, which is why launch cadence matters so much to the model.
Who are SharkNinja’s main competitors? Dyson in floorcare, Vitamix and Breville in food prep and coffee, Instant Brands and Whirlpool in cooking, and Dyson again in beauty. See our Dyson SWOT analysis for the incumbent side of that fight.
Is SharkNinja exposed to tariffs? Yes, but less than most peers. It began shifting production out of China in 2018 and had moved nearly all US-bound manufacturing to Southeast Asia by the end of 2025. Tariffs still compressed adjusted gross margin by 100 basis points in Q1 2026.
The Business Model Analyst Take
SharkNinja is one of the best-run consumer hardware companies in the world, and the Slushi Twist is a good product. Both things can be true alongside a third: this launch is defensive, and the company’s own filing says so.
The lesson for operators is not “go viral.” It is that virality is a loan, not an asset. It pulls demand forward and it always comes due. SharkNinja’s real competence is not that it made a slushie machine people filmed themselves using. It is that the company built a portfolio wide enough, and a supply chain flexible enough, that when the slushie machine cooled off, the quarter still grew 15.6% and the stock still hit a 52-week high.
Most companies that catch a viral product build the whole business on it. SharkNinja treats each one as a disposable engine, and keeps a dozen more on the workbench. That is the model. The Twist is just this quarter’s proof.
Watch August 6.