
China’s fitness boom is real. The business model question is whether brand premium survives a market that keeps punishing anything mainstream.
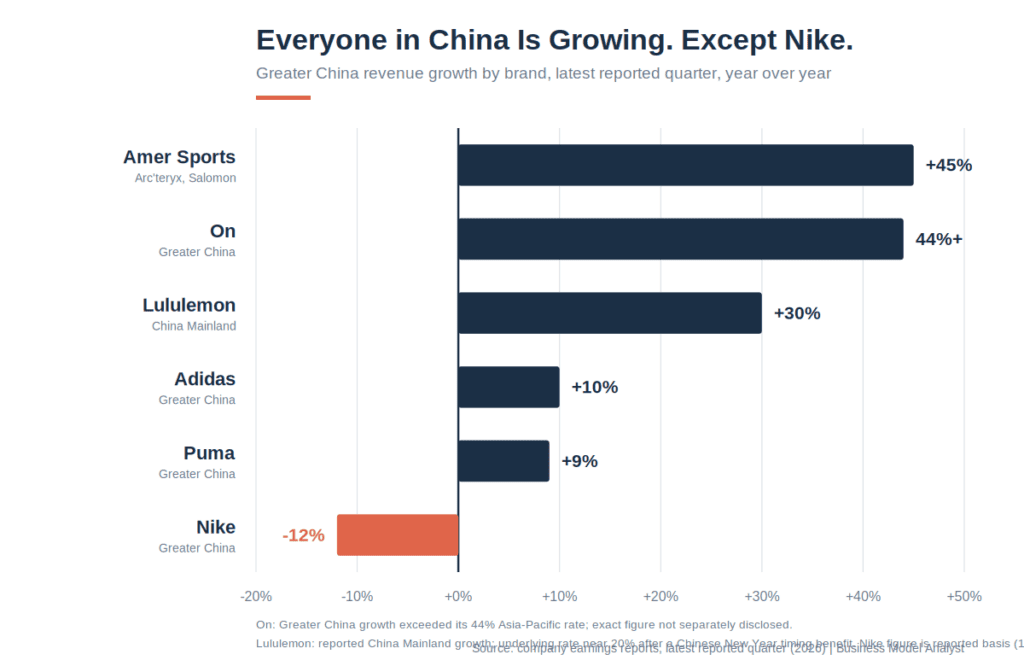
China’s fitness craze has lifted athletic apparel sales while cars and luxury sag. Amer Sports, On, and Lululemon are growing fast there. Nike is not, with Greater China revenue down 12% last quarter and off roughly 29% from its peak five years ago. The business model lesson sits in that gap.
Office workers from Chongqing and Shanghai now spend their weekends on the limestone cliffs of Yangshuo, a rock-climbing town that used to draw mostly American and European tourists. They are chasing an escape from high-pressure jobs, and they are buying gear to do it. That single scene captures a rare bright spot in a soft Chinese economy, and it hides a harder question for the Western brands cashing in: how long does any of them stay on top.
What Happened
The numbers behind China’s fitness boom are large and moving fast. Marathon participation has doubled since 2017 to more than a million people. Hyrox, the run-and-lift competition, grew from 7,300 participants in China to 55,000 in a single year. The central city of Hebi built around 1,600 pickleball courts and counts roughly 300,000 players. Rock climbing, padel, and Pilates are spreading through the big cities.
Gear sales followed. On said its Greater China quarterly growth ran ahead of its 44% Asia-Pacific rate, and its Asia-Pacific chief called premium the fastest-growing slice of the market. Amer Sports, owner of Arc’teryx and Salomon, posted about 45% Greater China growth in its latest quarter. Puma booked a 9% Greater China gain as Hyrox’s official apparel partner. Adidas grew around 10%. Lululemon reported a 30% jump in China Mainland revenue.
Then there is Nike. Greater China revenue fell 12% on a reported basis last quarter, and 17% in currency-neutral terms. The region has declined every quarter of Nike’s fiscal 2026, and revenue there sits about 29% below its peak. One market, two directions.
The Backstory
Chinese consumers traced the shift to the pandemic. A Shanghai yoga-studio owner who goes by LynnLight told the Wall Street Journal that after Covid, people started asking what they wanted from life beyond work. “Health is kind of the new wealth in China,” said On’s Rebecca Cai. Wellness became a status marker, and premium athletic gear became the uniform for it, worn by people who work out and plenty who do not.
That timing rewarded brands with a fresh identity and punished the incumbent. For most of the last decade the Nike business model looked close to untouchable in China: an asset-light design-and-marketing engine that outsourced manufacturing and printed cash on brand strength. The engine stalled. Fiscal 2025 revenue fell 10% to $46.3 billion, the steepest annual drop in over a decade, and net income dropped 44%. China turned from Nike’s growth story into its problem child, with local rivals like Li-Ning and Anta taking share and CEO Elliott Hill admitting on the last earnings call that “the results aren’t there yet.”
Lululemon’s arc points the other way, for now. Its China Mainland business grew to 19% of total revenue, up from 16% a year earlier, and became the one region carrying the company while North America shrank.
The Plan
Lululemon is putting its capital where the growth is. Of the 25 to 30 international stores it plans to open in 2026, the majority land in China, where it ended the first quarter with 173 locations. It runs a “Summer Sweat Games” event series across Chinese cities, complete with kettlebell and pull-up competitions, and it staged a 2,000-person yoga event on the Great Wall. The pitch to investors is double-digit China growth for years.
The challengers are localizing hard. On tailors products to Asian body sizes and sells UV-protective shirts for runners worried about sun exposure. Homegrown Maia Active, owned by Anta, undercuts Western prices with clothing cut for Asian proportions. Xtep churns out running shoes in the $30 to $75 range while owning the China business of elite American brand Saucony. Alo, one of Lululemon’s sharpest Western rivals, opened its first Chinese social accounts last month and posted “Hello China” on WeChat.
Nike is running the counterattack under its “Win Now” plan: rebuild wholesale, clear inventory, introduce China-designed products, and chase fast-growing formats like Hyrox with dedicated training camps. Hill says a full recovery waits until fiscal 2027.
The Business Model Angle
The instructive pattern is what novelty does to brand value in this market. A BNP Paribas analyst calls it the “microbrew effect”: Chinese consumers keep hunting new flavors, so scale and ubiquity turn into liabilities rather than moats. That inverts the Western apparel playbook, where wider distribution compounds brand power. In China, the brand everyone already owns becomes the brand nobody wants to be seen in.
Nike is the finished case study. It spent two decades becoming the default, and the default is exactly what younger Chinese buyers now skip. A Shanghai content creator told the Journal she quit Lululemon once it felt too mainstream and moved to Alo. The same sentence, five years from now, could name any brand riding high today.
That reframes where value gets captured. It flows to whoever holds the novelty position this season: a fresh Western entrant like On or Alo, a technical-status brand like Arc’teryx, or a local champion like Anta that owns both the price advantage and the cultural fluency. Premium pricing power in China is a rental, not a deed. You keep paying to hold it, through events, product churn, and marketing spend, and the moment you coast, a fresher name takes the lease. Lululemon lifted marketing to roughly 6% to 6.5% of sales and cut a fifth of the products on its store floors so new styles stand out. That is the rent coming due.
The Risk
The bet has a visible downside. Lululemon leaned its entire growth narrative on the single most competitive and most politically sensitive retail market it operates in, and it did so while profit fell apart at home. Group operating income dropped 37% in the first quarter, North America comparable sales fell 6%, and the company cut full-year earnings guidance to about $11 per share from $13.26 the year before. China is not a cushion on a strong base. It is the base.
Nationalism raises the stakes further. Lululemon brought out Japanese drums at that Great Wall event in May and triggered a wave of online anger before apologizing. One cultural misread can erase a season of goodwill in the exact market the company now depends on. Nike learned the cost of a China slide the slow way, over five years. A boycott can deliver it in five days.
The honest counterpoint: Lululemon’s China business is young and small next to Nike’s, at 173 stores and 19% of revenue, so its underlying 20% growth reads more like early innings than late-Nike saturation. The trend that broke Nike has not broken Lululemon. The warning is that the same market mechanics apply to both, and Lululemon is accelerating into them rather than hedging against them.
Quick Questions
Why is Nike losing in China while rivals grow? Chinese consumers are shifting toward newer brands and local champions like Anta and Li-Ning. Nike’s scale, its biggest historical advantage, now works against it in a market that rewards novelty. Greater China revenue fell 12% last quarter and sits about 29% below its five-year peak.
Is China really Lululemon’s main growth engine? Yes. China Mainland grew about 30% last quarter and now makes up 19% of revenue, while North America comparable sales fell 6%. Most of Lululemon’s 2026 international store openings will happen in China.
What is the “microbrew effect”? A term a BNP Paribas analyst uses for Chinese consumers chasing new brands the way craft-beer drinkers chase new labels. It makes market dominance fragile, because the brand everyone owns loses its status appeal.
Which brands are winning China’s fitness boom right now? Amer Sports (Arc’teryx, Salomon) grew about 45% last quarter, On exceeded its 44% Asia-Pacific rate, and Lululemon grew 30%. Local brands Anta, Li-Ning, and Xtep are also gaining fast on price and fit.
Why does athletic apparel grow when China’s economy is soft? Post-pandemic, wellness became a status symbol, and premium gear became the way to signal it. Fitness is one of the few categories rising while cars and traditional luxury slump.
The Business Model Analyst Take
The Wall Street Journal framed this as a boom with clear winners. We read it as a boom that commoditizes its winners on a timer. The forces driving China’s fitness spending, novelty-seeking and status signaling, are the same forces that will strip pricing power from any brand that becomes the default. Nike already lived that cycle. It went from untouchable to down 29% while doing little wrong on product, undone mostly by becoming ordinary.
Lululemon is betting it can stay novel in the one market where novelty decays fastest, and it is making that bet with its home market shrinking behind it. The bet is not unreasonable. Its China base is still small, its brand still fresh, its growth still real. But the margin for error is thin, the political risk is live after the Great Wall stumble, and the competitive set is filling with exactly the fresher names that pull Chinese consumers along. Winning China is not the achievement. Staying won is. That is the harder business, and it is the one that will decide whether Lululemon’s growth story survives past the next fashionable brand to post “Hello China.”