
Ask Americans what the dream looks like and the answer barely moves: a house with your name on the deed. In the Coldwell Banker 2025 American Dream Report, 85% still call homeownership part of the dream, and 56% say it personally represents the dream to them, ranking it above marriage and children (42%), a successful career or business (39%), and a college degree (23%).
Here is the problem. What Americans pursue and what actually builds wealth are close to opposite rankings. The path the most people chase has the lowest wealth ceiling of the three. The path the fewest people take, starting a business, is the only one with no ceiling at all and the only one the Federal Reserve links to a doubling of net worth.
This is a ranking of the three modern versions of the dream, scored as what they really are: wealth-building engines. We rate FIRE, homeownership, and business ownership on six fixed axes, then show why the honest answer is not “pick one.”
The three paths, defined
Homeownership. Buy a primary residence, pay down the mortgage, and let equity plus appreciation build your net worth over decades. The default dream, and the most leveraged bet most households will ever make.
FIRE (Financial Independence, Retire Early). Save an aggressive share of your income, invest it in low-cost index funds, and stop working once your portfolio hits roughly 25 times your annual spending. The 4% rule, the movement’s core math, says a nest egg of 25x expenses can fund withdrawals for 30-plus years. If you spend $60,000 a year, your number is $1.5 million.
Your own business. Build an asset that generates income and, eventually, sale value. The highest-variance path: most attempts fail, but the survivors capture returns neither of the other two can reach.
The scorecard: how the three actually compare
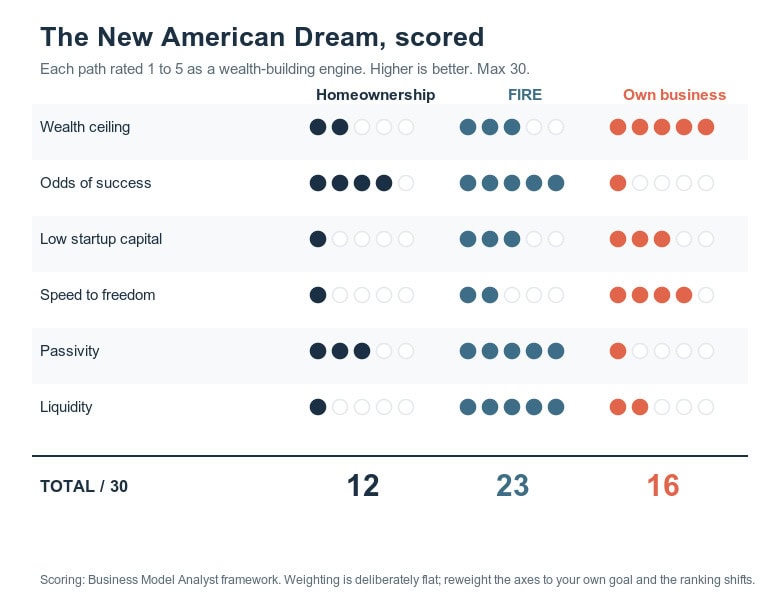
We scored each path 1 to 5 on the axes that decide whether a wealth engine is worth running. Higher is better.
| Axis | Homeownership | FIRE | Own business |
|---|---|---|---|
| Wealth ceiling | 2 | 3 | 5 |
| Odds of success | 4 | 5 | 1 |
| Low startup capital | 1 | 3 | 3 |
| Speed to freedom | 1 | 2 | 4 |
| Passivity | 3 | 5 | 1 |
| Liquidity | 1 | 5 | 2 |
| Total (of 30) | 12 | 23 | 16 |
On a flat, unweighted score, boring wins. FIRE takes it at 23, because index investing is the closest thing to a sure thing over a long horizon, it runs itself once funded, and you can sell a slice on any Tuesday. Business ownership lands second at 16: the only uncapped ceiling, but brutal odds and zero passivity drag the total down. Homeownership, the thing 85% call the dream, finishes last at 12 as a pure wealth engine.
One honest caveat, because the ranking is only as good as its weighting. These axes are weighted equally, and no one lives that way. Weight “wealth ceiling” heavily because you want to get rich rather than merely free, and business jumps to the front. Weight “a stable place to live” and homeownership’s real value, which a pure wealth-engine score undercounts, reappears. The scorecard is a thinking tool, not a verdict.
Path 1: Homeownership, the popular dream with the weak engine
Homeownership does two things well and one thing poorly, and the confusion between them is why it tops the dream survey while finishing last on the scorecard.
What it does well: forced savings and stability. A mortgage is a savings plan you cannot easily skip, and a fixed payment is an inflation hedge on your largest monthly cost. Americans feel this. In the same survey, 65% say buying beats renting long term and 48% believe real estate builds wealth better than stocks.
What it does poorly: build maximum wealth. A primary residence is a single, illiquid, highly leveraged asset that you also have to live inside, so you can never fully cash the gains without buying back into the same market. Long-run real home price appreciation has historically trailed the stock market by a wide margin. Leverage cuts both ways, transaction costs run 8 to 10% round trip, and property taxes and maintenance never stop.
Then there is the entry cost. The U.S. median home price has risen 30% since 2020 to $410,800, and a 20% down payment now roughly equals the entire median household income of $83,730. That is why 71% of aspiring buyers report delaying major life decisions to save for a home, and just over half do not expect to buy until age 40 or later. Homeownership scores a 1 on startup capital and a 1 on speed for a reason: it is the slowest engine to start and the slowest to pay off.
Verdict: an excellent stability and forced-savings vehicle. A mediocre wealth-maximizing one. Great as a foundation, weak as a strategy.
Path 2: FIRE, the reliable machine with a ceiling
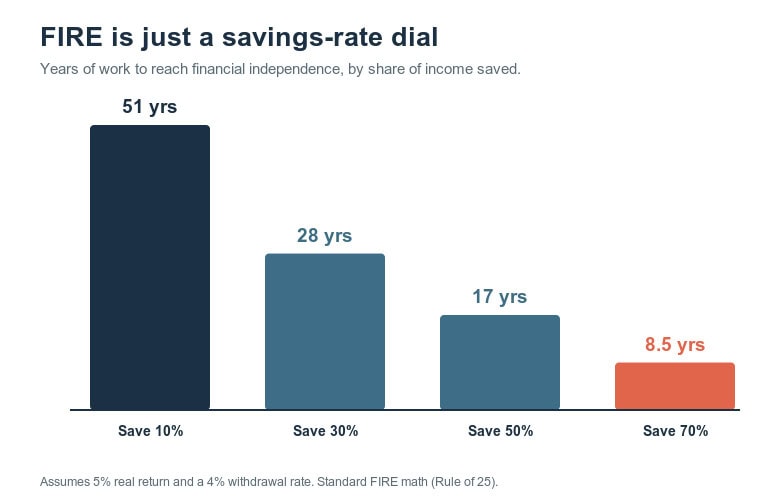
FIRE is the highest-scoring path because it removes almost every variable except one you control: your savings rate. Everything else is arithmetic.
The relationship is stark. Save 10% of your income and financial independence sits roughly 51 years away. Save 30% and it drops to about 28 years. Save 50% and you are looking at roughly 17 years. Push to 70% and you can reach it in under a decade. (Standard FIRE math, assuming a 5% real return and a 4% withdrawal rate.) No luck, no market timing, no product-market fit. Just a dial.
That reliability is the whole pitch. Broad-market index investing has the best base rate of any path here, which is why FIRE scores a 5 on odds and a 5 on passivity and liquidity. The catch is the ceiling. FIRE is capped by your savings rate times market returns, so it delivers freedom, not a fortune. It is also gated by income: a 50% savings rate is trivial to admire and hard to hit on a median wage, which is why FIRE in practice skews toward high earners.
Two real risks the movement understates. Sequence-of-returns risk, a bad crash right as you retire, can gut a portfolio that looked fine on paper, which is why many practitioners use a more conservative 3.25 to 3.5% withdrawal rate. And healthcare: one estimate puts a 35-year-old retiring at 50 on the hook for roughly $380,000 in health costs before Medicare kicks in at 65.
For the deeper question of exactly how large your number needs to be, and why “living off investments” starts further into seven figures than most people think, see our breakdown of how much you need to live off dividends. FIRE is also the destination most passive income strategies are quietly aiming at, whether their sellers admit it or not.
Verdict: the safest path to freedom. Not the path to wealth. If your goal is to stop trading time for money with high confidence, nothing here beats it.
Path 3: Your own business, the asymmetric bet
This is the path with the worst odds and the best payoff, and the data on both is cleaner than the myths suggest.
Start with the risk, because it is real. Per the U.S. Bureau of Labor Statistics, about 20% of new businesses fail in year one, roughly half are gone by year five, and about 65% close within ten years. The often-repeated “90% fail in year one” line is false, but the ten-year reality is sobering enough: only about one business in three is still standing after a decade. That earns business ownership a 1 on odds of success.
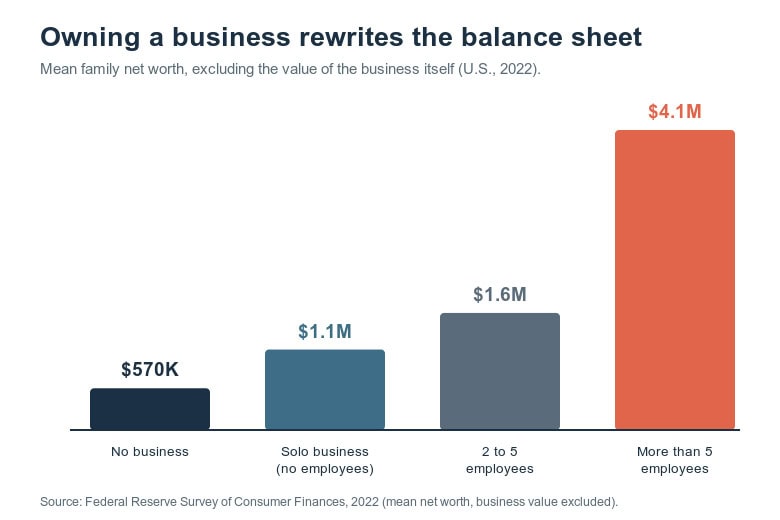
Now the payoff, and this is the number competitors skip. The Federal Reserve’s Survey of Consumer Finances shows that families with no business had a mean net worth around $570,000, while families owning a solo business with no employees averaged nearly $1.1 million, before counting the value of the business itself. Add employees and it compounds: 2 to 5 employees pushes mean net worth to about $1.6 million, and more than 5 employees to about $4.1 million. Business ownership does not just add to the balance sheet. It rewrites it.
That is the case for the 5 on wealth ceiling and the 4 on speed. A business is the only path here that can hit escape velocity in a few years rather than a few decades, because it is not capped by a savings rate or a single property. It is also the only one that produces an asset you can sell for a multiple of its earnings. The cost is everything the other paths score well on: passivity (1) and liquidity (2). A business is not a stream that runs itself. It is a job you own, right up until it is an asset you sell.
Verdict: the only path with a real shot at generational wealth, and the only one that can wipe you out. High ceiling, high floor to clear. If you understand how a business model actually creates and captures value, your odds improve; the 65% failure rate is not evenly distributed.
The insight most people miss: the dream is inverted
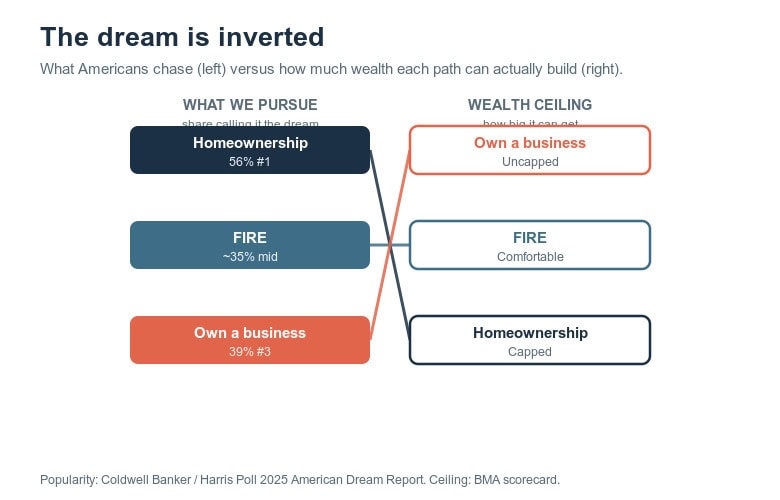
Line up what Americans pursue against what builds wealth and the two rankings run backwards.
Homeownership ranks first in desire and last in wealth ceiling. Business ownership ranks last in desire (only 39% even list it as part of the dream) and first in ceiling, with the Fed data to back it. FIRE sits in the middle of both, the quiet compromise almost no one puts on a vision board.
The reason is not that people are irrational. It is that the three paths optimize for different things and get scored as if they were interchangeable. Homeownership optimizes for stability and belonging. FIRE optimizes for freedom and certainty. A business optimizes for upside. Ask “which is the American dream” and stability wins the vote. Ask “which builds the most wealth” and upside wins the math. Both answers are correct. They are just answers to different questions.
There is a second, more useful truth hiding underneath: these paths are not mutually exclusive, and treating them as a three-way choice is the actual mistake. The strongest financial lives stack all three. A business throws off the surplus income that makes an aggressive FIRE savings rate possible. That portfolio, plus a business sale, funds the home purchase in cash and the early retirement at the same time. The people who look like they “won” rarely picked one lane. They used the business as the engine, index investing as the ballast, and the house as the reward.
So the honest ranking is conditional. If you want the highest expected wealth and can stomach the failure rate, business ranks first. If you want freedom with the least risk, FIRE ranks first. If you want a stable base and a place to raise a family, buy the house, but know you are buying stability, not maximum return, and do not mistake it for your whole financial plan.
FAQ
What is the safest of the three paths? FIRE, built on broad-market index investing, has the best base rate. It scores highest on odds of success, passivity, and liquidity. The main risks are a market crash near your retirement date and healthcare costs before Medicare eligibility.
Which path builds the most wealth? Business ownership has by far the highest ceiling. Federal Reserve data ties business ownership to roughly double the net worth of non-owners, and far more for businesses with employees. The trade-off is that about 65% of businesses close within ten years.
Is buying a home still worth it? As a place to live and a forced-savings plan, yes. As a pure wealth-building engine, it is the weakest of the three, because a primary residence is illiquid, heavily leveraged, and something you have to keep living in. Treat it as a foundation, not a strategy.
Do I have to choose just one? No, and that is the core point. The three stack: a business generates the income, FIRE-style investing compounds the surplus, and a home converts some of that into stability. The three-way “choice” framing is the mistake.
How much do I need to retire early? The rule of thumb is 25 times your annual expenses. For the detailed version, including why the real threshold sits further into seven figures than most people expect, see our guide on how much you need to live off dividends.
The Business Model Analyst Take
The “new American dream” framing sells a false choice. FIRE, homeownership, and a business are not three doors where you walk through one. They are three tools, and they do different jobs.
If we have to rank them as pure wealth engines, the scorecard is clear and a little uncomfortable: FIRE first for reliability, business second for raw ceiling, homeownership last. But that ranking inverts the one Americans actually live by, where the house comes first and the business comes last. That gap is the whole story. The most popular dream is the weakest wealth engine, and the least popular one is the strongest.
The operators who compound fastest treat this like a portfolio, not a personality test. Use the business as the engine, because it is the only thing here that can outrun a salary. Use index investing as the ballast, because it is the only thing that reliably keeps compounding while you sleep. Buy the house when it buys you stability, not because a survey told you it was the finish line. The dream was never one path. It was knowing which tool does which job.