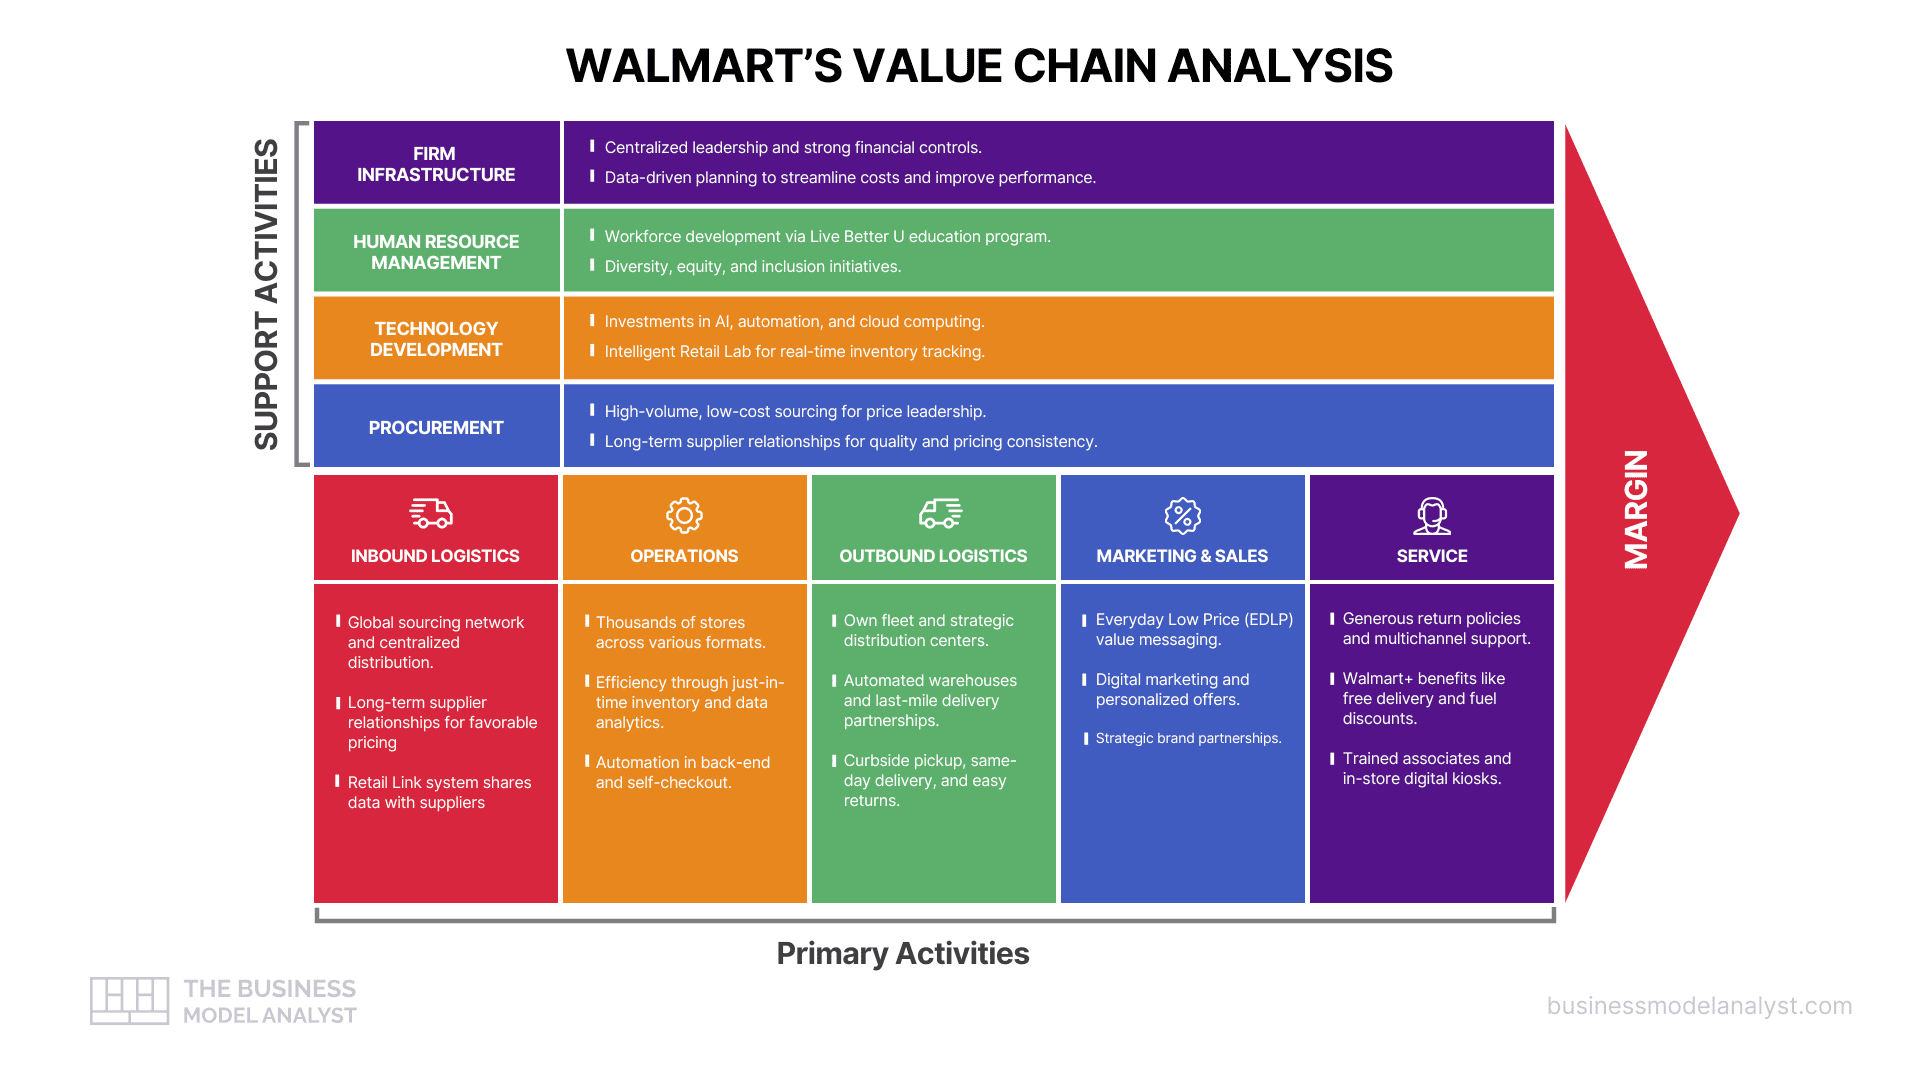
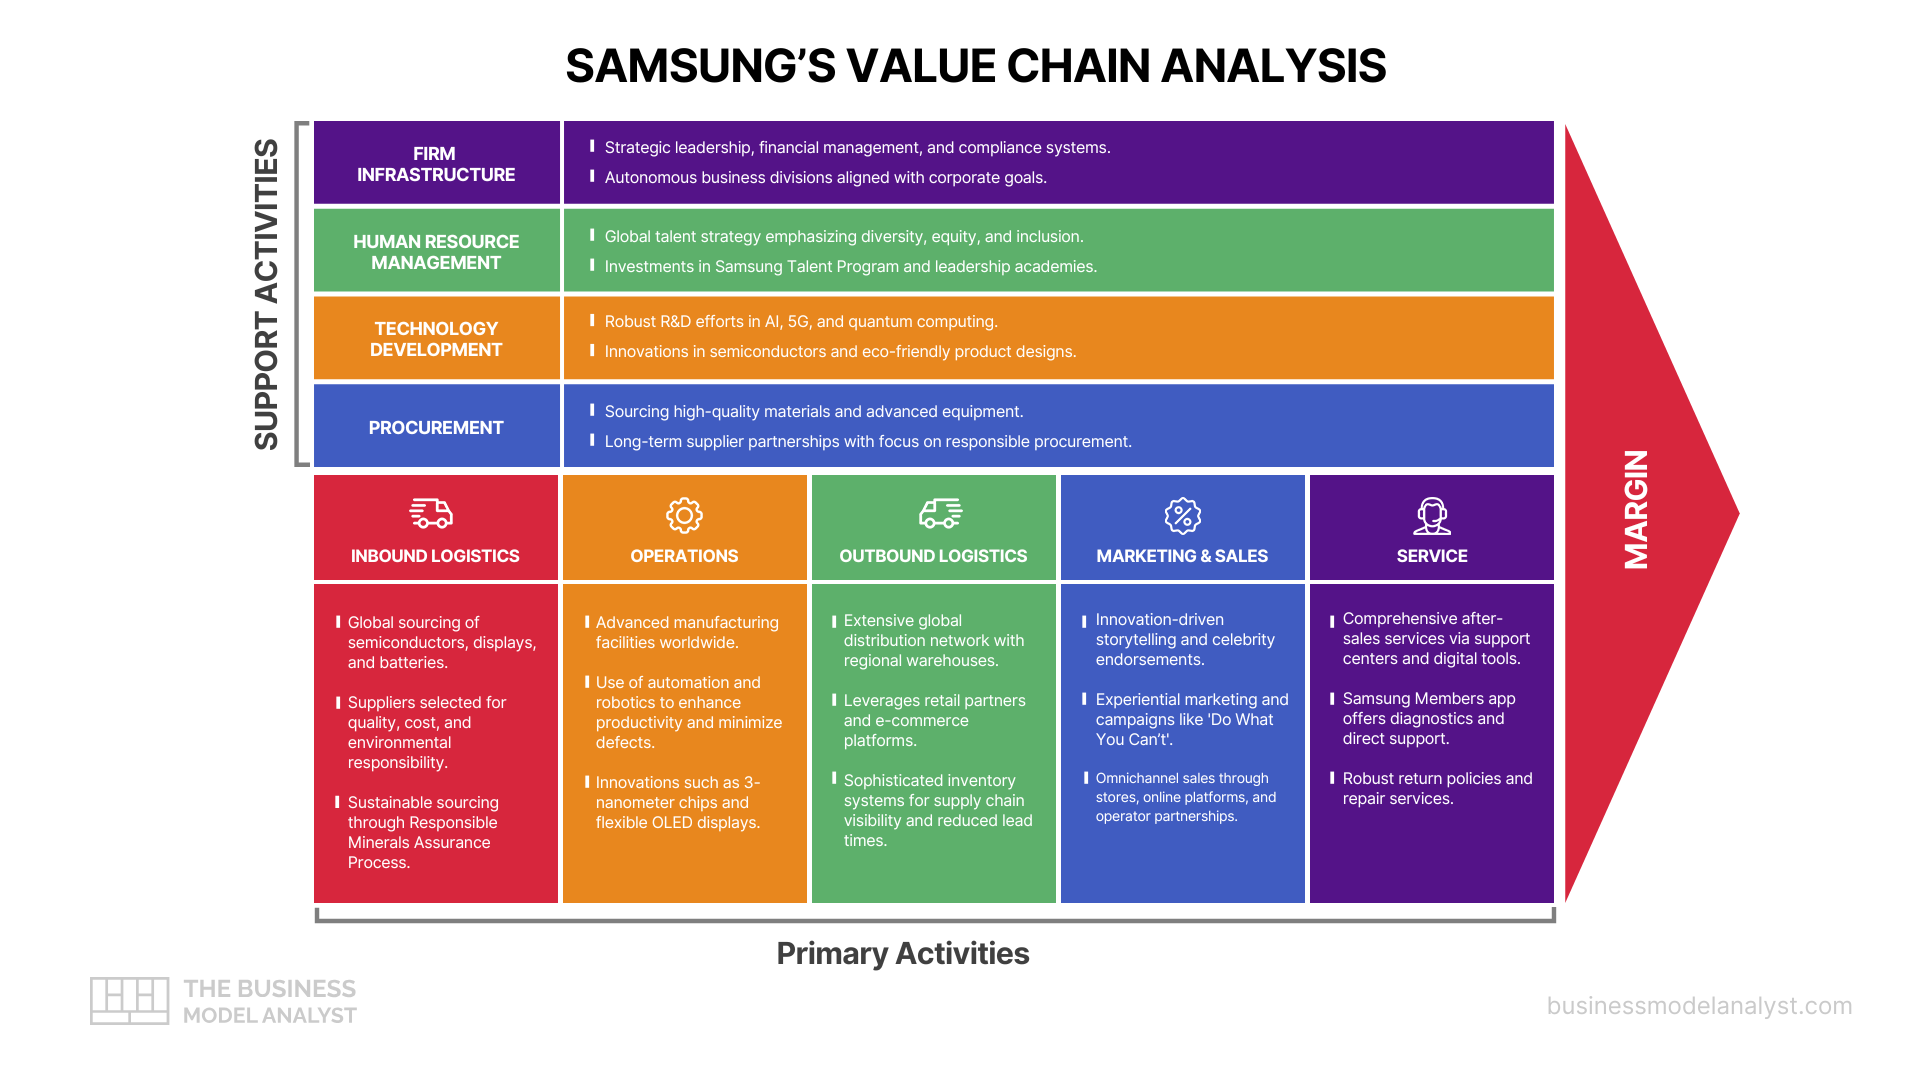
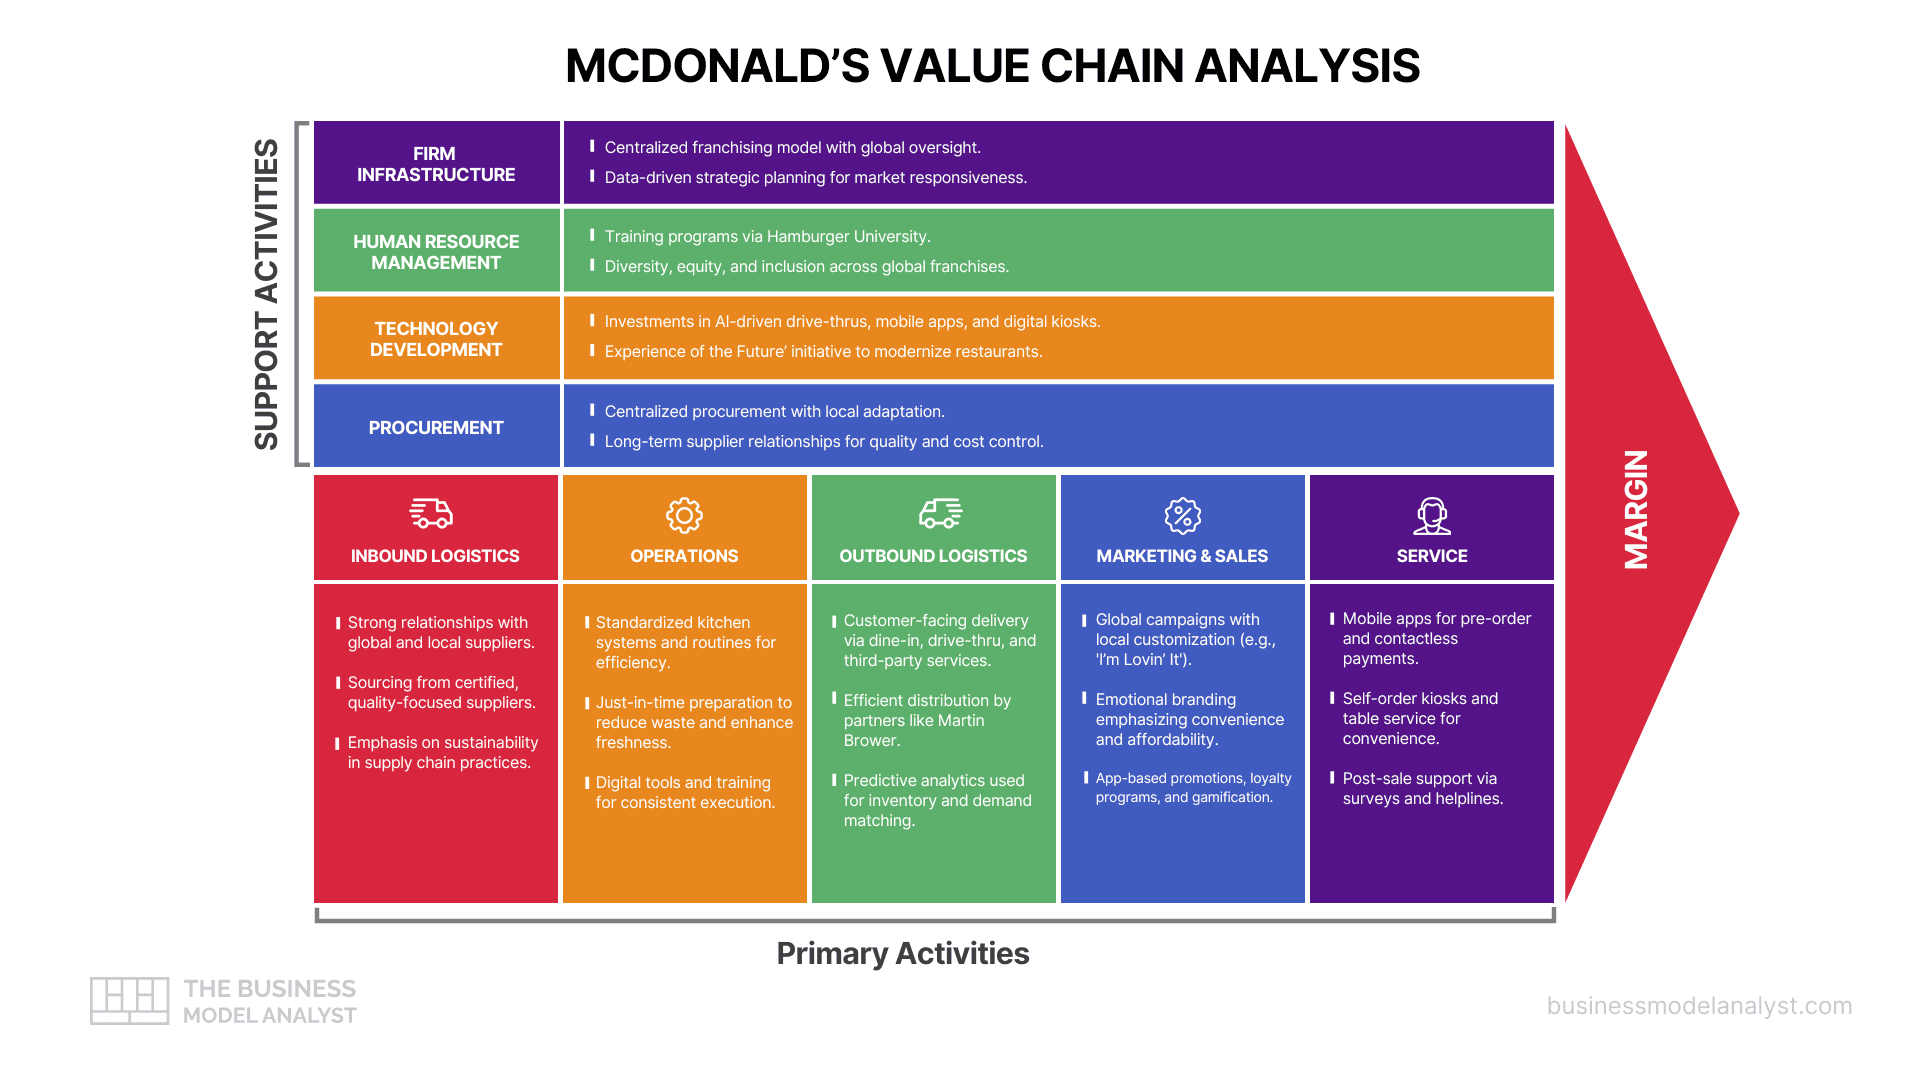
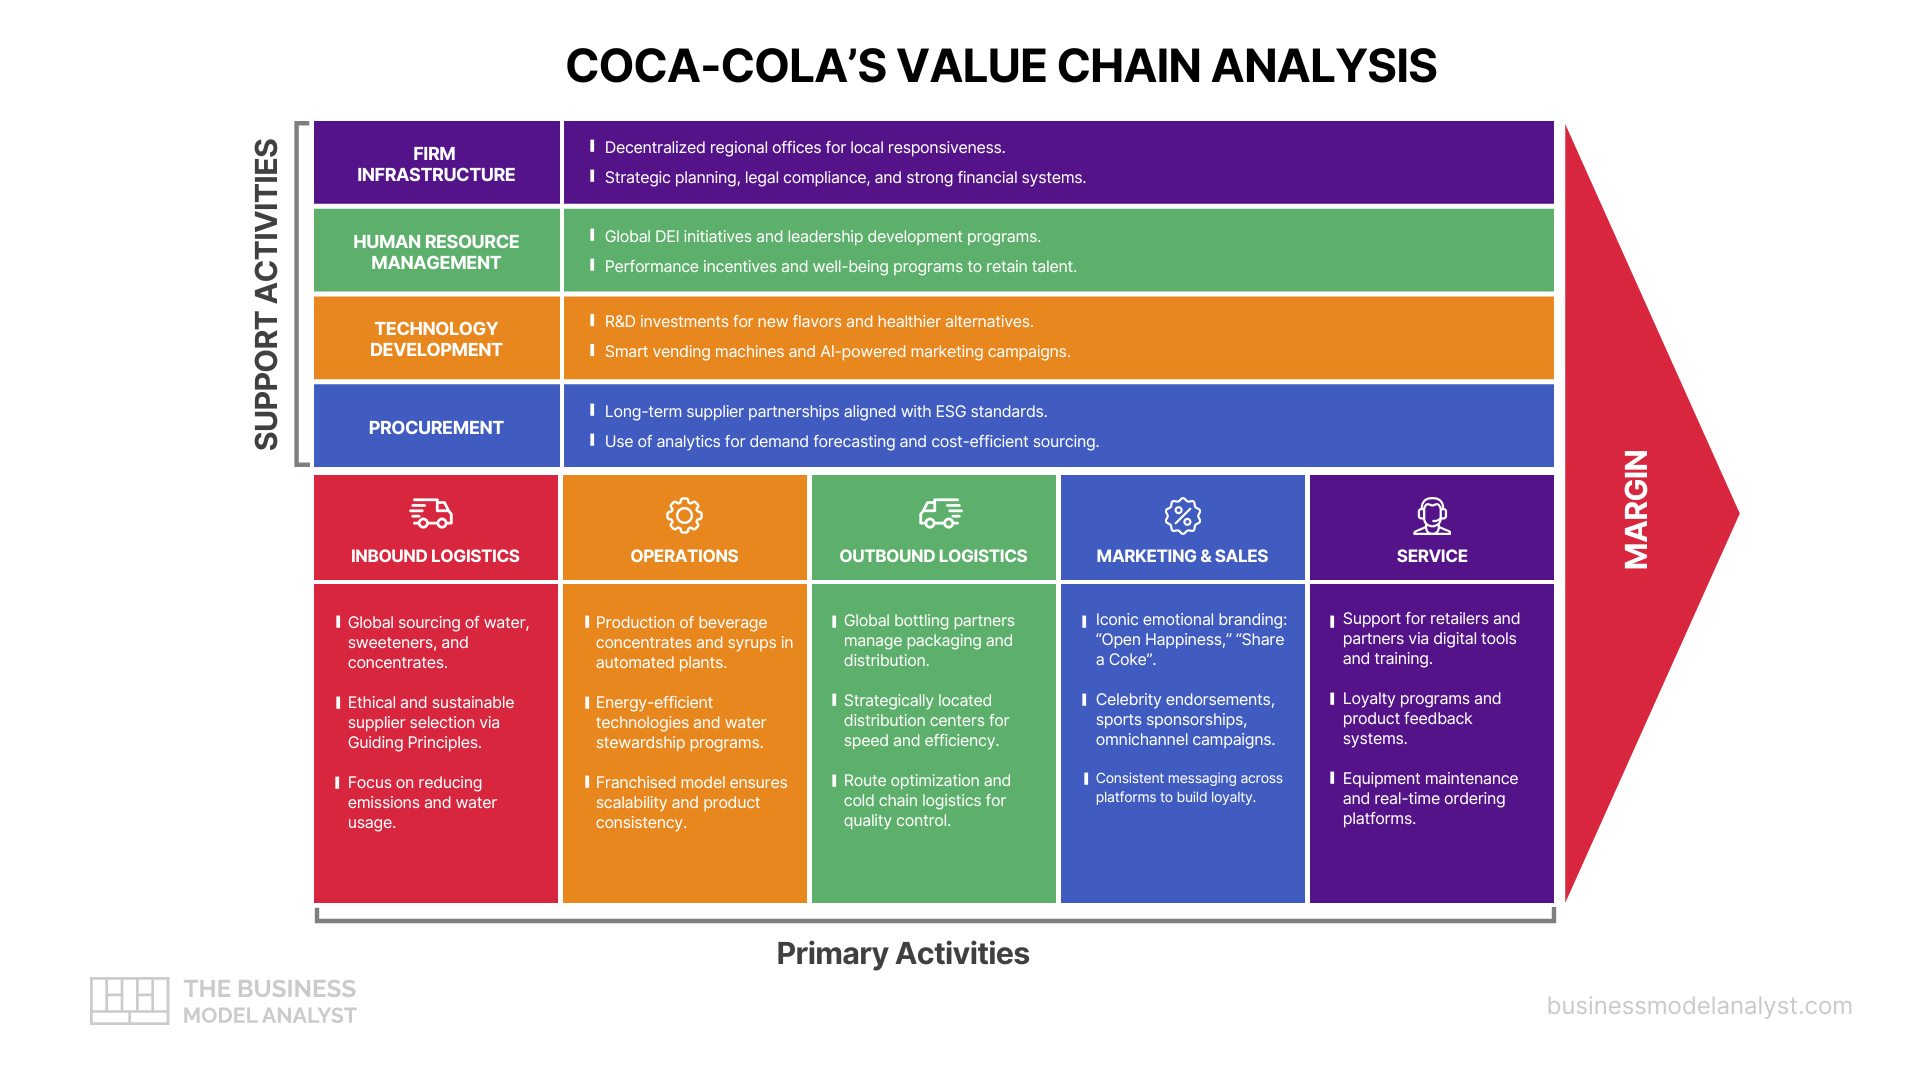
Value chain analysis, the framework Michael Porter introduced in 1985, breaks a company into the activities that actually create value and asks a simple question of each one: does this build a cost advantage, a differentiation advantage, or neither? For Netflix, the answer is unusually clear. The company turned content, code, and customer data into a streaming machine that generated $45.18 billion in revenue and a 29.5% operating margin in 2025, numbers a traditional media business would not recognize.
This Netflix value chain analysis maps every primary and support activity to the specific mechanism behind that profitability, using current financials rather than the decade-old figures most write-ups still recycle.
Definition Box: Netflix Value Chain Analysis
| What it is | A breakdown of Netflix’s business into Porter’s nine activities (five primary, four support) to show where the company creates value and competitive advantage. |
| Primary activities | Inbound logistics (content acquisition), operations (production and streaming), outbound logistics (delivery via Open Connect), marketing and sales, and service. |
| Support activities | Firm infrastructure, human resource management, technology development, and procurement. |
| The core insight | Netflix’s advantage is not any single activity. It is the loop between viewer data, content decisions, and its own delivery network, which together lower costs and raise engagement at the same time. |
| Key 2025 proof point | $45.18B revenue, 29.5% operating margin, ~325 million paid memberships, and an ad tier that crossed 190 million monthly active viewers, all running on infrastructure Netflix largely owns. |
Overview of Netflix
Reed Hastings and Marc Randolph founded Netflix in 1997 as a DVD-rental-by-mail service. The pivot that mattered came in 2007, when streaming launched, and again in 2013, when House of Cards made Netflix a studio rather than a distributor. Each shift rewrote the value chain underneath it. The Netflix business model is now a subscription-based streaming operation layered with advertising, live events, and games.
Three numbers frame the modern company:
| Milestone | Detail | Year |
|---|---|---|
| Streaming launch | First digital platform, still DVD-led | 2007 |
| First original | House of Cards greenlit on viewing data | 2013 |
| Paid memberships | ~325 million globally, up from 301.6M | End 2025 |
| Stopped reporting subscriber counts | Shifted investor focus to revenue and engagement | Q1 2025 |
| Pending acquisition | Warner Bros. Discovery, $82.7B deal | Announced 2026 |
That last row matters for the value chain. Netflix stopped disclosing quarterly subscriber totals starting in Q1 2025, a deliberate move to make revenue per member, not raw growth, the story. It signals a company whose value chain has matured from land-grab to margin extraction.
The Netflix Value Chain at a Glance
Before the detailed walk-through, here is the whole chain in one view, each activity tied to the advantage it produces and the evidence behind it.
| Activity | What Netflix does | Advantage created | 2024 to 2026 evidence |
|---|---|---|---|
| Inbound logistics | Licenses third-party titles and commissions originals | Differentiation through exclusive content | $18B content spend, 597 new originals in 2025 |
| Operations | Produces content and runs the streaming platform | Cost control and reliability at scale | Compute on AWS, video on owned CDN |
| Outbound logistics | Delivers video via Open Connect | Near-zero marginal delivery cost | ~95% of traffic served from Netflix-controlled appliances |
| Marketing and sales | Data-led, content-led acquisition and retention | Lower acquisition cost per member | Marketing held near $2.5B while revenue passed $45B |
| Service | Self-service support, parental controls, personalization | Low churn, low support cost | Recommendations estimated to save $1B+ a year |
| Firm infrastructure | Decentralized governance, “freedom and responsibility” | Speed of decision-making | Co-CEO structure, lean corporate layer |
| HR management | Selective hiring, top-of-market pay | High output per employee | Famously small headcount relative to revenue |
| Technology development | AI, recommendation systems, encoding | A moat rivals cannot easily copy | First-party data powers both content and ads |
| Procurement | Content rights, cloud, creative talent | Cost discipline on the largest line item | Budget-first film strategy under Dan Lin |
The rest of this analysis explains each row and the numbers behind it.
Primary Activities in the Netflix Value Chain
Inbound Logistics: Content as Raw Material
For a streamer, content is the raw material, and Netflix sources it two ways: licensing existing titles and producing its own. The strategic weight has shifted hard toward originals, because owned content cannot be pulled by a rival the way licensed catalog can.
The scale is the story competitors miss. Netflix spent roughly $18 billion on content in 2025 and released 597 new originals, a slate no traditional studio approaches. Crucially, Netflix treats that spend as a capitalized asset, not a simple expense. Its content amortization climbed from $4.8 billion in 2016 to $14.2 billion by 2023, nearly tripling, while operating margins rose at the same time. That accounting choice (spreading content cost over the years a title earns) is part of why a business spending $18 billion on programming still prints a near-30% margin.
| Content source | Role in the value chain | Strategic trade-off |
|---|---|---|
| Licensed titles | Fills the catalog cheaply, drives reach | Can be lost to competitors at renewal |
| Original series and films | Exclusive, owned, drives subscriptions | High upfront cost, hit-or-miss |
| Local-language originals | Wins specific regional markets | Needed for international growth |
| Live events and sports | Creates appointment viewing | New, operationally complex |
Operations: Production Plus Platform
Operations is where inputs become the service. Netflix runs two operational engines at once: a content studio and a software platform. On the technology side, Netflix migrated nearly all of its compute to Amazon Web Services years ago, but it does not stream video from AWS. Video delivery runs on Netflix’s own network (covered next). That split, cloud for computing and an owned CDN for delivery, is a deliberate operational design that keeps the most cost-sensitive function in-house.
The film operation has tightened noticeably. Under film chairman Dan Lin, hired in 2024, Netflix swapped blank-check deals for budget discipline, a shift our coverage of Netflix’s fewer-better-films strategy breaks down in detail. That is value chain optimization in real time: same activity, lower cost per output.
Outbound Logistics: Open Connect Is the Hidden Advantage
This is the section nearly every competing article gets wrong or skips. They call Netflix’s outbound logistics “minimal because it is digital.” The opposite is true. Netflix built one of the largest private content delivery networks on earth, and it is a genuine source of cost advantage.
Open Connect, launched in 2012, places Netflix-owned storage appliances directly inside internet service provider networks, free of charge to the ISP. The numbers, drawn from Netflix and public technical documentation:
| Open Connect metric | Figure |
|---|---|
| Launch year | 2012 |
| Appliances deployed | More than 8,000 globally |
| Invested in the network | Over $1 billion |
| ISP partners | More than 1,000 |
| Share of Netflix traffic served directly | Roughly 95% |
| Storage per appliance | Up to ~350 TB |
The economic logic is elegant. Netflix ships a copy of a title to a local appliance once, usually overnight when networks are idle. Every subsequent stream is served locally, so the title only crosses the expensive long-haul network a single time no matter how many people watch it. One independent analysis estimated Open Connect saved ISPs over $1 billion globally in 2021 alone. Netflix captures the other side of that benefit: near-zero marginal delivery cost as it scales toward a billion viewers.
Marketing and Sales: Spend Less, Earn More
Netflix’s marketing is data-led and content-led, which is a polite way of saying the content does much of the selling. The signal is in the ratio. Netflix’s marketing expense has stayed roughly flat near $2.5 billion for years while revenue grew past $45 billion, which means marketing as a share of revenue has roughly halved. That is operating leverage, and it is exactly what a mature value chain should produce.
The newer engines do the heavy lifting now. The ad tier and live events both feed acquisition and retention, themes our Netflix marketing strategy breakdown and Netflix target market analysis cover in depth.
| Marketing lever | How it creates value |
|---|---|
| Personalized in-app discovery | Keeps members watching, cuts churn |
| Original-release buzz | Earned media replaces paid spend |
| Live events (boxing, NFL, WWE) | Spikes sign-ups, gives advertisers premium moments |
| Ad tier targeting | Monetizes price-sensitive viewers, adds a second revenue stream |
Service: Retention as a Cost Center That Pays Back
Service at Netflix is built to be cheap and self-directed. Self-service help, easy cancellation, parental controls, and multilingual support keep the cost of serving 325 million memberships low. But the real service product is personalization. Netflix’s own research has long estimated that its recommendation and personalization system saves the company more than $1 billion per year in avoided churn. Service and technology blur here, which is the point.
Support Activities in the Netflix Value Chain
Firm Infrastructure
Netflix runs a deliberately thin corporate layer with a decentralized, high-trust governance model (its “freedom and responsibility” culture). Strategic decisions sit with co-CEOs Ted Sarandos and Greg Peters, with founder Reed Hastings as executive chairman. The structure favors speed, and our Netflix organizational structure analysis details how the hybrid functional-regional design supports global scale without bloating overhead.
Human Resource Management
Netflix is famous for paying top-of-market and hiring selectively, the trade being fewer people doing more. The result is one of the highest revenue-per-employee figures in media. The HR philosophy is itself a competitive asset: it attracts senior talent who want autonomy, and it keeps the firm infrastructure layer lean.
Technology Development
Technology underpins the entire chain, which is why it appears as a support activity but functions like a primary one. AI and machine learning power recommendations, encoding optimization (squeezing quality into less bandwidth), thumbnail testing, and now ad targeting. The strategic payoff in 2026 is that Netflix’s first-party viewing data lets advertisers target without third-party cookies, turning a content asset into an advertising asset. The Netflix value chain’s data loop (viewing behavior informs content, which generates more viewing behavior) is the moat rivals struggle to copy.
Procurement
Procurement at Netflix is dominated by one line: content rights. Securing licenses and talent at disciplined cost is the difference between a 20% and a 30% margin. The 2024 shift to budget-first film greenlighting is procurement strategy as much as creative strategy. The pending Warner Bros. Discovery acquisition, an $82.7 billion deal expected to close after WBD’s network spinoff, would be the largest procurement move in the company’s history, bringing a major content library in-house rather than licensing it.
Where Netflix’s Value Chain Creates Competitive Advantage
| Advantage | The mechanism | The evidence |
|---|---|---|
| Owned delivery network | Open Connect serves ~95% of traffic locally | Marginal delivery cost near zero at scale |
| Content as a capitalized asset | Amortization spreads cost over earning life | ~$18B spend, near-30% margin coexist |
| Data-to-content loop | Viewing data drives both greenlights and ads | First-party targeting without cookies |
| Operating leverage | Fixed-ish costs against rising revenue | Marketing flat at ~$2.5B, revenue past $45B |
| Scale in originals | 597 originals in 2025 dwarfs studio output | Exclusive library no rival can pull |
Put together, the chain does something specific: it lowers cost and raises differentiation at the same time, which Porter would call a rare position. Most companies have to pick one.
Netflix by the Numbers (2024 to 2026)
The data most competing analyses lack, in one place. Figures are from Netflix’s SEC filings and shareholder letters.
| Metric | 2024 | 2025 | 2026 (latest) |
|---|---|---|---|
| Revenue | ~$39.0B | $45.18B | $12.25B (Q1) |
| Operating margin | 27% | 29.5% | 32.3% (Q1) |
| Net income | ~$8.7B | $10.98B | n/a |
| Paid memberships | 301.6M | ~325M | not reported |
| Content spend | ~$17B | ~$18B | n/a |
| Ad-tier monthly active viewers | ~70M (year-end) | 190M (Nov) | 250M+ (May) |
| Best-ever quarterly net adds | 18.9M (Q4) | n/a | n/a |
Two data points deserve emphasis because they reframe the whole chain. First, the ad tier scaled from 94 million monthly active viewers in May 2025 to more than 190 million by November 2025, a near-doubling in six months that turned advertising from a side project into a structural revenue stream. Second, Netflix viewers streamed 96 billion hours in the second half of 2025, which is the engagement that the entire value chain exists to produce and protect.
Frequently Asked Questions
What are the primary activities in Netflix’s value chain? Inbound logistics (acquiring and producing content), operations (running the studio and the platform), outbound logistics (delivering video through Open Connect), marketing and sales, and service. Content acquisition and delivery are where Netflix creates the most value.
What is the most important part of Netflix’s value chain? The data-to-content-to-delivery loop. Viewing data informs what Netflix makes, owned content differentiates the catalog, and Open Connect delivers it at near-zero marginal cost. No single activity is the advantage; the integration is.
How does Open Connect give Netflix a cost advantage? Open Connect places Netflix-owned appliances inside ISP networks. A title is shipped to a local appliance once, then served locally to every viewer, so it crosses expensive long-haul networks only once. Roughly 95% of Netflix traffic is delivered this way, which keeps delivery cost flat as viewership grows.
How much does Netflix spend on content? Around $18 billion in 2025, across roughly 597 new originals plus licensed titles. Netflix capitalizes and amortizes this spend rather than expensing it immediately, which helps explain how it maintains a near-30% operating margin.
Why did Netflix stop reporting subscriber numbers? Starting in Q1 2025, Netflix stopped disclosing quarterly subscriber totals to shift investor focus toward revenue, operating margin, and engagement. The move reflects a value chain that has matured from chasing growth to extracting profit per member.
Who are Netflix’s main competitors? Disney+, Amazon Prime Video, Max, Apple TV+, and others. See our full breakdown of Netflix competitors and alternatives and the external pressures in the Netflix PESTLE analysis.
The Business Model Analyst Take
Most value chain analyses of Netflix describe a company that no longer exists, one with 260 million subscribers and a 2019 marketing budget. The current reality is sharper and more instructive.
Netflix’s value chain is best understood as a margin machine that got built in two phases. Phase one (2007 to roughly 2022) spent heavily to win the streaming war: originals, global expansion, and a private delivery network. Phase two, the one we are in now, is about pressing the advantages that phase one created. The ad tier, the price increases, the budget-first film strategy, and the decision to stop reporting subscriber counts are all moves you make when your value chain is mature enough to optimize rather than expand. The result is visible in the margin line, which climbed from 21% in 2023 to a record 32.3% in early 2026.
The single most underrated link in the chain is Open Connect. It is invisible to viewers, dismissed by most analysts, and quietly responsible for the fact that Netflix can scale toward a billion viewers without its delivery costs scaling alongside. The Warner Bros. Discovery acquisition, if it closes, is the next chapter: a bet that owning content outright beats licensing it, applied at the largest scale the company has ever attempted. Watch the margin. It tells you whether the value chain is still working.
This analysis draws on Netflix’s SEC filings and shareholder letters, Netflix Open Connect technical documentation, and independent reporting. Financial figures reflect the most recent disclosures available.