
The new $5.6 billion venture, Peranel, lets Nestlé pocket cash and hand a regulatory-clouded water business to private equity while keeping half the upside.
Nestlé is selling 50% of its waters and premium beverages business to Platinum Equity in a joint venture called Peranel, valued at 4.9 billion euros ($5.6 billion). Nestlé banks roughly 3 billion euros ($3.4 billion) in cash, keeps a 50% stake, and offloads day-to-day control of Perrier’s legal baggage.
The headline reads like a growth cull. The numbers say something more interesting: Nestlé just sold its second-fastest-growing category. This is not a business in trouble. It is a business Nestlé no longer wants on its own balance sheet, and the structure of the deal tells you exactly why.
What Happened
On July 23, 2026, alongside its first-half results, Nestlé announced a 50/50 joint venture with US private-equity firm Platinum Equity, run by billionaire Tom Gores. The new company, Peranel, will house more than 30 brands sold in 120 countries, including S.Pellegrino, Source Perrier, Acqua Panna, and the global Nestlé Pure Life brand.
Peranel carries an enterprise value of 4.9 billion euros. Nestlé collects about 3 billion euros in cash, holds onto 50% of the equity, and hands operational control to a partner that specializes in corporate carve-outs. The business will be headquartered in Paris and led by Muriel Lienau, the current head of Nestlé’s waters unit. Nestlé expects the deal to close in the first half of 2027.
The market reaction was ugly, but not because of this deal. Nestlé shares fell close to 7% on the day, driven by the earnings report the JV was announced beside. First-half net profit dropped 31.4% to 3.5 billion Swiss francs, dragged down by restructuring costs and write-downs tied to disposals.
The Backstory
Nestlé is a company in the middle of a hard reset. CEO Philipp Navratil took the top job in September 2025 after his predecessor, Laurent Freixe, was dismissed over an undisclosed relationship with a subordinate, and the chairman stepped down soon after. Navratil inherited a portfolio that investors had spent years calling bloated and a share price that had gone nowhere.
His answer has been to cut. Nestlé is eliminating around 16,000 jobs, running a cost program that has already delivered 1.7 billion francs in savings toward a 2 billion franc target, and reorganizing around four core categories: Coffee, Petcare, Nutrition, and Food & Snacks. Water is not on that list.
Then there is Perrier itself. Since 2024, Nestlé Waters has been trapped in what French media dubbed “Watergate.” The company admitted using banned filtration and ultraviolet treatments on water that law requires to be sold untreated as “natural mineral water,” paid a 2 million euro fine to avoid prosecution, and watched a French Senate inquiry conclude in May 2025 that the government had covered up the practice for years. French fraud authorities have pegged the scale of the alleged fraud at over 3 billion euros. A court threw out a consumer group’s suspension bid in late 2025, but the reputational cloud over the brand never lifted.
The Plan
Nestlé’s stated logic is focus. A standalone water company, the argument goes, can invest and move faster than a division buried inside a food-and-beverage giant. Platinum Equity brings three decades of carve-out experience and roughly $48 billion in assets under management, plus a track record of standing up independent companies from businesses shed by Ball, Caterpillar, Danone, and others.
But the real plan is financial engineering, and it is a repeat. In February 2026, Nestlé pushed its remaining ice-cream business into the Froneri joint venture while keeping a 50% stake. It is now shopping mainstream vitamin brands, including Nature’s Bounty, expecting to book a 1.3 billion franc loss while retaining premium names like Solgar and Garden of Life. Peranel is the same move a third time: deconsolidate the revenue, bank the cash, keep the optionality.
The Business Model Angle
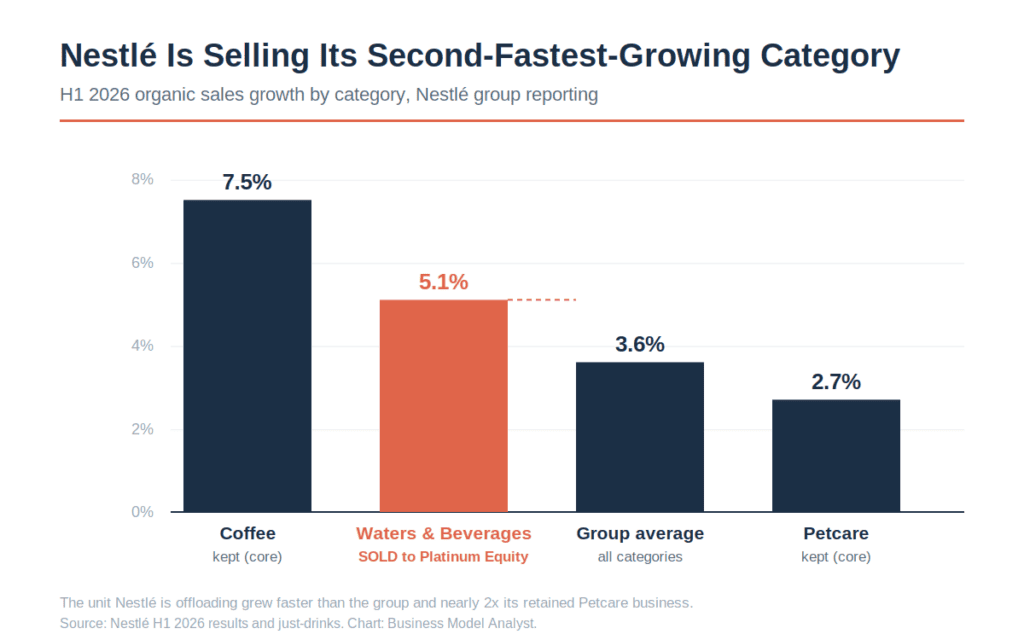
Here is the part the press release will not say out loud. Nestlé is not selling water because water is slow. In the first half of 2026, the waters and premium beverages unit grew organic sales 5.1%. That beat the group’s 3.6% and nearly doubled Petcare’s 2.7%, a category Nestlé is keeping as core. Only Coffee, at 7.5%, grew faster.
So why sell a growing business? Three reasons that have nothing to do with the top line.
| Factor | Why it pushes water off the balance sheet |
|---|---|
| Capital intensity | Bottling, sourcing, and logistics tie up assets and depress return on capital versus asset-light categories |
| Regulatory liability | The Perrier “natural mineral water” fight is an ongoing legal and reputational drain best owned by someone else |
| Strategic fit | Nestlé’s moats are in coffee and pet care, where brand pricing power and repeat purchase compound; water is a commodity with premium veneer |
The carve-out JV is the elegant part. Nestlé monetizes roughly 3 billion euros of a 4.9 billion euro enterprise value in cash today, moves the low-return, high-liability revenue off its consolidated books (which flatters group margins and return metrics), and still owns half the equity if Platinum Equity’s operators turn it into something bigger. It is an exit that is not an exit. You sell the problem, keep the option, and let a specialist absorb the turnaround risk.
This is the same instinct behind Nestlé’s crown jewels. The company guards the razor-and-blade economics of Nespresso and the sticky demand of Purina precisely because those models throw off cash without the capital drag. Water never did. For a fuller picture of where these categories sit inside the group, our Nestlé organizational structure analysis maps the divisions now being pulled apart.
The Risk
The obvious risk is that Nestlé sold cheap. A 4.9 billion euro enterprise value on a unit doing roughly 3.6 billion francs in annualized revenue is close to one times sales, a modest multiple for iconic global brands growing above 5%. If Platinum Equity cleans up the Perrier regulatory mess and repositions the portfolio, Nestlé’s retained 50% could look like the smart half of the trade, or it could look like it handed a turnaround specialist a bargain and kept the risk of being a minority partner with no control.
The second risk is signaling. Nestlé is now the company that keeps selling halves of itself. Froneri, Peranel, and the vitamins carve-out in the space of months tell investors the portfolio is being dismantled faster than it is being rebuilt. That can read as discipline or as a management team with no organic growth engine left except coffee. The 31% profit drop and near-7% share slide suggest the market has not decided which story it believes.
For a full view of the pressures shaping these moves, see our Nestlé SWOT analysis.
Quick Questions
How much is Nestlé getting for its water business? Nestlé is receiving about 3 billion euros ($3.4 billion) in cash for a 50% stake. The whole venture, Peranel, is valued at 4.9 billion euros ($5.6 billion) including cash and debt.
Who is buying it? Platinum Equity, a US private-equity firm run by billionaire Tom Gores with roughly $48 billion in assets under management. It is a 50/50 joint venture, not a full sale, so Nestlé keeps half.
What brands are in Peranel? More than 30 brands across 120 countries, including S.Pellegrino, Source Perrier, Acqua Panna, and Nestlé Pure Life.
Why is Nestlé selling if the water unit is growing? Because the reasons are capital intensity, the ongoing Perrier regulatory scandal in France, and strategic focus on four core categories, not slow growth. The unit actually grew faster than Nestlé’s group average in the first half of 2026.
When does the deal close? Nestlé expects it to complete in the first half of 2027.
The Business Model Analyst Take
Ignore the “focus on growth” framing. Nestlé sold a category that was outgrowing most of what it kept. The tell is in the structure, not the strategy slide. A 50/50 carve-out JV is what you build when you want the cash and the deconsolidated margins now but are not confident enough to walk away entirely, and when the asset carries baggage you would rather someone else carry.
That makes Peranel a clean case study in modern conglomerate management: the point is no longer to own great businesses, it is to own great returns on capital. Water is a good business with mediocre returns and a live legal problem. Coffee and pet care are good businesses with excellent returns. Nestlé is not shrinking. It is re-sorting its portfolio by return profile and using private equity as the disposal mechanism that lets it keep a foot in the door. Watch whether the retained 50% ever gets bought back at a higher price. If it does, this was a masterstroke. If Platinum Equity flips it to someone else in three years, Nestlé will have sold the bubbles and kept the bill.
Based on reporting from The Wall Street Journal, Reuters, just-drinks, and Nestlé’s H1 2026 results.