Microsoft just delivered a quarter that looks, on the surface, like a clean sweep. Profit up 31%. Azure past $100 billion for the first time. And, as a bonus for nervous investors, a capital-expenditure forecast that suddenly dropped by roughly $15 billion. The stock popped after hours.
Two of those three headlines are performance. One is presentation. Telling them apart is the whole game, and it says more about where the AI buildout stands than the $100 billion milestone everyone is celebrating.
What Happened
For the quarter that ended in June, Microsoft reported revenue of $90 billion, up 18%, and net income of $35.8 billion, up 31%. Both beat Wall Street. CEO Satya Nadella disclosed for the first time that Azure crossed $100 billion in annual revenue in fiscal 2026, a number Microsoft historically buries inside its broader cloud segment. Azure grew 43% in the quarter, up from 40%, with the company guiding to 45% next quarter. Copilot hit 30 million paid seats, up from 20 million and ahead of the 26 million one Stifel analyst expected.
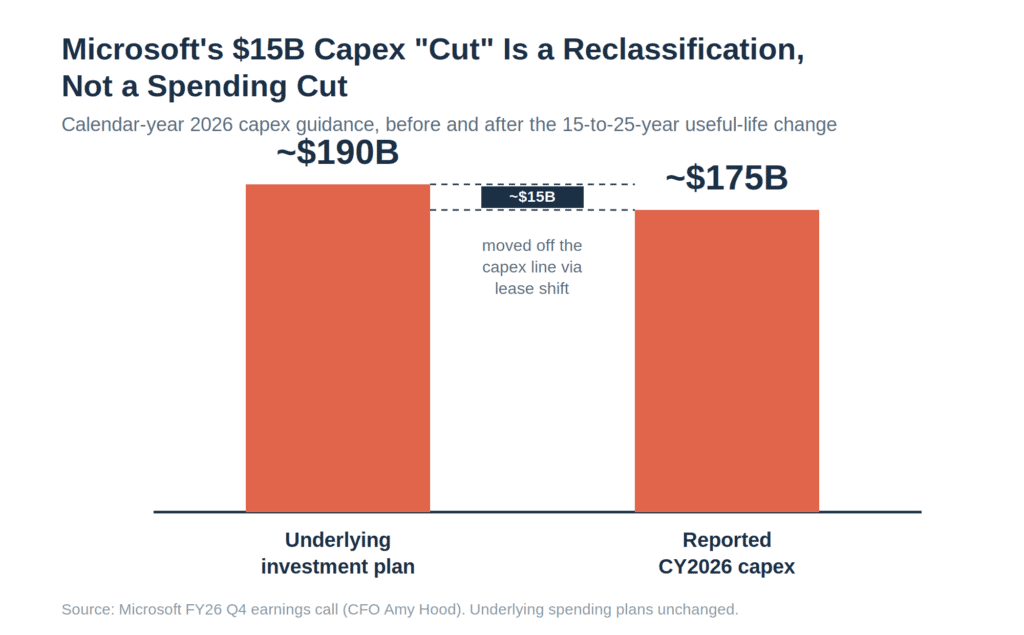
Then came the line that got the applause it did not deserve. Microsoft lowered its calendar-2026 capex forecast to about $175 billion, down from roughly $190 billion. For a market that has spent a year fretting about hyperscaler overspending, that sounded like discipline.
It was not. It was accounting.
The Numbers That Matter
CFO Amy Hood was clear about the mechanism, even if the headlines were not. Starting in fiscal 2027, Microsoft is extending the estimated useful life of its data centers and office buildings from 15 years to 25 years. That change does two things. It stretches out depreciation on those buildings, and it reclassifies more future data-center leases from finance leases to operating leases. Finance leases count toward reported capex. Operating leases do not.
So the $15 billion did not get cut. It got moved off the line where investors were looking. Hood said the underlying investment plan is unchanged. Every other number confirms it. Capex for the quarter was $41 billion, up nearly 70% year over year. Microsoft guided to more than $50 billion in the current quarter. The spending is not slowing down. It is accelerating. The reporting just got quieter.
The Real Story
Here is the part that got lost in the celebration. The profit jump and the capex “cut” are two separate stories, and neither is quite what it looks like.
The 31% profit jump is mostly real, but not entirely operating. Microsoft booked a $3.2 billion gain on its Anthropic investment this quarter and had lower-than-expected costs tied to its voluntary retirement program. Strip out the one-time Anthropic mark-up and the underlying earnings growth is still strong, but the headline overstates the run rate. That is a fair thing to flag, not a scandal.
The capex change is the one people are misreading in the other direction. Some are treating it as the reason profit jumped. It is not. The depreciation benefit does not even begin until fiscal 2027, and Hood herself called its effect on FY27 operating income “minimal.” The useful-life change is not about this quarter’s profit at all. It is about making future spending less visible, on two financial statements at once.
The Six-Year Problem Nobody Priced In
Now the detail that undercuts the whole accounting rationale. Microsoft is stretching the useful life of its buildings to 25 years. Fine. Concrete and steel last a long time. But roughly two-thirds of Microsoft’s capex goes to short-lived assets, the CPUs and GPUs that do the actual AI work. Those depreciate over about six years, and the company has said so plainly.
In other words, the part of the spend that dominates the bill is the part the accounting change does not touch. A GPU bought today will be obsolete long before the building it sits in reaches year 25. Extending the roof’s life does nothing to soften the treadmill of buying new chips every few years, which is the real, recurring cost of staying in the AI race. The reclassification cleans up the optics on the durable part of the asset base and leaves the expensive, fast-rotting part exactly where it was.
What Nobody Else Is Reporting
Microsoft is not doing anything unique here, and that is the actually interesting part. According to a Moody’s report earlier this year, the five largest hyperscalers are collectively carrying about $662 billion in future data-center lease obligations that sit off their balance sheets. Meta structured its $27 billion Hyperion project through an off-balance-sheet joint venture that its own auditor flagged as a “critical audit matter.” Google is funding its build-out with an $85 billion equity raise rather than the cash its ad business throws off, a pattern we broke down in our look at Google’s $514 billion cloud backlog.
The throughline: when AI spending was a badge of ambition, these companies bragged about it on the capex line. Now, one by one, they are engineering it off the headline metrics. Microsoft’s move also flatters a second number going forward. Operating-lease payments are excluded from standard free-cash-flow math, so shifting leases into that bucket quietly props up the “we are still free-cash-flow positive” talking point that Microsoft used this quarter to distinguish itself from a cash-flow-negative Alphabet. Microsoft’s free cash flow actually fell 23% this quarter. The accounting will make the next few look better than the cash reality.
The Counterargument
The steelman for Microsoft is genuinely strong, and any honest read has to sit with it.
First, the useful-life change is defensible on the merits. Microsoft has been operating data centers for two decades and has real evidence its buildings last well beyond 15 years. Aligning the accounting with reality is what accounting is supposed to do, and 25 years for a building is not aggressive.
Second, the business underneath is not a mirage. Azure at $100 billion growing 43% is a monster, and it is demand-constrained, not demand-starved. Hood said customer demand continues to exceed available capacity. The $678 billion in remaining performance obligations, Microsoft’s contracted-but-not-yet-booked backlog, is real signed revenue, and Hood noted the sequential growth came from customers beyond the frontier AI labs, not just OpenAI. Copilot beating estimates suggests the enterprise monetization thesis is finally converting. This is not a company hiding weakness. It is a company managing how strength gets presented.
Third, “off-balance-sheet” is not a synonym for “fraudulent.” These are contractual obligations disclosed in the footnotes, not hidden debts. The information is available to anyone who reads past the headline.
The Risk
The risk is not that the accounting is illegal. It is what the accounting reveals about sentiment. Companies do not reach for optics levers when they are confident the spending speaks for itself. They reach for them when they sense the audience is getting nervous about the return on that spending. When every hyperscaler starts moving AI capex off the headline at roughly the same moment, that is not a coincidence of accounting policy. It is a shared read on investor patience.
For Microsoft specifically, the exposure sits in the gap between $678 billion of contracted backlog and the six-year chip-replacement cycle. If AI demand growth slows even modestly while the GPU treadmill keeps running, the company is committed to buying obsolescing hardware against revenue that has to keep compounding to justify it. The accounting change does not reduce that risk. It just makes it harder to see on the two statements investors watch most.
What to Watch
Three things over the next few quarters. First, operating cash flow and lease liabilities together, not headline capex, because that is now where the true equipment burden shows up. Second, whether Copilot’s paid-seat growth holds its pace or stalls, since that is the cleanest proxy for whether the capex is turning into enterprise revenue rather than just capacity. Third, whether the other hyperscalers formalize similar useful-life or lease reclassifications in their own upcoming reports. If they do, the “capex discipline” narrative sweeping the sector this earnings season is largely a reporting artifact, and the real spending curve keeps bending up.
The Business Model Analyst Take
Microsoft had a great quarter. That is true and worth saying plainly. Azure past $100 billion is a genuine milestone, the backlog is real, and Copilot finally converting is the datapoint bulls have waited two years for.
But the tell in this earnings release is not the $100 billion. It is the $15 billion. The accounting move itself is legal, defensible, and arguably overdue. What matters is the timing and the company it keeps. When the single most valuable software company on earth, alongside every one of its peers, quietly decides this is the quarter to make AI spending look smaller, that is a sentiment indicator dressed up as a policy update. CFOs are pricing in doubt about AI capex returns before the market does, and they are doing it in the footnotes.
For anyone building or investing around this buildout, the lesson is simple and a little uncomfortable. Watch what these companies do with their reporting, not just what they say on stage. The spending has not changed. Only the lighting has. And you rarely dim the lights on something you are proud of.
For the underlying economics, see our breakdowns of the Microsoft business model, the Amazon business model and how AWS carries Amazon’s profit, and the Apple vs Microsoft comparison.