Wall Street, a Louisiana utility and its ratepayers are carrying the risk on Hyperion. Meta kept operational control and the only short exit.
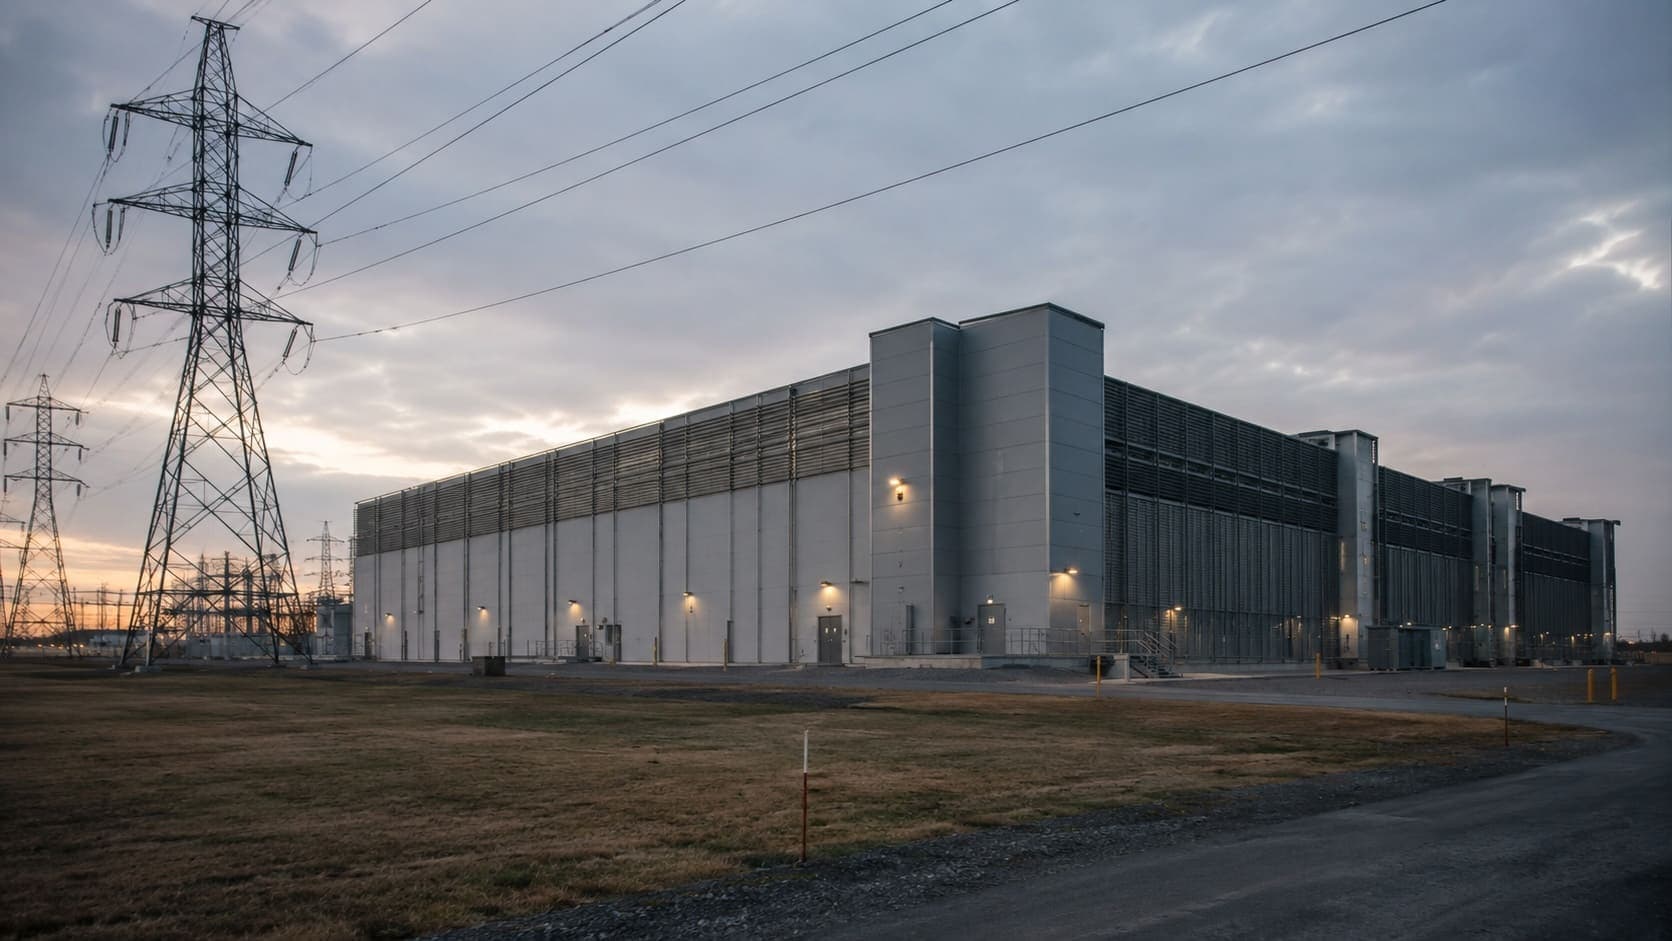
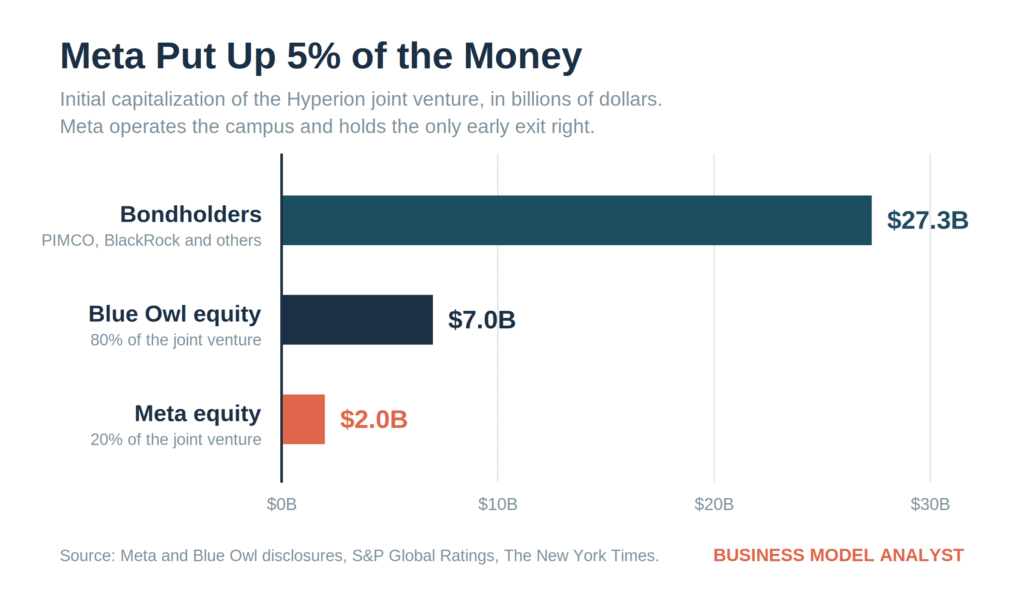
Meta’s Hyperion campus in Richland Parish, Louisiana now carries a $50 billion price tag. Meta contributed about $2 billion of the joint venture’s initial equity. Blue Owl put in $7 billion, bondholders led by PIMCO and BlackRock funded $27.3 billion, and Entergy is spending roughly $14 billion on ten gas turbines with the right to raise rates on Louisiana customers to cover part of the cost. Meta can exit its lease after four years. Blue Owl committed to 24. That gap is the deal.
The New York Times published an investigation on July 27 detailing how Meta secured the project through nine months of private talks, NDAs with more than 50 state officials, and a tax bill that legislators rewrote mid-session. The political story deserves the attention it is getting. The financial architecture underneath it deserves more, because other companies are already copying it.
What Happened
The Times reconstructed the deal from interviews with more than 40 people, plus corporate filings, tax records and property records. Entergy chief executive Phillip May pitched Louisiana to three Meta employees over dinner in New Orleans in January 2024. Meta said Louisiana was out of contention because it lacked a sales tax exemption on data center equipment and its legislature could not take up new exemptions that year.
Governor Jeff Landry’s team solved that in weeks. They took a pending bill that would have granted a rebate on fiber-optic equipment and rewrote it for data centers, because fiber sounded close enough. Revenue secretary Richard Nelson, who had planned to speak against the original bill, dropped his objection. Legislators passed it without knowing what it was for.
State officials announced Hyperion in December 2024 as a $10 billion project. It reached $30 billion by October 2025 and $50 billion this month, after Entergy raised its turbine plan from three units to ten. The campus runs a mile wide and more than five miles long. When it finishes, it will draw more than half of Entergy’s total generating supply and roughly seven times what New Orleans uses.
The Backstory
Two things happened on the same day in August 2025. Louisiana’s power commission voted 4 to 1 to approve the gas turbines, skipping the independent judicial review that normally tests whether a project serves the public interest. And Meta registered a Delaware entity called Beignet Investor LLC.
Beignet is a bankruptcy-remote special purpose vehicle. In October 2025 it issued a single senior secured, fully amortizing bond of $27.294 billion, priced at par with a 6.581% coupon and a final maturity in May 2049. Morgan Stanley ran the book alone. PIMCO took around $18 billion of it. BlackRock took more than $3 billion. S&P rated the paper A+, one notch below Meta’s own AA minus, because the rating agency read the bonds as Meta credit wearing a project finance costume.
Blue Owl funds own 80% of the joint venture that holds the campus. Meta owns 20%, operates the site, leases it back under a long-term agreement, and received a one-time $3 billion payout at closing. Meta also gave the venture a residual value guarantee covering the first 16 years of operation, a capped cash payment triggered if the lease ends and the campus is worth less than expected.
The Plan
Meta is converting capital expenditure into operating expense. A $27 billion data center built on Meta’s own balance sheet shows up as property, plant and equipment, drags on free cash flow, and lands in front of the rating agencies. The same campus built inside a Blue Owl joint venture shows up as a roughly $5 billion equity investment plus lease payments, with the residual value guarantee disclosed in the footnotes to the annual report rather than booked as a liability.
The trade cost Meta money. Its bonds price well inside 6.58%. Paying that spread bought three things Meta wanted more than the basis points: balance sheet capacity, ratings headroom, and a four-year exit on a 24-year asset.
Meta’s 2026 capital expenditure guidance already sits between $125 billion and $145 billion. Loading Hyperion’s full cost on top of that number would have forced a conversation with investors that Alphabet is already having about its own capex line.
The Business Model Angle
Every founder who has signed a lease instead of buying a building understands the first half of this. You give up ownership and residual upside to keep cash free and stay flexible. Meta ran that logic at a scale nobody had attempted before, and added a second move on top of it.
The second move is duration mismatch, and it points the other way. Bondholders own 24-year paper. The lease that services it depends on a tenant who can leave after four. If Meta walks, it owes the difference between the outstanding debt and whatever a replacement tenant or buyer will pay. Blue Owl says that would not be a costless decision. Nobody has said what it would cost, because nobody knows what a five-gigawatt AI campus in rural Louisiana is worth without Meta in it.
Debt service coverage on the bonds runs at 1.12 times. For every dollar of principal and interest due, the project generates $1.12 of cash. That is thin for a 24-year single-asset issue, and it holds only if the lease payments arrive on schedule for a quarter century.
The structure works because Meta’s advertising business is real. Meta booked $200.97 billion in 2025 revenue, and $196.18 billion of that came from ads. Bondholders are not underwriting AI demand. They are underwriting the Facebook and Instagram ad engine and its ability to keep paying rent through 2049. PIMCO bought a Meta credit proxy yielding 6.58% when Meta’s own paper yields less. That is the entire trade, and it is a reasonable one.
The awkward part sits on Meta’s side. A company that believed its AI compute would generate obvious returns would finance it the cheap way, on its own balance sheet, and keep the residual value. Meta paid a premium to rent the downside away. It is also building a cloud business to sell excess compute to other people, which is what you do when you are less than certain your own products will absorb what you built.
The Risk
Insurers refused to fully cover Hyperion. The campus sits in the Louisiana Delta flood plain, and its size made underwriters balk. Project planners assembled about $4 billion of coverage for a $50 billion asset. One executive who declined the business called building there in a flood plain crazy. Meta and Blue Owl say tornadoes pose a larger threat than water and full coverage was unnecessary.
The termination clause matters more than the coverage gap. If a natural disaster shuts the campus down for two years, Meta can walk away without paying the difference on what remains owed under the lease. Bondholders would hold a $27 billion claim against a flooded field in Richland Parish. Blue Owl says no scenario exists in which a project this large faces destruction from a natural catastrophe, which is a strong claim about a region that flooded in 2016.
Entergy customers carry a separate piece. Meta agreed to cover maintenance and operating costs on the new turbines for half of their 30-year life. Entergy kept the right to raise prices on all its customers for the rest. Commissioner Davante Lewis cast the lone dissenting vote and said he could not verify what he was being asked to approve.
Then there is the copying problem. Moody’s counted $662 billion in future data center lease obligations sitting off the balance sheets of Amazon, Meta, Alphabet, Microsoft and Oracle, and warned that public disclosures may not show the full picture. Companies have moved more than $120 billion of data center spending into SPVs in about eighteen months. Morgan Stanley expects private credit to supply another $800 billion for data centers over the next two years. Meta is raising a separate $13 billion SPV for a Texas campus.
The honest counterargument runs like this: project finance has funded pipelines, power plants and toll roads for decades using exactly these mechanics, and calling it Enron accounting misreads a mature market. Bondholders got disclosure, a rating and a covenant package. Nobody hid anything from PIMCO.
The reply is that pipelines do not become obsolete in four years. The concrete and the substations at Hyperion will outlast the bonds. The GPUs inside will not. A 2049 maturity assumes somebody wants five gigawatts of AI compute in northeast Louisiana for the next 24 years, and the only party who has expressed an opinion on that reserved the right to change its mind in 2029.
Quick Questions
Does the debt appear on Meta’s balance sheet? No. Blue Owl appoints the joint venture’s board, so Meta accounts for its 20% stake using the equity method. The residual value guarantee appears in annual report footnotes rather than as a recorded liability.
Who actually holds the $27 billion? Bond investors. PIMCO took roughly $18 billion, BlackRock more than $3 billion, and other institutional buyers took the rest. Many of those funds sit inside pension and retirement portfolios.
Why would Meta pay 6.58% when it can borrow cheaper? Balance sheet capacity and optionality. The spread buys Meta the ability to keep spending elsewhere without pressuring its credit rating, plus a four-year exit it would not have on an owned asset.
What happens to Louisiana if Meta leaves in 2029? Meta owes penalties and the shortfall on the lease. Entergy holds ten gas turbines built for a customer that consumed half its supply, with the right to recover costs from remaining ratepayers. Richland Parish keeps the roads and the tax base.
Is anyone else doing this? Microsoft, Oracle and Google have all explored SPV or programmatic financing platforms with similar architecture. Hyperion is the template.
The Business Model Analyst Take
Landry defended the secrecy by pointing at Zuckerberg’s own playbook. “He didn’t do it by going out there and telling everybody what he was doing,” the governor said. He was describing the negotiation. He could have been describing the balance sheet.
The lesson for operators has nothing to do with Louisiana politics. Meta demonstrated that a company with a strong credit rating and a boring cash machine can rent out its own risk profile. It sold access to Meta credit at a 6.58% yield, kept the compute, kept operational control, and pushed the tail risk onto bondholders, a utility’s customers, and an insurance market that already said no.
Watch the four-year mark. Every structure of this kind now being pitched to Microsoft, Oracle and Amazon carries the same assumption Hyperion carries: that AI demand in 2029 justifies rent through 2049. Meta wrote itself an exit from that assumption. The pension funds holding Beignet paper did not.