Mercedes-Benz SWOT Analysis at a glance
What it is: A structured look at the internal Strengths and Weaknesses and the external Opportunities and Threats facing Mercedes-Benz Group AG (Frankfurt: MBG), the luxury arm of the former Daimler empire and the maker of the S-Class, AMG, Maybach and the G-Class.
The 2026 takeaway: Mercedes is still one of the most valuable and most profitable luxury car brands on earth, but 2025 was its worst year since the pandemic. Group revenue fell to EUR 132.2 billion and net profit nearly halved to EUR 5.3 billion, squeezed by US tariffs, a collapsing China business, and softer electric vehicle demand than its own 2021 plan assumed. The strengths (brand, pricing power, a top-end product mix) are intact. The pressure is now coming from outside, and the company’s answer is cost-cutting plus a slower, hybrid-friendly transition rather than the all-electric sprint it once promised.
Figures reflect Mercedes-Benz Group’s audited FY2025 results (reported February 12, 2026) and company sales disclosures through year-end 2025.
Mercedes-Benz turns 140 in 2026, counting from the day Carl Benz patented the first motor car. That heritage is real, and the three-pointed star still sells. But a SWOT analysis is only useful if it describes the company as it is now, not the comfortable version that circulates in older write-ups. The 2026 version of Mercedes is a business defending high margins in a market that has stopped cooperating.
This analysis maps where the brand is genuinely strong, where the cracks have widened, and what the next two years could realistically deliver. If you want the wider method, our library of SWOT analysis examples breaks the framework down company by company.
Mercedes-Benz SWOT Analysis Summary
| Dimension | The short version |
|---|---|
| Strengths | World’s #2 most valuable auto brand (USD 50.1B), premium pricing power, top-end mix (S-Class, AMG, Maybach, G-Class), strong balance sheet, record AMG and G-Class years |
| Weaknesses | Profit nearly halved in 2025, heavy China exposure (down 19%), thin and falling margins, EV lineup behind its own plan, brand value sliding two years running |
| Opportunities | Hybrid-plus-electric flexibility, MB.OS software and assisted driving, electric CLA and GLC momentum, cost program savings, top-end and emerging-market growth |
| Threats | US import tariffs, BYD and Chinese rivals, Tesla, EV demand uncertainty, Euro 7 and tightening emissions rules, battery recalls, FX swings |
The headline numbers tell the story competitors built before the 2025 results landed: this is no longer a smooth upmarket growth story. It is a high-margin business absorbing real external shocks.
Mercedes-Benz Strengths
Mercedes still owns most of the assets that made it valuable in the first place. The difference in 2026 is that these strengths are now doing defensive work, holding the line while the rest of the business resets.
| Strength | Why it matters in 2026 |
|---|---|
| Brand value and prestige | Interbrand ranks Mercedes the #2 auto brand worldwide at USD 50.1 billion, behind only Toyota |
| Pricing power | Premium positioning lets Mercedes hold price where mass-market rivals discount |
| Top-end product mix | Top-end models hit 268,000 units, a record 15% of car sales in 2025 |
| Record halo brands | AMG delivered 145,000 units (+7%), the G-Class a best-ever 49,700 (+23%) |
| Financial resilience | Net industrial liquidity of EUR 32.2 billion; a 20%-plus total shareholder return in 2025 |
| Global footprint | Production and sales in nearly every country, spreading regional risk |
A brand that still commands a premium
The three-pointed star is one of the most recognized marks in the world, and it converts directly into money. In the 2025 Interbrand Best Global Brands ranking, Mercedes placed tenth overall and second among carmakers at USD 50.1 billion, ahead of BMW and well ahead of Tesla. That brand equity is what lets Mercedes charge what it charges and still find buyers.
The caveat, which we return to in Weaknesses, is direction. That same Interbrand figure fell 15% in 2025 and had already dropped the year before. The brand is strong, but it is not getting stronger right now.
The top end is carrying the company
Mercedes spent the past few years pushing deliberately upmarket, and in 2025 that mix did exactly what it was designed to do. Top-end vehicles (S-Class, Maybach, AMG, G-Class and the EQS pair) reached 268,000 units, a record 15% of all car sales, up from 14% a year earlier. AMG had one of its best years ever at 145,000 deliveries, and the off-road G-Class set a record at 49,700 units, up 23%. In China, half of every S-Class sold was the pricier Maybach version.
This is the part of the lineup that defends margin. When volume softens, the highest-value cars hold up best, and Mercedes leaned on that hard in 2025.
A balance sheet built to absorb a bad year
Even after profits dropped, Mercedes stayed financially solid. Net industrial liquidity rose slightly to EUR 32.2 billion, free cash flow from the industrial business came in at EUR 5.4 billion, and the company still delivered a total shareholder return above 20% on the year. It funded a EUR 3.50 per share dividend and launched a buyback of up to EUR 2 billion. That cushion is what lets management restructure on its own timeline instead of in a panic.
Mercedes-Benz Weaknesses
This is where the 2026 picture diverges most from the older analyses still ranking online. The weaknesses are no longer abstract risks. They showed up in the 2025 financials.
| Weakness | The 2025 evidence |
|---|---|
| Profit collapse | Net profit fell 48.8% to EUR 5.3 billion; reported EBIT fell 57.2% |
| China dependence | China car sales fell roughly 19%, the single biggest drag on the year |
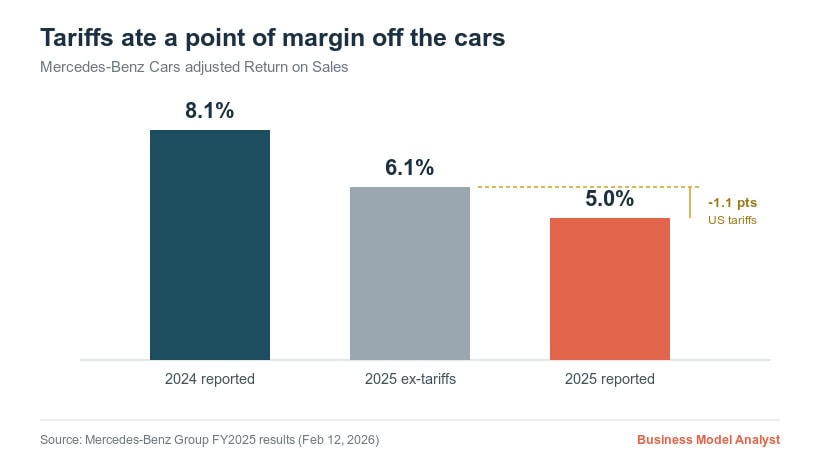
| Margin compression | Cars adjusted Return on Sales fell from 8.1% to 5.0% |
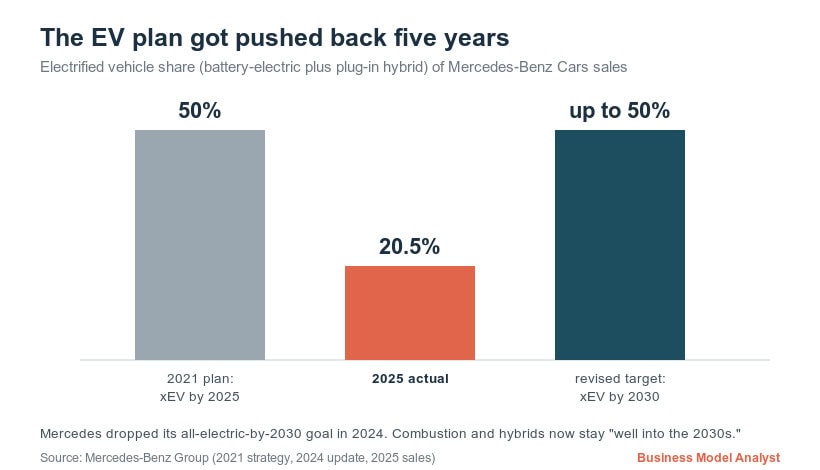
| EV lineup behind plan | Electrified share was 20.5%, far short of the 50% once targeted for 2025 |
| Falling brand value | Interbrand value down 15% in 2025, a second straight annual decline |
| Premium-only exposure | Little protection when luxury demand cools in a downturn |
The profit drop was severe
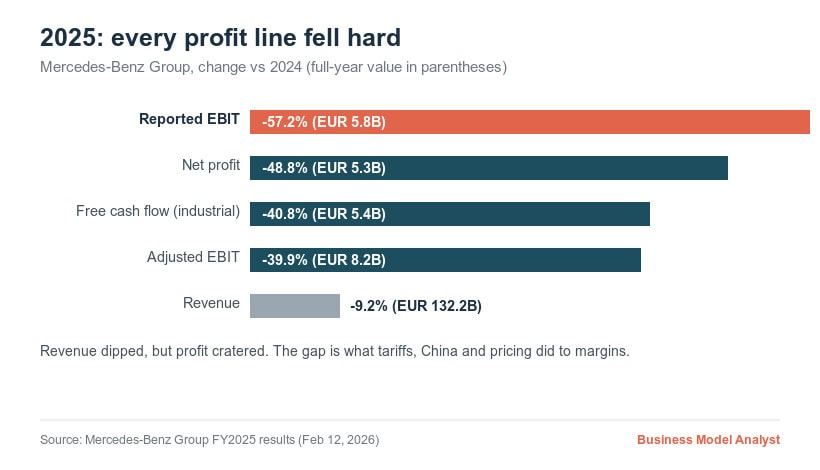
The cleanest way to see 2025 is the gap between revenue and profit. Revenue slipped 9.2%, which is uncomfortable but survivable. Profit did far worse. Reported EBIT fell 57.2% to EUR 5.8 billion, adjusted EBIT fell about 40% to EUR 8.2 billion, and net profit nearly halved to EUR 5.3 billion. That is operating leverage working in reverse: when a luxury automaker loses volume and pricing at the same time, the damage lands disproportionately on the bottom line.
China stopped being a tailwind
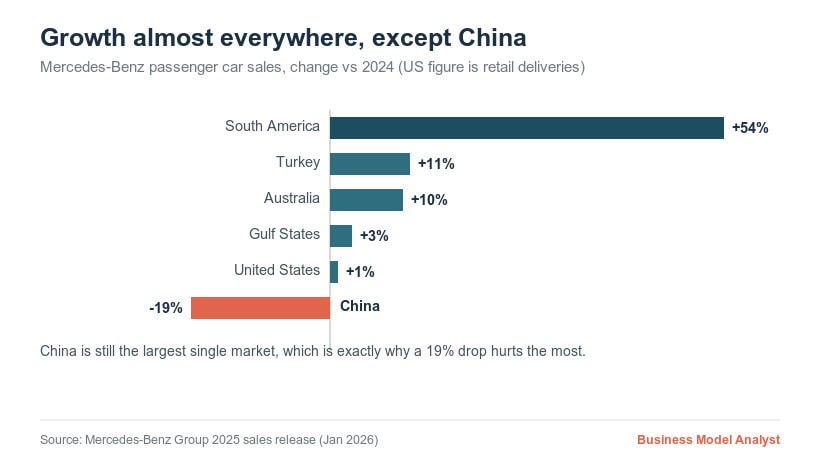
For a decade China was where Mercedes grew. In 2025 it became the problem. Sales in the company’s largest market dropped around 19%, as Chinese buyers shifted toward domestic brands led by BYD and the luxury segment itself came under pressure. Mercedes held its lead in the ultra-premium tier (cars priced above one million RMB), but that niche is not large enough to offset the broader decline.
The chart makes the dependence visible. Mercedes grew in most regions in 2025, with South America up 54% and solid gains in Europe, Australia and Turkey. None of it mattered enough, because China is still the biggest single market, so a double-digit fall there outweighs growth almost everywhere else.
The electric plan slipped
Older SWOT write-ups describe Mercedes as simply “late” to EVs. The 2026 reality is more specific and more interesting. Mercedes was not late on ambition. In 2021 it committed to going all-electric by 2030 where conditions allowed, with electrified models hitting 50% of sales by 2025. Demand did not follow. By 2024 the company had walked that target back, saying combustion and hybrids would stay “well into the 2030s” and that electrified vehicles would reach up to 50% of sales by 2030, not 2025.
In 2025, electrified vehicles (battery-electric plus plug-in hybrid) were 20.5% of car sales. Within that, plug-in hybrids grew while pure battery-electric sales actually slipped for much of the year before a fourth-quarter rebound led by the new electric CLA. So the real weakness is not a missing product line. It is that the demand Mercedes planned its factories and margins around did not arrive on schedule, and the recovery now rides heavily on two new models.
Mercedes-Benz Opportunities
The opportunities are real, but most of them are about execution speed rather than new ideas. Mercedes knows what it needs to do. The question is whether it does it fast enough.
| Opportunity | The angle |
|---|---|
| Powertrain flexibility | Selling ICE, hybrid and electric in parallel hedges against EV demand swings |
| Software and ADAS | MB.OS operating system and MB.DRIVE assisted driving as recurring revenue and differentiation |
| New EV momentum | Electric CLA named European Car of the Year 2026; electric GLC order books full into H2 2026 |
| Cost program | “Next Level Performance” targets material cost cuts of roughly 8% by 2027, 10% beyond |
| Top-end and emerging markets | Maybach, AMG and the G-Class plus growth in South America and the Gulf |
Flexibility is now a feature, not a retreat
The decision to keep combustion and hybrid options alive looked like a climbdown in 2024. In 2025 it looked like a hedge. With EV demand uneven across regions, being able to sell whatever powertrain a given market actually wants protects volume. The risk is that running three powertrain families at once is expensive, which is exactly why the cost program matters so much.
Software is the long game
Mercedes is rolling out its own operating system, MB.OS, across the lineup, alongside its MB.DRIVE assisted-driving stack and partnerships (including Momenta and ByteDance for the China market). If the company can turn connected features into recurring software revenue, it changes the margin math in a way that hardware alone cannot. This is the same playbook every premium automaker is chasing, so the prize is real but so is the competition. For how rivals approach the customer side of this, our BMW marketing strategy breakdown is a useful contrast.
Two new EVs are doing the heavy lifting
The electric CLA was named European Car of the Year 2026 and rated the best car ever tested by German magazine Auto Motor und Sport, and demand has been strong enough to fill order books quickly. The electric GLC, arriving in early 2026, reportedly has orders booked well into the second half of the year. These are the proof points that the electric portfolio can sell when the product is right. The opportunity is to extend that momentum across the range before rivals close the gap.
Cost discipline as a profit lever
The “Next Level Performance” program already contributed more than EUR 3.5 billion to EBIT in 2025 and targets material cost reductions of roughly 8% by 2027. If management hits those numbers while volume recovers, margins can rebuild without needing a sales miracle. That is the single most controllable lever Mercedes has.
Mercedes-Benz Threats
The threats are where Mercedes has the least control, and in 2025 they did the most damage.
| Threat | Why it bites |
|---|---|
| US import tariffs | New auto tariffs cost the cars division roughly 1.1 points of margin in 2025 |
| Chinese competition | BYD and domestic brands are taking premium share in Mercedes’s biggest market |
| Tesla and EV rivals | Price and technology pressure across the electric segment |
| EV demand uncertainty | Wrong-footed capacity planning if adoption stays slow or accelerates suddenly |
| Regulation | Euro 7 and tightening emissions rules raise compliance cost |
| Recalls and quality | A 2025 EQB battery-fire recall required high-voltage battery replacements |
Tariffs hit the margin directly
The single clearest external shock in 2025 was US trade policy. New import tariffs on vehicles and parts cost Mercedes-Benz Cars roughly 1.1 percentage points of margin, the difference between an adjusted Return on Sales of 6.1% excluding tariffs and the 5.0% it actually reported. Mercedes responded by creating a dedicated North America CEO role and managing US inventory tightly, but a tariff is a tax it cannot fully engineer away.
Chinese rivals are the structural threat
China is not just a soft patch. It is a competitive realignment. Domestic brands led by BYD have moved up the price ladder with strong technology and aggressive pricing, and they are winning customers Mercedes used to count on. The detailed case for why these challengers are durable rather than temporary is laid out in our BYD SWOT analysis and Tesla SWOT analysis. For Mercedes, the takeaway is that its largest market now has homegrown competition it did not face a decade ago.
Quality and recall risk
Reputation is an asset that erodes fast. In 2025 Mercedes faced a high-voltage battery recall on EQB electric models over fire risk, a recall that US safety regulators saw expanded into 2026 when a software fix proved insufficient and full battery replacements became the remedy. For a brand whose entire premium hinges on engineering trust, EV battery safety is a sensitive place to stumble.
The premium trap in a downturn
Finally, the same upmarket focus that protects margin in good times concentrates risk in bad ones. Luxury buyers can defer a purchase, and in a sharp recession Mercedes has less of a budget-tier cushion than broader rivals like Toyota. The strategy is sound, but it leaves the company exposed to swings in high-end discretionary spending.
The Business Model Analyst Take
Mercedes-Benz in 2026 is a strong company having a hard time, and the two facts are not in conflict. The brand, the pricing power, and the top-end mix are genuinely valuable and genuinely defensible. The balance sheet absorbed a brutal year without forcing a fire sale. Those are the marks of a business that is pressured, not broken.
But the 2025 results retire the comfortable narrative for good. Net profit nearly halved, China stopped being a growth engine and became the biggest drag, tariffs took a clean bite out of margin, and the electric transition is running years behind the plan Mercedes set for itself. Crucially, the worst of this came from outside the company. You cannot cost-cut your way out of a tariff or a shift in Chinese consumer taste.
The strategic question for the next two years is narrow. Can Mercedes rebuild margin through its cost program and a recovering top-end and EV mix faster than tariffs, China and EV uncertainty keep dragging it down? The CLA and GLC suggest the product side can deliver when it gets the formula right. The cost program suggests management knows where the levers are. What no one controls is the external environment, and in 2025 that environment did most of the damage. For founders and operators, that is the real lesson here: a premium brand can do almost everything right internally and still get knocked sideways by forces it does not own. The strengths buy Mercedes time. Whether that is enough depends on a recovery it can only partly engineer.