
Skye Anderson takes over a U.S. business that keeps 82 cents of every dollar it collects from franchisees and 12 cents of every dollar its own restaurants ring up. The turnaround she was hired to run needs franchisee capital.
McDonald’s reported U.S. same-store sales up 0.8% for the quarter ended June 30, 2026, in line with analyst forecasts but behind its own recent pace. Guest counts fell. Higher checks and pricier items covered the gap. On the same morning, the company named Skye Anderson president of McDonald’s USA, replacing Joe Erlinger. The two announcements belong together: a comparable-sales number carried by check growth protects the franchisor’s revenue line and squeezes the operator underneath it, and Anderson’s job is to persuade the owners of roughly 13,000 U.S. franchised restaurants to fund a remodel cycle at the exact moment their unit economics are thinning.
Adjusted earnings came in at $3.38 per share, ahead of forecasts. Revenue of $7.1 billion landed about $30 million short. Net income rose 5% to $2.36 billion. The stock fell 2%.
What Happened
Anderson, a 26-year McDonald’s veteran, moves into the U.S. presidency four months after the company created a U.S. chief operating officer role and gave it to her. Erlinger, who ran the U.S. business since 2019, is leaving after more than two decades and will advise into early next year.
Chris Kempczinski framed the appointment around speed and execution, calling Anderson “a proven change agent who can act with urgency to mobilize our system.” The word doing the work there is system. At McDonald’s, the System means franchisees, suppliers and employees, and 95% of U.S. restaurants sit on the franchisee side of that line.
U.S. comparable sales decelerated from 3.9% in the first quarter. Ahead of the release, Citi’s Jon Tower cited third-party visit data showing U.S. foot traffic down 4.6% year over year for the quarter, with May the worst month, and modeled U.S. same-store sales at negative 2%. The print came in better than that, and McDonald’s confirmed the direction underneath it: transactions negative, average check positive. Management had told investors in May to expect a meaningful deceleration against April 2025, when the Minecraft movie tie-in meal ran, and said the challenging environment had not improved.
The Backstory
Check-led growth is not a one-quarter event. It is now the third straight company disclosure describing U.S. comps the same way.
The 2025 Form 10-K attributes the year’s 2.1% U.S. comparable sales gain to average check growth. The first-quarter 2026 10-Q attributes the 3.9% U.S. gain primarily to positive check growth. Q2 2026 repeats the pattern with the traffic line now visibly negative.
Meanwhile the operator’s side of the ledger has been eroding. Kempczinski told CNBC in September 2025 that franchisee cash flow sat roughly 10% below its post-pandemic peak. McDonald’s own franchise disclosure documents make the compression precise. In the 2025 FDD, an independent traditional U.S. restaurant doing $3.2 million in annual sales showed operating income before occupancy costs of $812,000. In the 2026 FDD, the same $3.2 million volume produced $795,000. At $3.4 million, the figure slipped from $879,000 to $864,000.
Same sales, less profit. That is the whole story of a check-led comp told from the franchisee’s chair.
The Plan
Kempczinski unveiled McDonald’s Next in a message to the system on June 1, 2026, alongside the company’s Worldwide Convention in Las Vegas, retiring the Accelerating the Arches framework that had run since 2020. Four pillars: menu, consumers, restaurants and people. You can read our breakdown of McDonald’s NEXT growth strategy for the competitive picture against Chick-fil-A and Raising Cane’s.
The physical commitments are the expensive part. McDonald’s showed a new restaurant prototype with a kitchen visible from the dining room and the parking lot, a window onto the espresso station with a bar and stools in front of it, dual service counters splitting drive-thru from front counter, and a returning playplace. It is testing hand-breaded chicken strips in Chicago and pointing to Malaysia as proof the system can execute the process at scale. An automated ordering system branded ARCHY is running in five U.S. restaurants.
Every one of those items lands in a building. Kitchens get rebuilt for hand-breading. Beverage bars get plumbed. Prototypes get constructed. Someone writes those checks.
The Business Model Angle
McDonald’s does not sell hamburgers for a living. It collects a percentage of other people’s hamburger sales and rents them the dirt.
In 2025, U.S. franchisees rang up $51.9 billion in restaurant sales. McDonald’s booked $7.37 billion of that as franchised revenue, about 14 cents per franchisee dollar in rent and royalties. After its own occupancy costs, it kept $6.08 billion, or 11.7 cents. Its roughly 700 company-operated U.S. restaurants sold $3.1 billion of food and produced $360 million of restaurant margin.
Run those as percentages and the two businesses stop resembling each other.
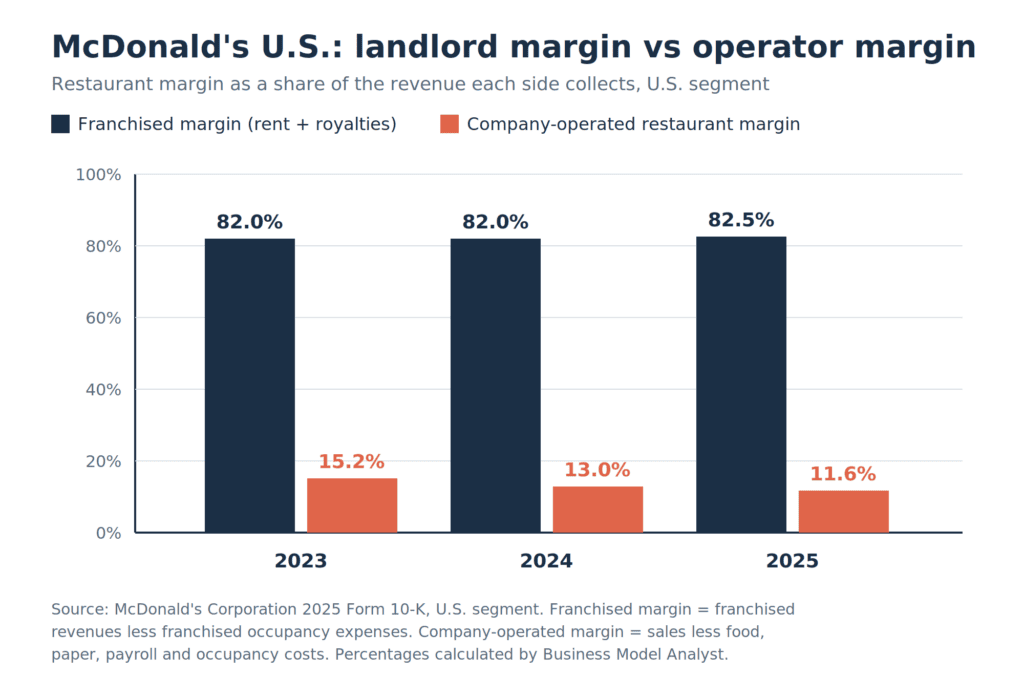
The navy bars barely move. The coral bars have lost 360 basis points in two years. On the first-quarter 2026 call, management called U.S. company-operated margins unacceptable and said it was reviewing the right ownership mix for those restaurants. Anderson has held direct leadership of McOpCo, U.S. National Operations and Restaurant Development since the spring. She already owns the unacceptable number.
Now trace where a remodel actually lands. McDonald’s sets conventional franchise rent as a function of what McDonald’s itself spent acquiring and developing the site. Its 2022 disclosure schedule started new traditional restaurants at 10% of sales where the company’s cost came in under $1.55 million and climbed to 15.75% where the company spent between $3.51 million and $3.61 million, adding a quarter point for every additional $100,000. Restaurants built before 2020 generally start closer to 8.5%. Royalties on newly built and company-acquired U.S. units went from 4% to 5% on January 1, 2024, the first increase in nearly 30 years.
Stack that against the FDD. A franchisee doing $3.2 million on a pre-2020 site at 8.5% rent and a 4% royalty pays McDonald’s about $400,000 and keeps roughly $395,000 before depreciation, interest and income tax. The same $3.2 million on a newly built site at 10% rent and 5% royalty leaves about $315,000. At the top of the published rent scale, a heavily built store paying 15.75% and 5% leaves closer to $131,000.
The nicer the building McDonald’s puts up, the larger the slice of the operator’s sales it takes back as rent. That is not a loophole. It is the pricing formula working as designed, and it is why the National Owners Association argued back in 2023 that new units “will not provide a historical return for the franchisee.”
Worth saying plainly: McDonald’s has not raised its take. The share of U.S. franchisee sales it collects has drifted from 14.35% in 2023 to 14.19% in 2025. Corporate is not squeezing harder. The sales dollars are simply arriving from fewer transactions, and a restaurant’s labor hours, equipment wear and management load track transactions rather than dollars. Our McDonald’s business model teardown covers how the real estate layer got built in the first place.
The Risk
For shareholders, this structure is the point. A 46.1% operating margin and $7.2 billion of free cash flow exist because McDonald’s converted operating risk into rent. Weak traffic barely dents the franchised revenue line. That resilience is the first thing any McDonald’s SWOT analysis puts in the strengths column.
The exposure sits one cycle out. McDonald’s has guided 2026 capital expenditure to $3.7 to $3.9 billion, up from $3.4 billion, with another $300 to $500 million increase signaled for 2027 on the way to 50,000 restaurants. It returned $7.1 billion to shareholders in 2025. If franchisees slow-walk the prototype, McDonald’s can co-invest, which it says it may do, and that money comes off the same line already climbing. Or it can wait, and the remodel cycle stretches out past the September investor event where Citi expects management to argue the case for asset investment.
There is a second path worth watching. Reviewing the ownership mix for McOpCo could mean selling company restaurants to franchisees. Doing so converts an 11.6% margin into an 82.5% one overnight and flatters the P&L. It also closes the window through which McDonald’s watches its own operations from the inside, at the moment it has staked a growth plan on operational quality.
The bull case is mix rather than price. Six new drinks landed on May 6, and beverages carry better margins than beef. If check growth comes from customers trading up to a crafted soda instead of paying more for the same Quarter Pounder, the franchisee’s economics improve with the average ticket. Nothing in the second-quarter guest count suggests that has started.
Quick Questions
Did McDonald’s miss the quarter? Adjusted earnings of $3.38 beat. Revenue of $7.1 billion missed by roughly $30 million. U.S. same-store sales of 0.8% met consensus. The stock still fell 2%, which tells you the market was reading the traffic line.
Why does a franchisor care about guest counts at all? Short term, it does not care much. Rent and royalties key off sales dollars. Long term, transactions determine whether franchisees can afford to reinvest, and reinvestment determines whether McDonald’s reaches 50,000 restaurants by the end of 2027.
Is Skye Anderson a marketing hire? No. She was CFO in Australia, spent six years leading U.S. field business including the West Zone and its 5,700-plus restaurants, then built Global Business Services from scratch with offices in Hyderabad and Mexico City. Finance, shared services and operations. McDonald’s went shopping for a plumber.
How much does a U.S. McDonald’s actually earn? The 2026 FDD reports operating income before occupancy costs of $732,000 to $864,000 across the $3.0 million to $3.4 million sales band. Rent, royalty, depreciation, interest and taxes all come out after that. Average U.S. franchised volume reached $4.06 million in 2025.
The Business Model Analyst Take
McDonald’s has spent seventy years engineering a business that gets paid whether or not the restaurant is any good. It worked. The 2025 numbers show the franchisor clearing 82.5 cents of margin on every dollar of franchised revenue while its own restaurants cleared 11.6 cents on every dollar of food they sold.
That design has one bill attached, and it arrives whenever the brand needs the stores to change. McDonald’s Next needs hand-breaded chicken lines, espresso bars, dual counters and a new building. McDonald’s collects the upside as rent and a royalty. The franchisee funds the construction, absorbs the labor, and then pays a rent percentage calculated off how much the construction cost.
Appointing Anderson reads as an admission that the constraint moved. Erlinger’s era was about price and value messaging aimed at the customer. Anderson’s brief points inward at supply chain, technology, development and company-operated restaurants, which is the machinery you fix when the problem is no longer what you say but what happens between the order and the tray.
Watch the September investor meeting for the number nobody has committed to yet: how much of the McDonald’s Next remodel McDonald’s funds itself. A high figure means the franchisor blinked and capital intensity rises against a stock already at its cheapest forward multiple in a decade. A low figure means Anderson has to sell independent owners on a construction project that raises the rent on their own restaurants. Chick-fil-A runs the opposite model and owns its restaurants outright, which is why its strengths and weaknesses read nothing like this, and why Chipotle never had this conversation at all.
Rent is a wonderful business until you need the tenant to renovate.