The spice maker will also headquarter internationally in the Netherlands, a tell about who really ends up owning the combined foods giant.
McCormick will seek a secondary listing on the London Stock Exchange on top of its existing New York listing, part of its planned merger with Unilever’s foods business into a company worth more than $65 billion. The deal should close by mid-2027. The London move, paired with a Netherlands international headquarters, signals that former Unilever shareholders will own most of what McCormick runs.
McCormick built its reputation on doing one thing well: spices and flavor, sold at premium margins. It is about to become something much larger and much harder to explain. The London listing announced Thursday is the clearest sign yet of what that transformation actually costs.
What Happened
McCormick said Thursday it will pursue a secondary listing on the London Stock Exchange, adding a UK line to its current New York Stock Exchange listing. The company framed the move as a way to smooth capital flows and improve liquidity for shareholders.
Alongside the listing, McCormick said the combined company will set up an international headquarters and keep a substantial presence in the Netherlands, where Unilever has operated for more than a century. The company also reorganized itself into four commercial divisions ahead of the close: Americas consumer, international consumer, global food service, and global flavor. That split carves the old consumer business into two divisions along geographic lines.
The proposed merger with Unilever’s foods arm should close by mid-2027 and create a company valued above $65 billion including debt.
The Backstory
Unilever and McCormick announced the deal on March 31, 2026, in the second-largest food transaction on record. Unilever agreed to spin off its foods division, home to Knorr, Hellmann’s, and other pantry staples, and merge it with McCormick, the owner of Frank’s RedHot and Cholula. The combined entity carries an enterprise value near $65.8 billion.
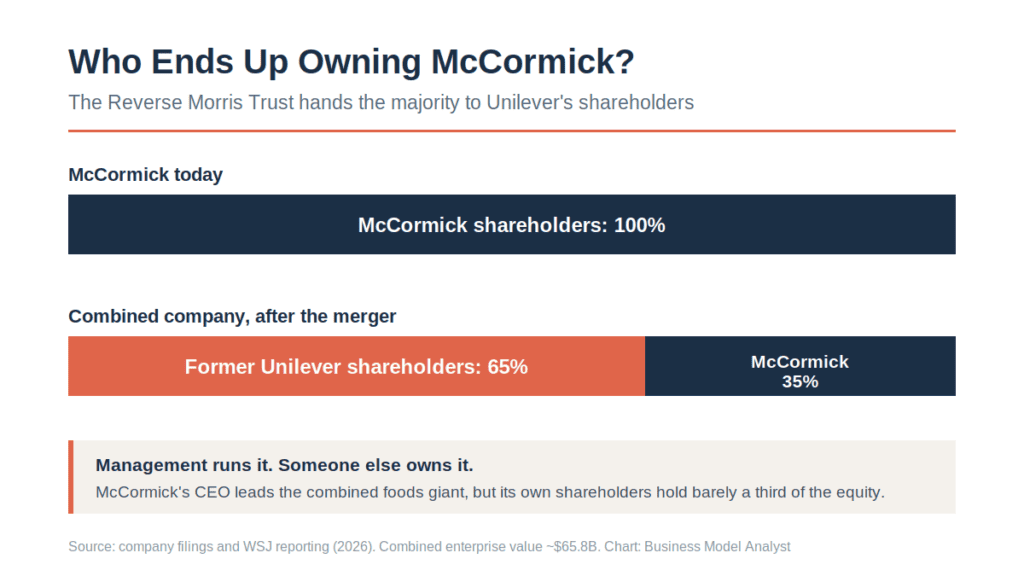
The structure matters more than the price. The companies used a Reverse Morris Trust, a tax-efficient mechanism that lets Unilever hand its food business to McCormick without triggering a large tax bill. The catch: in an RMT, the seller’s shareholders end up owning the majority of the merged company. Unilever’s holders will control roughly 65% of the combined equity. McCormick’s own shareholders will hold about 35%. McCormick pays Unilever $15.7 billion in cash on top, funded through new debt, and its CEO Brendan Foley leads the result.
When the two companies announced the deal, shares in both fell around 5%. That reaction is the part the celebratory coverage skipped. The market disliked this arrangement for both sides at once.
The Plan
The London listing solves a problem the deal structure created. Unilever’s shareholder base sits in Europe and holds a London-listed stock. Hand those investors a stake in a US-listed food company through the merger, and many of them face a choice between holding an unfamiliar NYSE ticker or selling. Some Unilever investors had already signaled they were reluctant to own a large publicly traded American food company, analysts said. A London line gives those holders a way to stay in without switching markets.
The Netherlands headquarters follows the same logic. Unilever’s roots run deep there, and keeping an operational and legal presence in the region reassures the shareholder base that inherited control of the business. The four-division reorganization sets up the integration, separating consumer sales by geography so the Americas and international teams can run on their own terms.
The Business Model Angle
Two opposite strategies collide in this single deal, and that is what makes it worth studying.
Unilever is shrinking on purpose. For years its foods brands grew slowly and dragged down the group’s valuation multiple. By offloading them, Unilever becomes a focused beauty, personal-care, and home business that can trade closer to specialist peers. Investors have pushed conglomerates toward this kind of simplification for a decade, and Unilever finally moved.
McCormick is doing the reverse. It starts as a focused pure-play with a premium multiple earned through category dominance and high margins on spices. The merger roughly triples its size by bolting on lower-growth legacy food brands and about $15 billion of new debt. The focus that earned McCormick its premium is the thing it is trading away.
The London listing exposes the deeper mechanic. McCormick’s management runs the combined company, but McCormick’s shareholders own the minority of it. The corporate structure has to serve the majority owners, who came over from Unilever. So a Maryland spice company lists in London and headquarters internationally in the Netherlands, not because those geographies fit McCormick, but because they fit the shareholders McCormick’s leaders now answer to. The RMT gave McCormick operational control and handed away ownership control. This week’s announcement is the bill arriving.
For a founder or operator, the lesson sits in the fine print of how deals get financed. A tax-efficient structure is not a free structure. The RMT saved a fortune in tax, and the price of that saving is a company whose owners and whose managers pull in different directions from day one.
The Risk
The debt is the first problem. McCormick is taking on roughly $15 billion to fund the cash portion, pushing leverage to around 4.3 times EBITDA. Integration has to go smoothly to service that load, and management has set a target of about $600 million in annual cost savings by 2029 to justify it.
The second risk is the one Unilever just walked away from. Foods volumes have been muted for years. McCormick is buying into a category that its own seller found too sluggish to keep. If McCormick cannot revive growth in Knorr and Hellmann’s, it will have traded a fast, high-margin spice business for a slow, indebted one.
The third risk is governance. Operational control and ownership control now sit in different hands. If the two sets of shareholders disagree about strategy, dividends, or capital allocation, the split between who runs the company and who owns it becomes a live tension rather than a footnote.
Quick Questions
Why is McCormick listing in London if it is a US company? To accommodate the shareholders it inherits from Unilever. The Reverse Morris Trust structure leaves former Unilever investors owning about 65% of the combined company, and many of them hold London-listed stock. A secondary London listing lets them stay invested without moving to a US exchange.
Who controls the combined company? McCormick’s management, led by CEO Brendan Foley, runs operations. Ownership is a different story. Former Unilever shareholders hold roughly 65% of the equity, and McCormick’s own shareholders hold about 35%.
What does McCormick gain from the deal? Scale. The merger roughly triples McCormick’s size and adds major brands like Knorr and Hellmann’s, plus a large food-service and international footprint. The cost is around $15 billion in new debt and the loss of its focused, high-margin profile.
Why did both stocks fall when the deal was announced? McCormick investors worried about the debt and the shift away from a focused spice business. Unilever investors were reluctant to end up holding shares in a large US food company. The deal’s structure created discomfort on both sides.
When does the deal close? The companies expect it to complete by mid-2027, subject to regulatory approvals and shareholder votes.
The Business Model Analyst Take
Strip away the “flavor powerhouse” language and this is a story about focus and who pays for scale. Unilever is the winner in plain sight. It sheds a slow business, sharpens its identity, and pockets $15.7 billion in cash. McCormick is the harder case. It gains size and loses the exact quality that made it a premium company, and it borrows heavily to do so.
The London listing and the Netherlands headquarters read as generous corporate housekeeping until you notice what they reveal. McCormick is reshaping its stock, its domicile signals, and its governance around owners who arrived through a tax maneuver. Management got the keys to a much bigger company. Ownership got handed to someone else. Whether that arrangement produces a durable flavor giant or a slow-moving, indebted one depends on integration that has not started and growth in a category that its previous owner gave up on. We will know by mid-2027 which read was right.