
Private equity spent nine years scaling the company that makes Starbucks-style syrups and Oatly cartons. The exit multiple says the growth never turned into pricing power.
Truelink Capital completed its acquisition of Lyons Magnus on July 20, 2026, buying the Fresno ingredients maker from Paine Schwartz Partners in a deal valued at roughly $1 billion including debt. Lyons generates over $1 billion in annual revenue. That is about 1x sales, roughly half the multiple paid for Tate & Lyle weeks earlier.
There is a version of this story where a 174-year-old company selling for a billion dollars is a success. Paine Schwartz bought Lyons Magnus from the Smittcamp family in 2017, bolted on acquisitions, pushed into aseptic manufacturing and healthcare nutrition, and nearly doubled annual revenue. Then it sold the whole thing for approximately what the company books in a single year of sales. In the same sector, in the same quarter, buyers paid far more per dollar of revenue for businesses growing slower. The gap is not a market timing accident. It is a verdict on what kind of business Lyons Magnus actually is.
What Happened
Truelink Capital, a Los Angeles midmarket private equity firm focused on business services and industrials, announced on July 20 that it had completed the purchase of Lyons Magnus from Paine Schwartz Partners. Financial terms were not disclosed in the release, but people familiar with the transaction told The Wall Street Journal the deal valued the business at around $1 billion including debt.
Lyons Magnus was founded in 1852 and is headquartered in Fresno, California. It is a B2B formulator and manufacturer, not a consumer brand. Its portfolio spans coffee syrups and sauces, beverage bases and concentrates, refreshers, smoothie bases, ice cream toppings and specialty healthcare nutrition products. Customers sit in the coffeehouse, QSR, foodservice and healthcare channels.
Truelink raised $2 billion for its second fund in March 2026 and has been deploying it quickly, adding industrial supplier Horwitz alongside several subsidiary-level acquisitions in construction and manufacturing. Lyons is the food platform in a portfolio otherwise weighted toward construction and chemicals, including Zep and Trulite.
The Backstory
Paine Schwartz took its position in Lyons Magnus in November 2017, buying from Robert Smittcamp, who had run the company for more than 40 years. The firm specializes in what it calls sustainable food chain investing, with portfolio companies including cold-pressed juice maker Suja Life and plant-based dough producer Urban Farmer.
The playbook was standard platform-and-bolt-on. Lyons acquired TRU Aseptics of Beloit, Wisconsin in 2019, a specialist in low-acid aseptic processing for plant-based milks, protein shakes and cold-brew coffee. It later picked up operations from Hormel Foods. The strategy pushed Lyons out of fruit purees and into shelf-stable ready-to-drink manufacturing, a genuinely higher-growth category.
Then July 2022 happened. Lyons recalled 53 nutritional and beverage products over potential microbial contamination, including Cronobacter sakazakii and Clostridium botulinum, after products failed to meet commercial sterility specifications. Within two weeks the recall expanded well past 100 SKUs. The brands on the list were not Lyons brands. They were Oatly, Premier Protein, Stumptown, Intelligentsia, Glucerna, Kate Farms and Aloha. In January 2023, the FDA issued a warning letter over the Beloit facility, citing non-compliance with low-acid canned food regulations and flagging that Lyons had sat on positive internal lab results before notifying regulators.
The plant that was supposed to be the growth engine became the liability.
The Plan
Truelink’s stated approach is accelerating growth through strategic initiatives and transformative add-on acquisitions, which is the same platform logic Paine Schwartz ran. The bet is that Lyons has been rebuilt operationally since 2023 and that a buyer paying 1x sales is buying a repaired asset at a broken-asset price.
The logic holds if two things are true. First, that the aseptic and healthcare nutrition capacity is now clean and recertified, which converts the 2022 wound into a discount rather than a defect. Second, that coffeehouse and QSR demand for syrups, refreshers and cold-brew bases keeps compounding while Lyons owns hard-to-replicate manufacturing capacity. Aseptic lines are capital-intensive and slow to build. Scarcity of capacity is a real moat, just a different one from brand.
Truelink also gets an obvious lever Paine Schwartz never pulled hard: margin. At an EBITDA multiple in line with what CVC paid for IFF’s food ingredients unit, roughly 10x, a $1 billion enterprise value implies something near $100 million of EBITDA on $1 billion of revenue. Call it a 10% margin. Tate & Lyle runs at 21%. IFF’s divested unit at 14%. Every point Truelink adds is worth roughly $100 million of enterprise value at constant multiples.
The Business Model Angle
Here is the structural problem, and it has nothing to do with coffee.
Lyons Magnus is a contract manufacturer that sells through other companies’ brands. When you drink an Oatly Barista Edition, the value you assign to that carton belongs to Oatly. When something goes wrong inside the carton, the liability, the recall cost, the FDA warning letter and the customer churn all land on Lyons. That is the worst side of the white label trade: you absorb the downside of a brand you do not own.
Compare that to the specialty ingredients businesses that priced higher this year. Tate & Lyle brings close to 1,000 patents and sells sugar-reduction and mouthfeel systems that customers cannot easily reformulate away from. IFF’s food ingredients unit leads in texturants and emulsifiers. Those are IP businesses wearing manufacturing clothes. Their customers are switching-cost captives. Lyons’ customers are not. A coffee chain can move its syrup contract on a renewal cycle.
This is the same asymmetry Starbucks sits on the winning side of. Starbucks captures a $6 price point on inputs that cost cents, because the brand and the store experience carry the pricing power, not the syrup. Read across the Starbucks value chain and the syrup supplier is an interchangeable inbound-logistics line item. That is precisely why Lyons clears 1x sales while its customers trade at many multiples of it.
The lesson generalizes past food. Scale in a private-label or contract-manufacturing model buys you volume, not margin. Trader Joe’s shows the other side of the same coin: the retailer owning the private label captures the economics, while the manufacturer behind it stays anonymous and replaceable. Revenue growth is a vanity metric in this structure. Paine Schwartz proved it, doubling the topline over nine years and exiting at a multiple that suggests the market saw very little durable value created.
The Risk
Truelink’s discount could be a value trap. Three reasons.
Customer concentration in foodservice cuts both ways. Winning a national coffeehouse chain adds enormous revenue and enormous fragility. One lost contract at 10% margins wipes out years of bolt-on gains.
Food safety is a recurring, not one-time, exposure. Aseptic manufacturing failures are systemic, not accidental. The 2022 root cause was sterility validation and seal integrity at high line speeds, meaning the risk scales with the exact throughput Truelink needs to add.
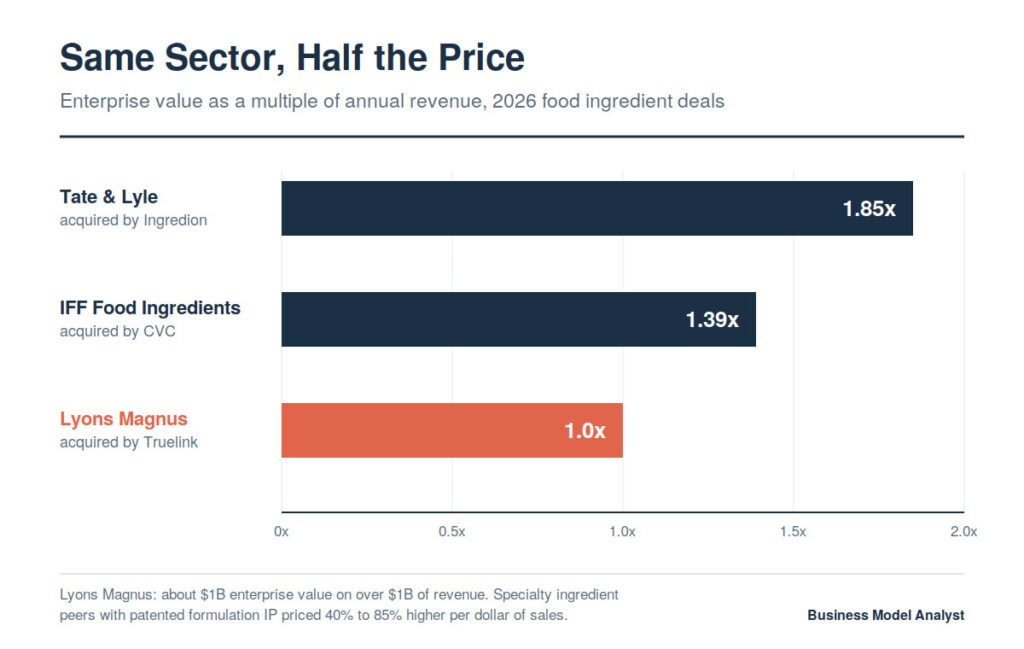
And the exit math is unforgiving. Truelink is buying at roughly 1x sales in a sector where two strategic buyers just paid 1.4x and 1.85x. To generate a private equity return, Truelink either re-rates the business toward those multiples, which requires proving pricing power Lyons has never demonstrated, or grinds out margin expansion in a channel where the customer holds the leverage. Paine Schwartz had nine years and did not manage the re-rate.
Quick Questions
What does Lyons Magnus actually make? Coffee syrups and sauces, beverage bases, concentrates, smoothie bases, refreshers, ice cream toppings and healthcare nutrition products. It sells B2B to coffeehouses, QSR chains, foodservice distributors and healthcare institutions rather than to consumers.
How much did Truelink pay for Lyons Magnus? Terms were not disclosed in the announcement. People familiar with the deal told The Wall Street Journal it valued the business at around $1 billion including debt, against annual revenue of over $1 billion.
Why is 1x sales considered low? Two comparable 2026 ingredient deals cleared far higher. CVC valued IFF’s food ingredients business at $4.3 billion on $3.1 billion of sales, about 1.39x. Ingredion’s Tate & Lyle deal implies roughly $5 billion of enterprise value on $2.7 billion of revenue, about 1.85x.
Was Lyons Magnus involved in a recall? Yes. In July 2022 it recalled 53 nutritional and beverage products for potential microbial contamination, later expanding past 100 SKUs across brands including Oatly, Premier Protein, Stumptown and Glucerna. The FDA issued a warning letter over its Wisconsin aseptic facility in January 2023.
Who owned Lyons Magnus before? Paine Schwartz Partners acquired it from the Smittcamp family in 2017. The family had run the business for more than four decades.
The Business Model Analyst Take
The number to remember is not $1 billion. It is 1x.
Paine Schwartz executed the roll-up correctly. It bought a founder-owned business, added aseptic capacity, entered healthcare nutrition, and nearly doubled revenue in nine years. Judged on operational execution, that is a competent hold. Judged on value creation, it is close to a flat outcome, because the model it was scaling has no mechanism for converting volume into pricing power.
That is the durable lesson for anyone building a B2B manufacturing business. Ask where the pricing power sits in your value chain before you spend a decade adding capacity to your side of it. If your customer owns the brand, sets the spec and can requalify a competitor at contract renewal, you are not building a moat. You are building a cost center that someone else’s brand rents.
Truelink is buying at a price that already assumes this. That is the honest read: the discount is not mispricing, it is the market correctly valuing a business with revenue but no leverage. Truelink’s return depends on changing what Lyons Magnus is, not on running it better. Nine years of evidence says that is the hard part.