
The LVMH SWOT analysis examines the strengths, weaknesses, opportunities, and threats facing the world’s largest luxury group as it exits the post-pandemic boom and settles into a slower, more normal market. LVMH Moët Hennessy Louis Vuitton owns more than 75 maisons across fashion, leather goods, wines and spirits, perfumes, watches, jewelry, and retail. In 2025 it posted revenue of EUR 80.8 billion, a slight decline that says less about the business than the headline suggests. This analysis breaks down where the group is strong, where it is exposed, and what a skeptic should watch in 2026.
What is LVMH? LVMH Moët Hennessy Louis Vuitton SE is a French luxury conglomerate founded in 1987 through the merger of Louis Vuitton and Moët Hennessy. Chaired by Bernard Arnault, it operates five business groups: Fashion & Leather Goods (Louis Vuitton, Dior, Loro Piana, Celine, Fendi, Loewe), Wines & Spirits (Moët & Chandon, Hennessy, Dom Pérignon), Perfumes & Cosmetics (Parfums Christian Dior, Guerlain), Watches & Jewelry (Tiffany, Bulgari, TAG Heuer), and Selective Retailing (Sephora, DFS). It is Europe’s most valuable listed company and France’s largest private employer.
LVMH at a glance (FY2025)
| Metric | FY2025 | Change vs FY2024 |
|---|---|---|
| Revenue | EUR 80.8bn | -5% reported, -1% organic |
| Profit from recurring operations | EUR 17.8bn | -9% |
| Operating margin | 22.0% | down from 23.1% |
| Net profit (Group share) | EUR 10.9bn | -13% |
| Free cash flow | EUR 11.3bn | +8% |
| Net debt | EUR 6.9bn | down from EUR 9.2bn |
| Dividend per share | EUR 13.00 | unchanged |
| Employees | 211,000+ | – |
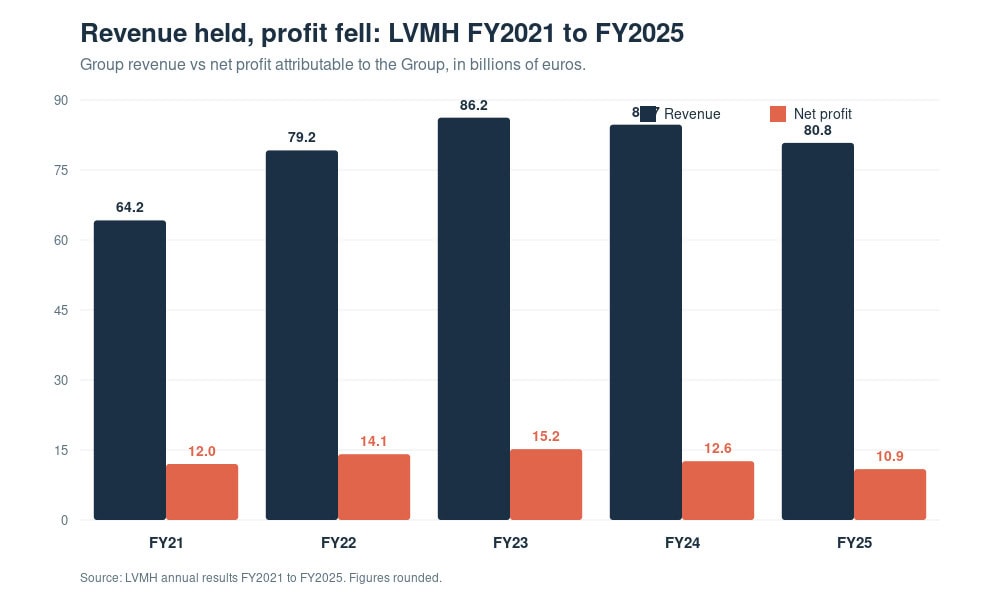
The single most important line in that table is not the revenue drop. It is the split between reported and organic. Most of the 5% fall came from currency, not from customers buying less. Strip out the foreign exchange effect and demand fell about 1%. LVMH did not have a bad year. It had a flat year that the euro made look worse.
Strengths
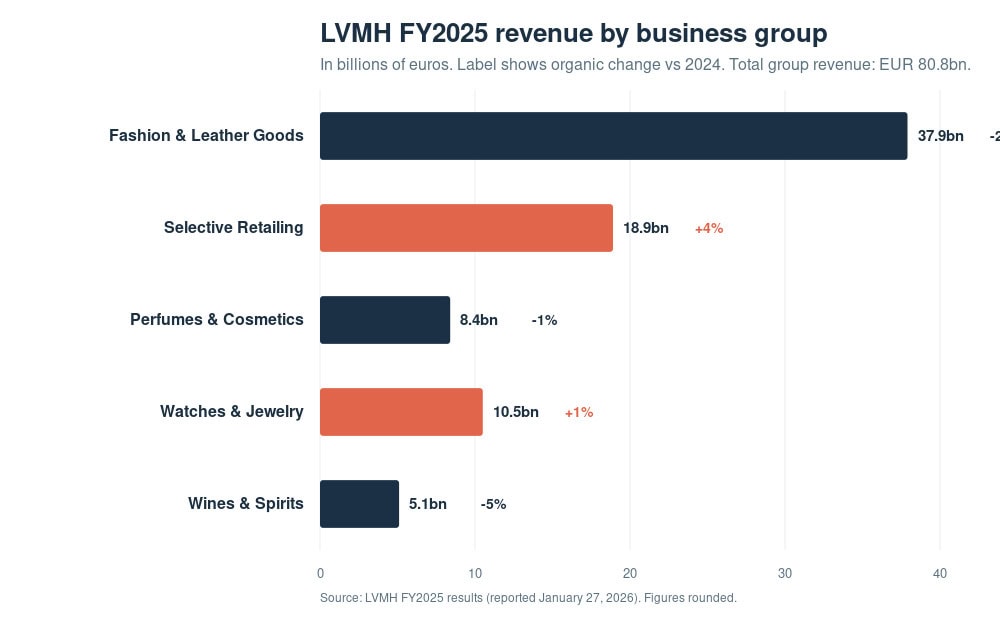
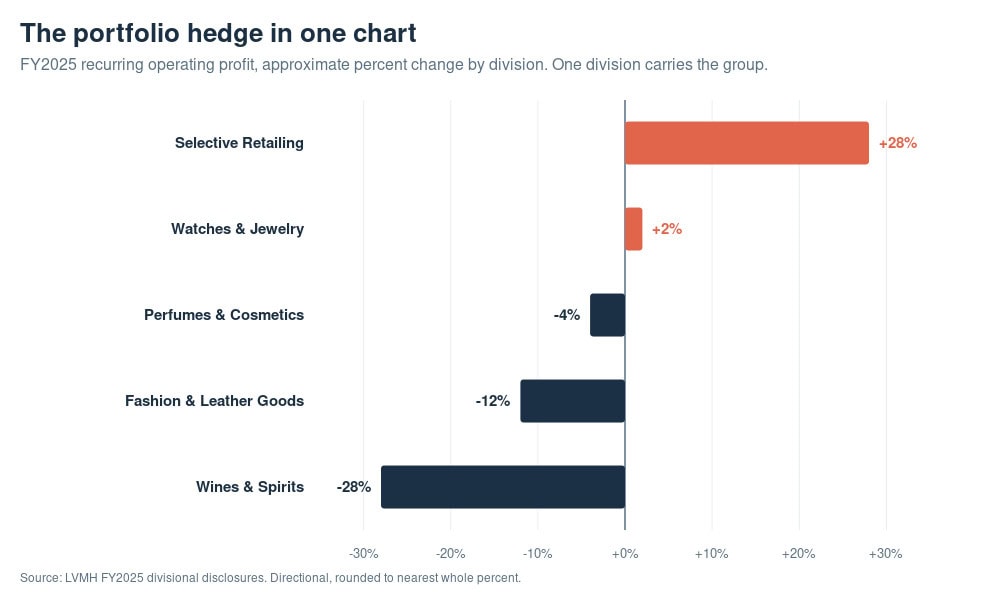
A portfolio that absorbs shocks. LVMH runs more than 75 brands across five groups, and in a soft year the spread does its job. When Fashion & Leather Goods and Wines & Spirits slipped in 2025, Selective Retailing grew organic revenue 4% and lifted recurring profit 28% to EUR 1.8 billion. No pure-play rival has this hedge. Hermès is one house. Kering leans on Gucci. LVMH loses a division and keeps moving.
Sephora is a growth engine hiding inside a hard-luxury group. Sephora opened roughly 100 stores in 2025 and held its spot as the world’s leading beauty retailer, taking share while the handbag business cooled. Beauty sells at lower prices and higher frequency than a EUR 5,000 bag, which gives LVMH a stream of repeat, aspirational buyers that the core maisons cannot reach on their own.
A balance sheet that turns downturns into opportunities. Net debt fell from EUR 9.2 billion to EUR 6.9 billion, and free cash flow rose 8% to EUR 11.3 billion even in a down year. This is why the dividend held at EUR 13. It is also why LVMH can buy weakened competitors when everyone else is retrenching. Cash flow that grows while revenue falls is the mark of a business with real pricing discipline.
Louis Vuitton and Dior can raise prices through a downturn. Fashion & Leather Goods, led by these two houses, remained the group’s profit engine in 2025. The pair sit in the narrow band of luxury brands that can push prices in a weak market without losing their core buyer. That pricing power is what holds the group margin at 22% when volumes soften.
Vertical control competitors cannot copy quickly. LVMH runs 117 production plants and workshops in France alone and keeps pushing certified sourcing higher across cotton, wool, and grapes. Owning the supply chain protects both margin and the craftsmanship story that justifies the prices.
Weaknesses
The profit engine is also the biggest exposure. Fashion & Leather Goods is the group’s cash cow and its concentration risk in the same breath. In the first half of 2025, the division’s revenue fell 8% and its recurring profit dropped 18% to EUR 6.6 billion. When Louis Vuitton and Dior slow, the whole group feels it, and no other division is large enough to fill the gap.
Here is the tension worth sitting with. That concentration is also why the margin is 22% and not 12%. Diversifying away from Vuitton and Dior would dilute the very thing that makes LVMH the most profitable name in luxury. The weakness and the moat are the same fact.
Wines & Spirits has a demand problem, not a cycle problem. The division was the worst performer in 2025, with revenue down 5% organic, dragged by weak cognac demand in the United States and Asia. Champagne held up. Cognac faces a harder question about whether the next generation of drinkers shows up at all. That is structural, and price cuts will not fix it.
Succession is undefined, and the market has noticed. Bernard Arnault is 76 and told investors at the end of 2025 to “see you in ten years.” Shareholders pushed back at the January 2026 results, calling the lack of a named successor a governance risk. Baillie Gifford abstained from the vote to extend his age cap to 85, and Allianz Global Investors opposed it outright. All five Arnault children hold senior roles, but no heir is named. For a group this dependent on one person’s judgment, that is a real vulnerability, not a headline.
Currency turns steady demand into ugly optics. Foreign exchange knocked about three points off 2025 revenue. Most of the reported decline was the euro moving against the dollar and yen, not customers leaving. LVMH cannot control this, and it means reported earnings will keep swinging on things management does not steer.
Opportunities
The demand base is rebalancing toward the US and Europe. LVMH’s growth is shifting away from a heavy reliance on Asia toward a more even spread across the United States and Europe. A less China-dependent revenue base is a healthier one. Arnault’s four-decade relationship with the Trump family adds a diplomatic edge in the US market, which matters more now that Tiffany is fully integrated.
Tiffany and hard luxury have room to run. The revamped Tiffany stores are landing, and Watches & Jewelry grew organically in 2025 while softer categories fell. Jewelry holds value in downturns better than seasonal fashion, and Tiffany still has margin to recover toward Bulgari’s level.
Beauty and Sephora can stretch further. LVMH’s stated 2026 plan leans on experiential retail and category expansion in beauty and high-value segments. Sephora gives it a distribution network rivals cannot match, and beauty brings in younger buyers who may trade up to the core maisons over time.
A soft market is LVMH’s acquisition window. The group’s historical playbook is to buy when others are weak. With EUR 11.3 billion in free cash flow and falling debt, LVMH has the firepower to pick off struggling independents while private-equity buyers sit on the sidelines.
Threats
Luxury normalisation may last longer than one year. If the aspirational middle-class buyer stays cautious, the whole sector’s volume base shrinks. Arnault himself called 2026 an environment that “remains uncertain.” A group built for a growing market has to prove it can hold margin in a flat one.
China demand is fragile. Even with the US and Europe rebalancing, Asia outside Japan is still large. A deeper Chinese consumer retrenchment would hit LVMH and every luxury peer hard, and the timing is not in anyone’s control.
Tariffs and currency add noise on top of demand. The 2025 results landed in what LVMH called a disrupted geopolitical and economic environment. US tariff policy, FX swings, and softer tourist flows all pull at reported numbers regardless of how the maisons perform.
Creative transitions can misfire. LVMH is mid-way through designer changes at Louis Vuitton, Dior, and Loro Piana. Handled well, a new creative director reignites desirability. Handled badly, it stalls a EUR 38 billion division. Kering’s Gucci troubles show how fast a mishandled creative reset can bleed a flagship. The same risk applies here, and at LVMH’s scale the stakes are larger.
LVMH vs the field
LVMH’s diversification looks best when you hold it against its rivals. Kering’s fortunes rise and fall with Gucci, a single-brand dependence that has punished it through Gucci’s slump. Hermès takes the opposite approach, one house with famously tight supply and the steadiest margins in the industry, but no portfolio hedge and a deliberate cap on how fast it can grow. LVMH sits between them: broad enough to absorb a bad division, big enough to buy its way into new categories, and exposed enough to Vuitton and Dior that a stumble there still matters. For deeper reads on the field, see our Gucci SWOT analysis, Hermès SWOT analysis, and Chanel SWOT analysis.
Frequently asked questions
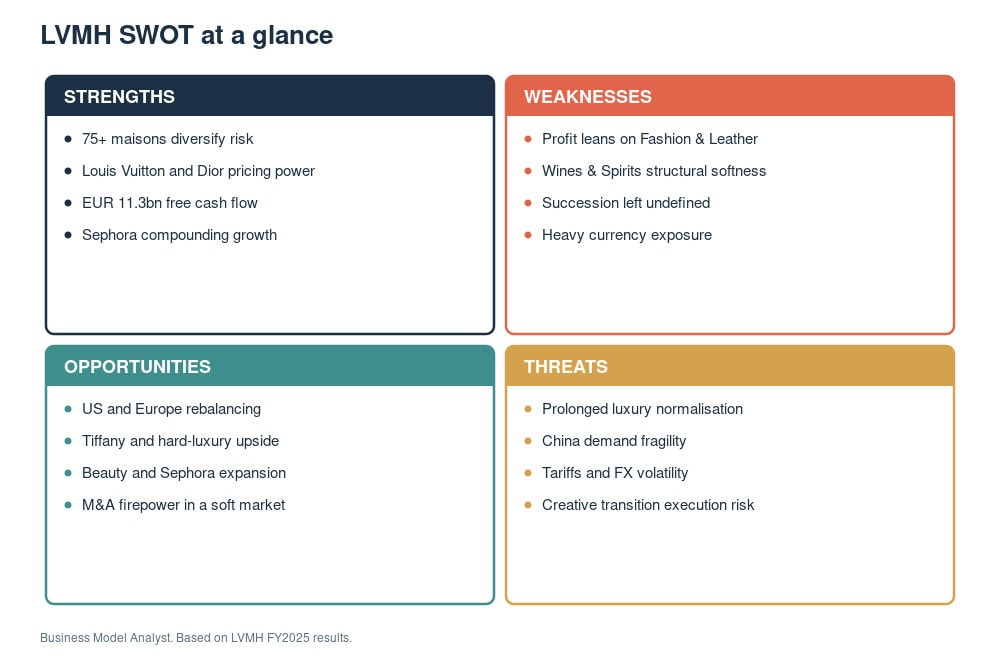
What are LVMH’s biggest strengths? Its diversified portfolio of 75+ brands, the pricing power of Louis Vuitton and Dior, strong free cash flow of EUR 11.3 billion, and Sephora’s continued growth as the world’s leading beauty retailer.
What is LVMH’s biggest weakness? Concentration. Fashion & Leather Goods drives most of the group’s profit, so any slowdown at Louis Vuitton or Dior hits the whole company. The unresolved succession question is a close second.
Did LVMH’s revenue really fall in 2025? Reported revenue fell 5% to EUR 80.8 billion, but most of that was currency. On an organic basis, revenue fell about 1%, so underlying demand was close to flat rather than collapsing.
Who will succeed Bernard Arnault? No successor has been named. All five of Arnault’s children hold senior roles across the group, and Arnault, at 76, has said he intends to lead for years yet. Investors have flagged the lack of a clear plan as a governance risk.
How does LVMH compare to Hermès and Kering? LVMH is the most diversified of the three. Hermès runs a single high-margin house with capped growth, and Kering depends heavily on Gucci. LVMH’s spread protects it in downturns but leaves it exposed to its two flagship fashion brands.
The Business Model Analyst Take
The number that will get quoted from LVMH’s 2025 results is the 5% revenue drop. Ignore it. The real figure is minus 1% organic, which tells you demand barely moved and the euro did the rest. A group this size holding flat through a luxury correction, while lifting free cash flow 8% and cutting debt, is not a business in trouble. It is a business proving its pricing discipline in the exact conditions that expose weaker names.
The genuine risk is not on the income statement. It is the empty chair. LVMH runs on Bernard Arnault’s judgment, and at 76 he has named no successor and told shareholders to check back in a decade. The financials are predictable. The transition is not, and it carries more variance than any tariff or currency swing. The contrarian read is that the succession noise is theatre: Antoine Arnault joined the executive committee in early 2026, the holding structure was engineered years ago, and the family control is locked tight. That may be right. But “trust us, it is handled” is a thin answer for the most valuable company in Europe, and the investors abstaining from that age-cap vote were not being unreasonable.
Watch two things in 2026. First, whether the creative resets at Louis Vuitton and Dior land, because that is where the margin lives. Second, whether Arnault gives the market any real signal on succession. The business will be fine. The question is who runs it next, and for now the most powerful man in luxury is not saying.