
The world’s most coveted status symbol is losing its grip, and shoppers are voting with their wallets, on resale apps instead of in boutiques.
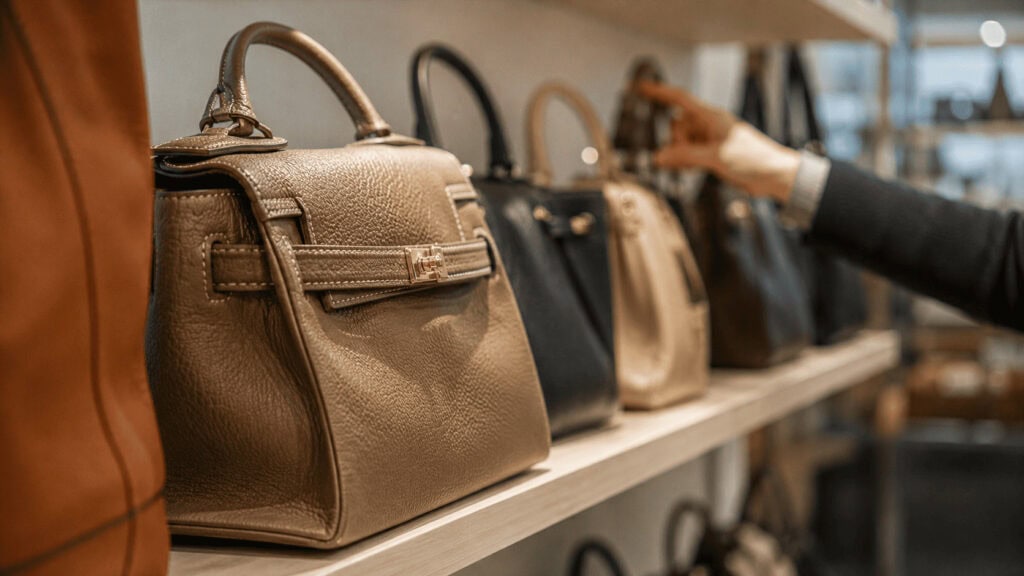
Luxury handbag sales have fallen almost 10% from their 2023 peak, a roughly $8 billion hole, as shoppers chase vintage and resale instead of pricey new designs. Bain data shows the slump, while The RealReal reports vintage bag searches jumped 131% in a single year. The It-bag isn’t dead. It’s just changing hands.
Picture the early 2020s. Brands were minting money, raising prices like clockwork, and shoppers kept buying anyway. The waitlist was the flex. Then the music slowed. The bags that once felt impossibly rare started showing up everywhere on social feeds, and the spell began to crack. Now the hottest bag in fashion might be one that’s already a decade old.
What Happened
Sales of luxury handbags are down almost 10% from their 2023 peaks, according to Bain & Company. That works out to roughly $8 billion in annual spending that has simply vanished from designer stores.
The shoppers didn’t disappear. They moved. Sales of luxury handbags on resale platform The RealReal are up 20% since 2023. In May, searches for vintage bags on the site were up 131% versus the same month a year earlier. Rental and resale platforms like Vivrelle are seeing a surge of social content about cheaper ways to access luxury, per analysis from Traackr.
The bigger surprise: this isn’t only about price. Carrying a vintage bag is becoming cooler than buying new.
The Backstory
There’s a useful history lesson here, and it involves pineapples. In the 17th century, pineapples were so rare they functioned like the era’s Birkin. Then supply rose, the middle class could afford them, and they instantly lost their power to impress.
Luxury brands now face the same question shareholders are asking: are handbags more like a mansion, which never stops signaling wealth, or more like a pineapple?
Part of the problem is brands’ own doing. They jacked up prices aggressively during the pandemic, annoying loyal buyers. They also pumped out fewer fresh ideas, releasing 80% fewer new bags between 2023 and 2025 than they did between 2016 and 2019, Bain found. And the relentless flood of Birkins and Classic Flaps across social media did the rest.
As Bernstein luxury analyst Luca Solca puts it, brands are selling the promise of exclusivity, and anything that creates too much visibility works against that promise.
The Plan
The industry’s bet is that innovation pulls shoppers back, and there’s one loud proof point: Chanel.
The privately owned brand hired designer Matthieu Blazy to overhaul its lineup, and the response has been ferocious. Shoppers have stripped shelves bare, and sold-out models are fetching steep premiums on resale sites. Today, 74% of Chanel’s handbag offering is brand new, according to Bernstein. The takeaway is blunt: desire for a new luxury bag is still intense when the design is actually right.
Brands have escaped a handbag funk before. Back in 2015, purse sales stalled because customers got sick of heavily logoed looks. A burst of fresh design fixed it and delivered years of strong returns.
The Business Model Angle
Here’s why luxury houses are sweating. Handbags are the profit engine, and a remarkably concentrated one.
| Brand | Share of sales from handbags / leather goods |
|---|---|
| Hermès | 44% of group sales (Birkin, Kelly and similar) |
| Saint Laurent | 65% of total sales |
| Bottega Veneta | 77% of total sales |
Bags are also the perfect retail product. They lift revenue per square foot, which matters enormously when you pay the highest store rents in the world. They recruit new customers, since a designer purse is often someone’s first luxury buy. And because they don’t have sizing issues like shoes or clothing, they rarely go on sale, which protects margins.
That concentration is the strategic lesson. When one hero category carries this much of your revenue, a shift in taste isn’t a dent, it’s a structural threat. The pattern is classic disruption from below: the secondhand market isn’t competing on the same axis (newness), it’s redefining what “cool” means (heritage, scarcity, knowing your fashion history). Brands now have to treat their own back catalog as their biggest competitor.
The Risk
The optimistic read could be wrong. If the move toward buying pre-owned and vintage genuinely sticks, the math gets ugly fast, because It-bags have been the industry’s bread and butter since the 1990s.
The stock market is already nervous. Shares of LVMH, Kering and Hermès, the groups most exposed to handbags, are down 27% on average since the start of 2024.
The counterargument, though, is real. The underlying hunger for status hasn’t faded. Younger shoppers are arguably more image-conscious than ever, precisely because of social media. They still want to broadcast signals of status. The open question, as one professor frames it, is simply what they’re now willing to buy new. Get that answer right, and the funk lifts. Get it wrong, and the resale market keeps eating your lunch.
Quick Questions
Are luxury handbag sales actually falling?
Yes. Bain & Company data shows sales down nearly 10% from their 2023 peak, a drop of roughly $8 billion in annual spending.
Why is everyone buying vintage bags now?
Two reasons. They’re cheaper through resale, and they’ve become a status signal of their own. Buying vintage suggests you know fashion history, and it helps you stand out in an era of algorithm-driven trends.
Is any brand still winning at new bags?
Chanel. After hiring designer Matthieu Blazy, its new designs are selling out and trading at premiums on resale sites. Roughly 74% of its current handbag lineup is new.
Should I worry about luxury stocks?
That’s your call, not investment advice, but the numbers are stark: LVMH, Kering and Hermès are down about 27% on average since early 2024, and the rebound depends entirely on what shoppers want next.
The Business Model Analyst Take
When your most profitable product becomes too visible, exclusivity quietly evaporates, and the secondhand market is happy to capture the value you leave behind. The lesson for any premium brand: scarcity is a feature you have to actively defend, not a moat that holds itself. Treat your past success as your sharpest competitor, or someone on a resale app will.