
What it is: A Lululemon value chain analysis applies Michael Porter’s framework to the company’s primary and support activities, then traces where the money is made and where the risk actually sits.
The key takeaway: Lululemon owns the two ends of its chain and rents everything in the middle. It runs no factories and no mills, and its own 10-K says suppliers own the intellectual property in its fabrics. What it does own is heavy: 811 stores, 2.9 million square feet of open distribution space, and 39,000 employees. Seventy percent of that warehouse space sits in Canada, laid out for a customs rule that no longer exists. When tariffs hit in 2025 and 2026, there was no wholesale partner to share the pain with and no owned plant to squeeze, so the whole shock landed on the two nodes Lululemon paid for.
Most breakdowns of Lululemon’s supply chain stop at “vertically integrated direct-to-consumer” and move on. That phrase describes the selling end and hides the sourcing end, where Lululemon looks less integrated than almost anyone in the category. This analysis uses the fiscal 2025 Form 10-K covering the year ended February 1, 2026, and the first-quarter fiscal 2026 results reported on June 4, 2026, so the numbers describe the company as it stands going into the Heidi O’Neill era rather than the 2021 version still circulating online.
What a value chain analysis measures
Porter split a company into two groups of activities in Competitive Advantage (1985). Primary activities move a product from raw material to customer: inbound logistics, operations, outbound logistics, marketing and sales, and service. Support activities make those possible: procurement, technology development, human resource management, and firm infrastructure.
The useful question is never “what are the activities.” It is which links a company owns, which it rents, and what happens to margin when costs move. You can see the same exercise run on a wholesale-led business in our Nike value chain analysis, and across other brands in our companies value chain analysis library.
The shape of Lululemon’s chain
Here is the ownership map, node by node, drawn from what the company discloses about itself.
| Link in the chain | Who owns it | Lululemon’s disclosed position |
|---|---|---|
| Fiber and yarn | Third parties | Not disclosed; sourced through mills |
| Fabric and trims | ~65 outside suppliers | Top 5 make 48% of fabric; largest makes 20% |
| Fabric intellectual property | Suppliers | 10-K states suppliers own or control it and it is not unique to Lululemon |
| Garment assembly | ~51 outside vendors | Top 5 make 47% of product; largest makes 15% |
| Testing and inspection | Third-party firms | Independent inspection and verification companies run fabric tests |
| Distribution centers | Mixed | Owns one (Groveport, Ohio); leases seven |
| Stores | Lululemon | 811 company-operated stores plus 58 outlets |
| E-commerce | Lululemon | Digital was 40% of first-quarter fiscal 2026 revenue |
| Wholesale | Minimal by design | Studios, corporate sales, campus retailers only |
| Brand | Lululemon | Trademarks and trade secrets; the 10-K describes its patent position as limited |
Two links carry the whole business: the specification written in Vancouver and the store where a customer hands over money. Everything between them belongs to somebody else, and Lululemon has no long-term contracts with most of those somebodies. That structure produced spectacular returns for fifteen years because every extra dollar of demand landed straight on an owned, high-margin node without any capital going into looms. It also means a cost shock in the middle has nowhere to go.
Primary activity 1: inbound logistics and materials
Lululemon works with roughly 65 fabric suppliers. Its top five make 48% of the cloth, and a single mill makes 20% of it. For a brand whose entire premium rests on how a legging feels against skin, one supplier controlling a fifth of the fabric is a real dependency.
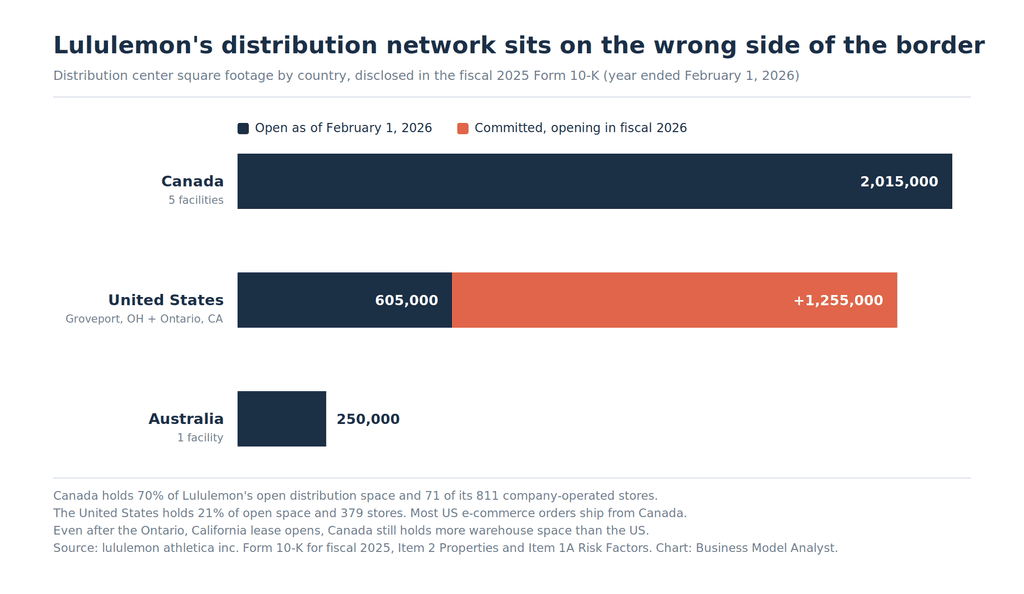
The geography matters more than most write-ups admit. During fiscal 2025, 34% of fabric came from Taiwan, 29% from China Mainland, 10% from South Korea, and 10% from Vietnam. Lululemon’s own risk factors name the Taiwan concentration as a geopolitical exposure, which is unusual candor for an apparel filing.
Then there is the disclosure that undercuts the most repeated claim about this company. Lululemon states in its risk factors that the intellectual property in the technology, fabrics, and processes behind its products is owned or controlled by its suppliers, and that it is not unique to Lululemon. Luon, Nulu, Everlux and the rest are trademarks and trade secrets protected by contract. They are not patents on textiles. The mill that makes Lululemon’s signature knit can make a close cousin for anyone else who calls.
That single sentence explains the “dupe” problem better than any commentary about Gen Z shopping habits. Lululemon added a dedicated dupe risk factor to the fiscal 2025 filing for the first time, warning that if shoppers stop seeing a gap between its product and cheaper alternatives, the price premium goes with it. Alo Yoga and Vuori did not crack a patent. They ordered from the same kind of mill. Our Lululemon SWOT analysis covers the competitive fallout; the point here is that the vulnerability is structural, written into where the IP sits.
Primary activity 2: operations
Lululemon owns no manufacturing facilities. About 51 outside vendors assemble its products, with the top five accounting for 47% and the largest at 15%.
Country concentration is where Lululemon diverges from its usual comparison set. Five countries produced 87% of its output in fiscal 2025: Vietnam at 40%, Cambodia 18%, Sri Lanka 11%, Indonesia 11%, and Bangladesh 7%. Nike, by contrast, spreads finished apparel across 321 factories in 34 countries.
The more telling difference is the relationship between cloth and stitching. Nike says its contract manufacturers buy their principal materials in the countries where assembly happens. Lululemon’s map does not work that way. Northeast Asia mills 73% of the fabric; South and Southeast Asia sew 87% of the garments. Vietnam is the only country appearing meaningfully on both lists. A typical Lululemon garment therefore crosses at least two international borders before it reaches a warehouse, and for most US online orders it crosses a third.
Each crossing is a customs event, a freight bill, and a week of lead time.
Primary activity 3: outbound logistics, and the border problem
This is the link where Lululemon put its own capital, and it is the link that broke.
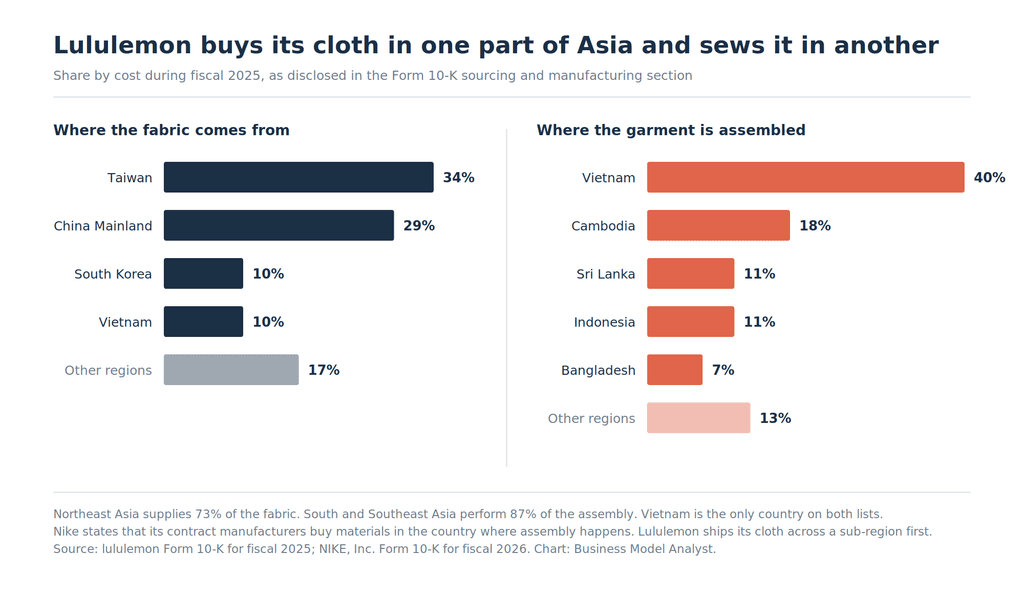
As of February 1, 2026, Lululemon disclosed eight distribution facilities. Five sit in Canada and hold 2,015,000 square feet. One sits in the United States, the 605,000 square foot Groveport, Ohio building, the only distribution center the company owns outright. One sits in Australia. Canada therefore holds 70% of Lululemon’s open warehouse space while housing 71 of its 811 stores. The United States holds 21% of the space and 379 stores.
That looks like an error until you remember why it was built. Lululemon’s 10-K states that most of its sales to US e-commerce customers get fulfilled from Canadian distribution centers, and that a large share of those parcels historically qualified for the de minimis exemption, entering the United States duty free under the $800 threshold. Shipping from Brampton to Boston was cheaper than shipping from Ohio to Boston, because the parcel skipped duty on the way. The Vancouver headquarters gave Lululemon a head start on a customs arbitrage, and the company built its physical footprint around it.
The United States ended de minimis for certain shipments on May 2, 2025, extended the elimination globally from August 29, 2025, and enacted legislation repealing the statutory exemption outright by July 1, 2027. Origin now governs. Asian-made goods sitting in an Ontario warehouse do not become Canadian goods, so they get no USMCA relief when they cross. Overnight, Lululemon’s largest single class of owned and leased operating asset ended up on the wrong side of a tariff wall.
The fix is the 1,255,000 square foot leased facility in Ontario, California, committed through February 2039 and scheduled to open in fiscal 2026. It is the biggest building in the network by a wide margin, and it is a re-domestication of fulfillment rather than a capacity expansion. Even after it opens, Canada will still hold more distribution space than the United States. Fiscal 2026 capital spending of $700 million to $720 million goes largely into that project, new stores, and technology.
Primary activity 4: marketing and sales
Lululemon ended fiscal 2025 with 811 company-operated stores, 58 outlets, and 45 locations run by third parties under license in nine countries. It operates in 30 countries and reports three segments.
| Segment | FY2025 revenue | Change | Share of total |
|---|---|---|---|
| Americas | $7,847.0M | -1.0% | 71% |
| China Mainland | $1,754.8M | +28.9% | 16% |
| Rest of World | $1,500.8M | +15.6% | 13% |
| Total | $11,102.6M | +5% | 100% |
Women’s product made 63% of revenue, men’s 24%, and accessories and other 13%. Digital contributed 40% of first-quarter fiscal 2026 revenue.
The absence of a wholesale channel is the defining feature of this node. Nike ran $27.5 billion through wholesale in fiscal 2026, which means Foot Locker and Dick’s carry a share of Nike’s inventory risk and absorb a share of its markdowns. Lululemon has almost none of that. It takes 100% of the inventory risk on 100% of what it orders, and when a product misses, the clearance happens in its own stores at its own expense.
Store productivity is now moving the wrong way. Sales per square foot fell from $1,574 in fiscal 2024 to $1,426 in fiscal 2025, down 9.4%, while store count rose from 767 to 811. Square footage grew another 11% year over year by the first quarter of fiscal 2026. Lululemon is adding selling space into declining productivity, and the company guides North American revenue to fall by high single digits for the full year. Our Lululemon target market breakdown covers who is walking away and why.
Primary activity 5: service
Service is thin by design. Lululemon runs a Like New re-commerce program that takes gently used product in exchange for store credit and resells it online, plus 58 outlets that clear slow-moving and prior-season inventory. Returns flow back through stores or online into the same distribution pool the company uses for forward shipments, which is one of the arguments for the one-inventory-pool model it has built.
None of this is a profit center. It is a pressure valve on a business that cannot push unsold goods onto a wholesale partner.
Support activities
Procurement. Lululemon has no long-term contracts with most of its suppliers and manufacturing sources, and it competes with other brands for the same fabrics and the same capacity. Buying power exists at scale, but it does not buy relief from a customs duty. The importer of record pays that, and the importer of record is Lululemon.
Technology development. The design team works with suppliers to develop fabrics, and independent inspection and verification companies run the performance testing on pilling, shrinkage, abrasion, and colorfastness. Both the invention and the verification sit outside the company. What Lululemon keeps in-house is the specification and the fit.
Human resources. About 39,000 employees, the large majority of them working in stores. This headcount is the fixed cost that shows up in the margin math below.
Infrastructure. Vancouver headquarters, a store development organization, and a tax structure with an open question in it. The Canada Revenue Agency withdrew from bilateral advance pricing arrangement negotiations with Lululemon and the IRS in October 2025, leaving the company’s transfer pricing between its Canadian and US entities exposed to audit. Its organizational structure sits on top of that arrangement.
Where the margin actually goes
Lululemon includes store and distribution center occupancy inside cost of goods sold, which most readers of the gross margin line do not realize. The company confirmed it on the first-quarter call when it decomposed a 410 basis point gross margin decline into 280 points of tariff and 140 points of fixed cost deleverage. Rent showing up in gross margin means the line most analysts read as product economics is really product plus property.
That is why every shock gets bigger on the way down the income statement.
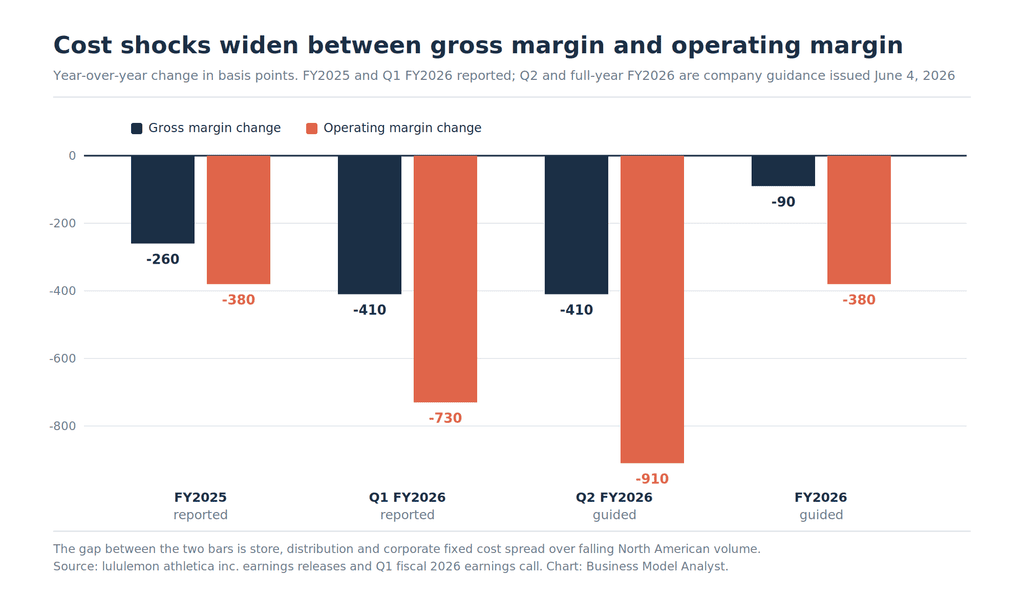
The gap widens because Lululemon owns the last node. Store labor, occupancy, corporate cost and marketing are fixed against a North American revenue base that is shrinking. Full-year guidance calls for 290 basis points of SG&A deleverage on top of the 90 point gross margin decline, which produces an operating margin of roughly 16.1% against 19.9% in fiscal 2025. On guided revenue of $11.0 billion to $11.15 billion, that is about $425 million of operating income gone in a year when revenue is flat.
Diluted earnings per share guidance of $10.95 to $11.15 compares with $13.26 in fiscal 2025 and $14.64 the year before. A $100 investment in Lululemon on January 31, 2021 was worth $53.09 five years later. The same $100 in the S&P 500 was worth $186.82.
The tariff math nobody has run
Lululemon’s fiscal 2026 guidance assumes a 10% incremental tariff rate in the second quarter and 20% in the back half, with no recovery of duties paid under IEEPA. Those assumptions were set on June 4, 2026. The regime changed after that.
The Supreme Court invalidated the IEEPA tariffs on February 20, 2026. The administration replaced them within hours under Section 122 of the Trade Act of 1974, capped at 15% and 150 days. Those expired at midnight on July 23, 2026, and USTR’s Section 301 forced-labor tariffs took effect at 12:01 a.m. the following morning, covering 60 economies at either 10% or 12.5% depending on whether each country has a forced-labor import prohibition in place.
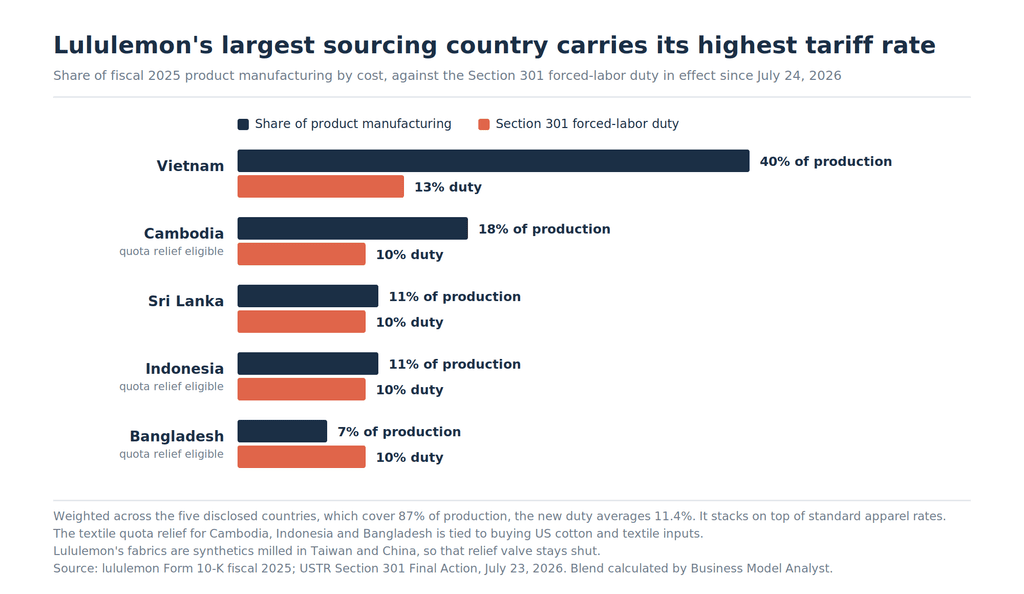
Weighting the new rates by Lululemon’s disclosed sourcing map produces a blended duty of about 11.4% across the five countries that make 87% of its product. The prior IEEPA blend across the same five countries ran about 19.6%. The reciprocal layer on Lululemon’s sourcing base has therefore fallen by roughly eight points against what the company assumed for the second half.
Two wrinkles cut the other way. Vietnam, which makes 40% of Lululemon’s product and more than any other country by a factor of two, landed in the 12.5% tier and pays 13% with stacking, the highest rate in its sourcing base. And the one piece of apparel-specific relief in the package, a textile tariff rate quota for Bangladesh, Cambodia, Indonesia and Malaysia available no earlier than September 1, 2026, ties the reduced rate to each country’s purchases of US cotton and textile inputs. Those three countries cover 36% of Lululemon’s production. Lululemon builds with synthetics milled in Taiwan and China. The relief valve exists and it is shut.
There is also an asset nobody is counting. Duties paid under IEEPA between April 2025 and February 2026 became refundable when the Supreme Court struck the authority down, and Lululemon’s guidance explicitly excludes any recovery. At the first-quarter run rate of 280 basis points of gross tariff impact, the annualized cost sits near $310 million. Whatever portion of the 2025 layer comes back arrives outside plan.
What Heidi O’Neill inherits
Calvin McDonald stepped down effective January 31, 2026. Chip Wilson launched a proxy contest in December, settled it on May 27, 2026 for two board seats and an 18-month standstill, and Heidi O’Neill arrives from Nike in September.
The value chain hands her three decisions that have nothing to do with product.
The first is fulfillment geography. She takes over a network built for a customs rule that expired, with one large correction already committed through 2039 and Canada still holding the larger share of space.
The second is the fabric IP. Owning the specification without owning the textile worked while nobody else could source the same cloth. That window is closed, and closing it again means either buying into a mill, funding exclusive development with real capital, or accepting that the product premium now has to come from fit and brand alone.
The third is the fixed-cost base. Lululemon is opening 40 to 45 stores and growing square footage by low double digits in a year when North American revenue falls by high single digits. Every point of new selling space widens the gap between gross margin and operating margin.
Our Lululemon business model piece covers how the revenue engine is put together. The chain underneath it is the part that needs rebuilding.
Frequently asked questions
Does Lululemon manufacture any of its own products? No. The company states in its 10-K that it does not own or operate any manufacturing facilities. Roughly 51 outside vendors assemble its products and about 65 outside suppliers make its fabric.
Where are Lululemon products made? During fiscal 2025, Vietnam produced 40% of Lululemon’s products by cost, followed by Cambodia at 18%, Sri Lanka at 11%, Indonesia at 11%, and Bangladesh at 7%. The fabric comes from elsewhere: 34% from Taiwan, 29% from China Mainland, 10% from South Korea, and 10% from Vietnam.
Does Lululemon own its fabric technology? Not in the legal sense most people assume. Lululemon’s own risk factors state that suppliers own or control the intellectual property in the technology, fabrics and processes behind its products, and that this IP is not unique to Lululemon. Names like Luon are trademarks backed by contracts and trade secrets rather than textile patents.
Why did tariffs hurt Lululemon more than other apparel brands? Two reasons compound. Lululemon is the importer of record on nearly everything it sells, with almost no wholesale partners to share duty and markdown risk. And most of its US e-commerce orders ship from Canadian warehouses that used to enter duty free under the de minimis exemption, so it lost a routing advantage at the same moment rates went up.
What is Lululemon’s biggest value chain vulnerability? Concentration at the two ends. One mill makes 20% of the fabric, one country assembles 40% of the product, and the store network that carries the entire margin is growing while its sales per square foot falls.
The Business Model Analyst Take
Lululemon spent two decades being praised for a value chain it never had. The vertical integration everyone cites runs one direction only. Downstream, the company owns the stores, the site, the inventory risk and the customer. Upstream it owns a specification document and a set of trademarks, and its own filings say the mills own the rest.
That arrangement is not a flaw. It is the same arrangement that let a Vancouver yoga shop reach $11 billion without ever buying a loom. The flaw is what happens when a cost lands in the rented middle. There is no factory to squeeze, no long-term contract to enforce, no wholesaler to split the bill, and no textile patent to license. So the cost travels straight to the two nodes Lululemon paid for, and then the fixed costs sitting in those nodes amplify it a second time.
The distribution map is the part worth watching. A company built a physical network in the wrong country because a customs threshold made it the cheapest routing, and it will spend the next fifteen years paying rent on the correction. That is the honest lesson of this value chain: an asset optimized for a tax rule is not an asset, it is a bet on the rule.
Heidi O’Neill can fix stores and she can fix product. Whether she buys her way back into the fabric layer will tell you whether Lululemon intends to be a brand that designs clothing or a brand that orders it.