
A Lululemon PESTLE analysis scores the political, economic, social, technological, legal and environmental forces acting on the company from outside. The standard version treats those six as separate buckets and adds them up. For Lululemon in 2026, they are not separate. Political, legal and environmental risk all resolve into the same trade question, and the demand story and the supply story sit in the same corner of the map.
Every competitor page runs the same conclusion. Lululemon sells in 30 countries, sources from five, reports three segments, and grows fastest overseas. Spread that wide and no single shock can hurt you.
That reading fails a basic test. A macro analysis is only useful if the factors move independently. If they move together, six manageable bullets are one large bet written six times, and the diversification is cosmetic.
Score Lululemon’s six factors against each other and the same geography keeps appearing. China Mainland supplied 76% of the company’s net revenue growth in fiscal 2025. China Mainland and Taiwan supply 63% of its fabric. The regulator investigating its environmental claims sits in Vancouver. The duty that took 380 basis points out of its operating margin has been imposed under three different statutes since February, two of which courts have already struck down.
Below is what the framework looks like when you stop adding the buckets and start comparing them.
The setup: what the standard reading gets wrong
Lululemon closed fiscal 2025 (year ended February 1, 2026) with revenue of $11.10 billion, up 5%. Gross margin fell 260 basis points to 56.6%. Operating margin fell 380 basis points to 19.9%. Diluted EPS dropped from $14.64 to $13.26. The company runs 811 owned stores, employs roughly 39,000 people, owns no factories, and carries the inventory risk on nearly all of it, since wholesale is close to zero.
The June 4, 2026 guidance cut put fiscal 2026 revenue at $11.0 billion to $11.15 billion, flat to down 1%, with operating margin down another 380 basis points. Hold revenue flat and that guidance implies operating profit of roughly $1.78 billion against $2.21 billion, a drop of about $426 million. The macro environment is charging Lululemon close to half a billion dollars a year while barely touching the top line.
Here is how the two readings diverge.
| Factor | Standard reading | What the 2026 record shows |
|---|---|---|
| Political | Tariffs raise costs across the industry | The duty is stable, the statute under it is not |
| Economic | A soft US consumer is offset by international growth | The offset market neighbors the input base |
| Social | Athleisure demand is a durable global tailwind | US shoppers are trading down while Chinese shoppers trade up |
| Technological | Fabric innovation is the moat | Suppliers hold the fabric IP, and they sell to the copyists too |
| Legal | Compliance is a cost of doing business in 30 markets | Trade law, forced-labor law and disclosure law all point at the same suppliers |
| Environmental | Sustainability credentials support the premium price | Lululemon’s own regulator opened a file on those credentials |
Political factors
The Section 301 forced-labor tariffs are the single largest political input to Lululemon’s P&L, and the way the United States arrived at them tells you more than the rate does.
USTR opened 60 investigations on March 12, 2026, determined the practices actionable on June 2, announced final action on July 23, and started collecting at 12:01 a.m. on July 24. That is 134 days from opening to collection, against Section 301 cases that historically run more than a year. The duties cover roughly 60 economies representing more than 99% of US imports, at 10% for countries with an enforced forced-labor import prohibition and 12.5% for those without.
Lululemon’s disclosed assembly base carries the load. Vietnam accounts for 40% of production, Cambodia 18%, Sri Lanka 11%, Indonesia 11% and Bangladesh 7%, which covers 87% of the total. Fabric comes from a different set of countries: Taiwan 34%, China Mainland 29%, South Korea 10% and Vietnam 10%. The Lululemon value chain analysis works through what that two-country routing does to the landed cost of a single garment.
The de minimis exemption is the second political input, and it is already spent. Treasury ended it for certain shipments on May 2, 2025 and globally on August 29, 2025, with statutory repeal following by July 1, 2027. Lululemon fulfilled most US e-commerce orders from Canadian distribution centers under that exemption. Asian goods sitting in an Ontario warehouse do not become Canadian goods, so USMCA offers no relief.
Taiwan is the third, and Lululemon named it in its own fiscal 2025 risk factors for the first time. One third of the company’s fabric comes from an island the Taiwan Textile Federation describes as roughly 70% of world functional textile production. Second-sourcing away from Taiwan means moving toward China Mainland, which supplies the next 29%.
A fourth political input has not landed yet. USTR opened a separate Section 301 investigation on March 11, 2026 into structural excess manufacturing capacity across 16 economies, and any duty from it stacks on top of the forced-labor rate. Cross the 16 against Lululemon’s disclosed sourcing base and seven of its eight sourcing countries appear on the list: Vietnam, Cambodia, Indonesia and Bangladesh on the assembly side, Taiwan, China Mainland and South Korea on the fabric side. Sri Lanka is the only one missing. The Federal Circuit’s 2025 ruling in HMTX Industries, which the Supreme Court declined to review on June 15, 2026, gives USTR wide latitude to modify Section 301 actions once they exist.

Economic factors
Two consumer cycles run in opposite directions, and Lululemon sits on both.
In the Americas, 70.7% of revenue, the company guided fiscal 2026 revenue down high single digits, with the second quarter down low double digits. Oxford Economics puts the bottom 80% of US consumers near a record-low share of budget spent on discretionary items. McKinsey’s second-quarter 2026 consumer survey found spending pullbacks across most discretionary categories, worst among low-income households but reaching higher earners cutting what the researchers called nice-to-haves. Placer.ai’s first-quarter data showed off-price apparel leading while full-price and luxury lost traffic. A brand that refuses to discount, for good reasons covered in the Lululemon SWOT analysis, has few tools in that environment.
China Mainland runs the other way. Revenue there grew 28.9% in fiscal 2025 and 30% in the first quarter of fiscal 2026. Bigone Lab tracked Chinese sports and health online sales up 22% in January and February 2026, accelerating from 12% in the fourth quarter of 2025, with no government subsidy behind it. Analysts at Baiguan describe urban professionals in Beijing’s Guomao and Shanghai’s Xintiandi swapping luxury handbags for running shoes and leggings.
Add those two cycles and the arithmetic is stark. China Mainland delivered $393 million of Lululemon’s $517 million in net revenue growth last year while the Americas subtracted $79 million. A segment worth 15.8% of revenue produced 76.2% of the growth, a multiplier of 4.8 times.
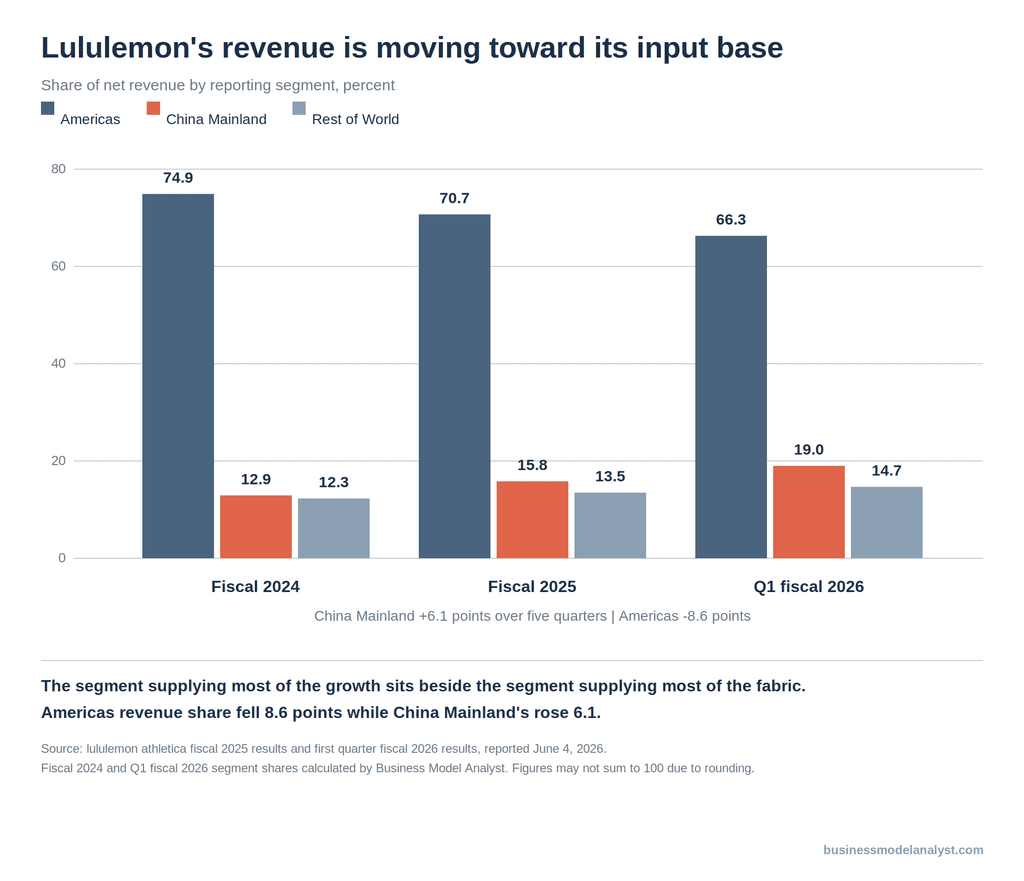
That is usually framed as diversification working. Read it alongside the sourcing map and it is the opposite. Growth is migrating into the same neighborhood the fabric comes from.
Capital allocation is accelerating the move. Of the 40 to 45 net new stores planned for fiscal 2026, 25 to 30 sit in international markets with the majority in China Mainland, against 15 in the Americas of which roughly eight are in Mexico. Lululemon ended fiscal 2025 with more than 170 China Mainland stores and is spending $700 million to $720 million of capex this year on distribution centers, stores and technology. Management is putting new store capital into the geography that already carries the highest correlation with the input base, which is the rational response to where the demand is and the reason the exposure keeps compounding.

Social factors
The dupe problem is a supply-chain fact wearing a social-trends costume.
Lululemon added a dedicated risk factor for imitation products in fiscal 2025. In the United States, Alo Yoga and Vuori take the share. In China, the field is denser and cheaper. Anta bought Maia Active, a brand designed for Asian female bodies by mainland founders and priced at roughly half Lululemon’s range, and is now running it through the same playbook it used on FILA and Arc’teryx. Particle Fever, VFU and Li-Ning’s Danskin license fill in below.
None of these companies broke a patent. They ordered from the same class of mill. The taste shift toward premium activewear that carries Lululemon in Tier 1 Chinese cities also funds the competitors who can reach Tier 2.5 and below, where price comparison beats brand world.
US social risk points a different direction. Lululemon’s fiscal 2025 risk factors name political polarization and consumer boycotts, a first for the company. Combine that with a premium price in a trading-down market and the social factor scores negative at home and positive abroad, splitting along the same line as everything else.
Technological factors
Two technology exposures matter, and both trace back to suppliers.
The first is fabric. Lululemon’s 10-K states that the intellectual property in its technology, fabrics and processes is owned or controlled by its suppliers rather than by the company, and describes its own patent position as limited. Luon, Nulu and Everlux are trademarks backed by trade secrets and contracts. Most competitor pages still call proprietary fabric the moat, which gets the causation backwards.
The second is discovery. Lululemon disclosed for the first time in fiscal 2025 that AI-enabled shopping tools reduce its control over how customers find products. For a brand that has spent 25 years building store communities, run clubs and ambassador rosters as the top of its funnel, an assistant that answers “best leggings under $80” strips out the layer where Lululemon does its work.
Both exposures land upstream, and both worsen with the same event. A shock to the Northeast Asian mill cluster hits the fabric. A shift to agentic retail hits the brand premium that justifies paying more for that fabric.
Legal factors
Trade litigation now moves faster than trade policy, and neither one lowers the bill.
Importers sued over the Section 301 forced-labor tariffs on the day they took effect. Burlap and Barrel and Collective Horology filed at the Court of International Trade, and on August 3, 2026, 25 state attorneys general co-led by Oregon, Arizona and California filed State of Oregon v. Trump, No. 26-03467, arguing that forced labor is a pretext for keeping a global duty alive under a third statute. The Supreme Court struck down the IEEPA tariffs on February 20. The Court of International Trade held the Section 122 surcharge unlawful in May, and it expired by operation of law on July 24. Section 301 duties started the same day, with no gap.
For a planning department, that record has one meaning. Winning in court has not lowered the rate. It has changed the letterhead. Lululemon’s importer-of-record position and its claim on any refunds is covered in tariff refunds and the importer of record.
Forced-labor law is the second thread, and it runs through the same suppliers. The company flagged UFLPA compliance and first-sale customs valuation as open questions in fiscal 2025. It also ranked first on KnowTheChain’s forced-labor disclosure index, which changes nothing about the duty: Section 301 charges by country of origin, not by importer conduct.
The third thread sits at home. Canada’s Competition Bureau opened a formal investigation into Lululemon’s environmental marketing in May 2024, following a Stand.earth complaint alleging that the “Be Planet” campaign clashed with a doubling of Scope 3 emissions since 2020. Bill C-59 added substantiation requirements in June 2024 and, from June 20, 2025, let private parties seek leave to bring deceptive-marketing cases directly to the Competition Tribunal. Exposure runs up to 3% of worldwide gross revenues. Ottawa then proposed removing parts of the regime in its November 2025 budget implementation act, so the risk is live and the rules underneath it are moving, which is the same pattern as the tariff.
A fourth thread is opening in the growth market. Beijing’s State Administration for Market Regulation has run a national campaign against “involution,” the term Chinese officials use for destructive price competition, and has paired it with a revised Anti-Unfair Competition Law effective October 15, 2025 and revised rules on vertical agreements effective February 1, 2026. Restricting below-cost pricing and subsidy wars favors domestic brands with deep multi-brand portfolios, which describes Anta more than it describes Lululemon. The vertical-agreement rules also reach non-price restraints such as territorial and customer restrictions, the kind of distribution control a single-brand direct retailer relies on.
Meanwhile the EU’s Empowering Consumers directive applies from September 27, 2026, and California SB 253 catches any company above $1 billion in revenue doing business in the state, with the first Scope 1 and 2 report due November 10, 2026. Lululemon clears both thresholds.
Environmental factors
Lululemon’s environmental exposure is the supply-concentration exposure with a different label on it.
The company published its fifth consecutive Impact Report in November 2025 and used it to reset. It cut its 2030 preferred-materials target from 100% to 90%. It missed the 2025 goal of a 50% intensity reduction in single-use plastic and removed the goal from future reporting. It hit its recycled polyester sub-target a year early at 77% of procured polyester, and reached 11% on renewable or recycled nylon, where the report blames the difficulty of scaling preferred nylon 6,6. Supply-chain emissions fell 29% in intensity against the 2021 baseline, against a 60% reduction target for 2030.
Every one of those numbers depends on decisions made inside factories Lululemon does not own. Renewable electricity among core Tier 1 and Tier 2 suppliers stood at 15% against a 50% target for 2030. Noel Kinder, formerly Nike’s chief sustainability officer, joined as SVP of sustainability in May 2025 to close that gap, and the gap closes when mills in Taiwan, China Mainland and Vietnam change their power procurement.
The materials targets have the same shape. Preferred nylon does not scale because the upstream capacity does not exist yet, and the capacity that does exist sits in the same Northeast Asian cluster that supplies 73% of Lululemon’s fabric today. The environmental factor and the political factor are reading from the same map.
The correlation problem
Add the six buckets and Lululemon looks spread across 30 countries. Compare them and three of the company’s four largest exposures sit within a few hundred miles of each other.

The test of any macro analysis is whether it produces a move. Run the standard remedies against Lululemon’s 2026 position and each one lands back where it started.
| Standard remedy | Where it lands | Why the exposure does not fall |
|---|---|---|
| Grow international to offset a soft US market | China Mainland | Adds demand exposure to the region already supplying 63% of fabric |
| Move fabric out of China Mainland | Taiwan | Taiwan is roughly 70% of world functional textile output, on the same strait |
| Shift more assembly to a safer origin | Vietnam | Already 40% of assembly and the highest duty rate in the disclosed base |
| Litigate the tariff | US courts | Two of three statutes struck down, and the duty never lapsed |
| Raise prices to recover margin | US consumer | Bottom 80% near a record-low discretionary share, off-price leading apparel |
| Lean on sustainability positioning | Canada, EU, California | The home regulator opened a file, and targets have already been reset |
Two of those routes are worth stress-testing, because the bear case here can be overstated.
The first counterargument is that geographic correlation cuts both ways. Chinese demand has held up through every US tariff round so far, and a trade shock that raises Lululemon’s landed cost in Portland does nothing to a store in Chengdu selling RMB-denominated inventory sourced regionally. That is fair, and it is the strongest argument for the current strategy. It holds until the shock originates in the Taiwan Strait rather than in Washington, which is the one event that hits demand and supply in the same quarter.
The second is that Lululemon’s tariff assumption may be conservative. Guidance assumes 20% incremental duty in the second half and excludes any IEEPA recovery, which at the first-quarter run rate is worth roughly $310 million annualized. The actual Section 301 blend across Lululemon’s sourcing base runs well under that assumption. Both of those are upside to the printed numbers, and neither changes the correlation.
What Heidi O’Neill inherits
O’Neill takes over in September 2026 with the interim co-CEO arrangement between Meghan Frank and Andre Maestrini ending, two Chip Wilson nominees seated on the board after the June annual meeting, and a third product and brand director due by October 1.
The macro list she inherits has one item on it disguised as six. Lululemon can pull a lever on any single factor. It can raise prices, reroute fabric, restate a climate target or litigate a duty. What it cannot do is pull a lever that reduces two of them at once, because the factors share a driver.
FAQ
What is a PESTLE analysis of Lululemon? It is a structured scan of the six external forces acting on the company: political, economic, social, technological, legal and environmental. For a fuller treatment of the framework itself, see what is PESTLE analysis.
What is the biggest political risk to Lululemon in 2026? The Section 301 forced-labor tariffs that took effect on July 24, 2026, at 10% or 12.5% depending on origin, layered on a sourcing base where five Asian countries handle 87% of assembly. The instability of the legal authority matters as much as the rate, since the same duty has run under three statutes since February.
How dependent is Lululemon on China? More than the revenue share suggests. China Mainland was 15.8% of fiscal 2025 revenue and 19% by the first quarter of fiscal 2026, but it produced 76% of last year’s net revenue growth. On the supply side, China Mainland and Taiwan together account for 63% of the company’s fabric.
Why is Lululemon under investigation for greenwashing? Canada’s Competition Bureau opened a formal investigation in May 2024 after Stand.earth complained that the “Be Planet” campaign misrepresented the company’s climate position while its Scope 3 emissions doubled from 2020. No finding has been issued. Penalties under the amended Competition Act can reach 3% of worldwide gross revenues.
Does international expansion reduce Lululemon’s risk? It reduces dependence on the US consumer and increases dependence on Greater China, where the fabric already comes from. Our piece on Nike losing China while Lululemon bets on it covers the upside case in detail.
How do external factors show up in Lululemon’s numbers? Through margin rather than revenue. Fiscal 2026 guidance holds revenue roughly flat while cutting operating margin 380 basis points, which works out to about $426 million of operating profit. With almost no wholesale and no franchise base, Lululemon has no partner to share a cost shock with.
The Business Model Analyst Take
The framework itself is what fails here. A PESTLE analysis assumes six independent forces, and independence is what lets you add scores across buckets and call the sum a risk profile. Lululemon breaks that assumption. Its political, legal and environmental exposures all resolve into the conduct of mills it does not own, and its economic and social exposures split along the same US-versus-Greater-China line as its sourcing map.
The company earned that position honestly. Building a distribution network around a customs exemption, sourcing performance fabric from the cluster that makes the best performance fabric, and chasing growth into the market that wanted the product all made sense one decision at a time. The correlation showed up later, and nobody at Lululemon chose it in a single meeting.
For anyone running this analysis on their own business, the transferable move is to stop scoring the six factors and start scoring the pairs. Ask which two buckets would move together in a bad quarter. If the answer is more than one pair, the framework is flattering you.
Read this alongside the Lululemon business model and the Lululemon target market for the internal picture, and the economic factors affecting business and environmental factors affecting business explainers for the framework detail.