
To live entirely off dividends in 2026, you need roughly $2.2 million invested at a realistic quality-dividend yield of about 3.5% to cover the average US household’s spending of $78,535 a year. A leaner solo lifestyle of around $40,000 needs closer to $1.1 million. Anything under $500,000 pays a useful supplement, not a salary. The number swings hard with the yield you chase, and chasing the highest yield is usually the wrong move. Here is the full ranking, tier by tier, with the math laid out.
How dividend income scales with portfolio size
Dividends are simple arithmetic: your annual income is your portfolio balance multiplied by its yield. The catch is that “the yield” is not one number. It depends entirely on what you own. A plain S&P 500 fund yields about 1.05% in mid-2026, near an all-time low, because the index is dominated by tech companies that pay little or nothing. A quality dividend ETF like Schwab’s SCHD yields around 3.25%. High-yield covered-call funds and REIT-heavy strategies can pay 7% or more, but that number comes with strings attached that we will get to.
Here is what each portfolio size produces per year across those three worlds.
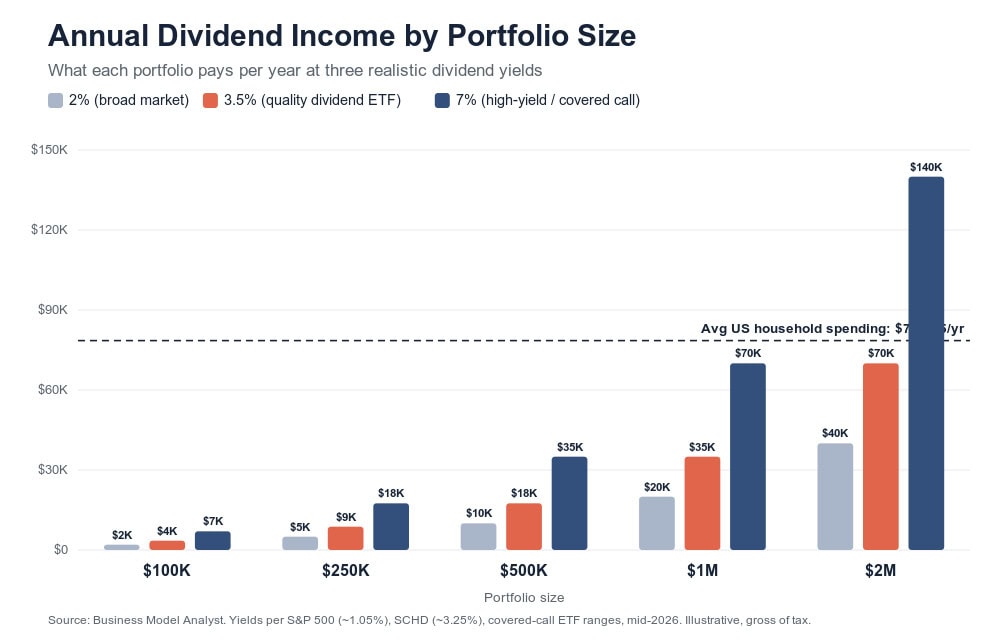
The dashed line is the punchline. It marks the $78,535 that the average American household actually spends in a year. Notice how few of these bars clear it. Only a $2 million portfolio at 3.5% gets there comfortably, and only a $1 million portfolio does it by reaching for a risky 7% yield. Everything to the left is a supplement to other income, not a replacement for it.
| Portfolio | At 2% (broad market) | At 3.5% (quality dividend) | At 7% (high-yield) |
|---|---|---|---|
| $100,000 | $2,000 | $3,500 | $7,000 |
| $250,000 | $5,000 | $8,750 | $17,500 |
| $500,000 | $10,000 | $17,500 | $35,000 |
| $750,000 | $15,000 | $26,250 | $52,500 |
| $1,000,000 | $20,000 | $35,000 | $70,000 |
| $2,000,000 | $40,000 | $70,000 | $140,000 |
| $5,000,000 | $100,000 | $175,000 | $350,000 |
The ranking: what each portfolio size actually buys you
$100,000 to $250,000 (the supplement tier). At a sensible 3.5% yield, this pays $3,500 to $8,750 a year, or roughly $290 to $730 a month. That covers a utility bill, a car payment, or a decent chunk of groceries. It is real money and worth building, but nobody quits a job on it. The honest use here is reinvestment: let the dividends compound and buy more shares until the balance is large enough to matter.
$500,000 to $750,000 (the lean and partial tier). Now you are producing $17,500 to $26,250 a year at 3.5%. That can cover a frugal single person in a low-cost part of the country, especially when paired with a small pension, Social Security, or part-time income. It is the classic “lean FIRE” zone: possible, but with little margin for a bad market or a surprise expense.
$1 million to $2 million (the real threshold). This is where living off dividends stops being a fantasy. At 3.5%, a $2 million portfolio throws off $70,000 a year, within striking distance of average household spending. A $1 million portfolio at 3.5% pays $35,000, enough for a genuinely modest household. This tier is the honest answer to “how much do I need,” and most people badly underestimate how far into seven figures it sits.
$5 million and up (the comfortable tier). At 3.5%, $5 million pays $175,000 a year, comfortably above average spending with room to reinvest a portion, outrun inflation, and never touch the principal. This is the “worry-free” zone, and it is worth being clear that it requires genuine wealth, not a clever yield trick.
How much you actually need to cover the bills
Flip the question around. Instead of asking what a portfolio pays, ask how big it has to be to fund a specific lifestyle. The formula is annual spending divided by yield, and the results are sobering at safe yields.
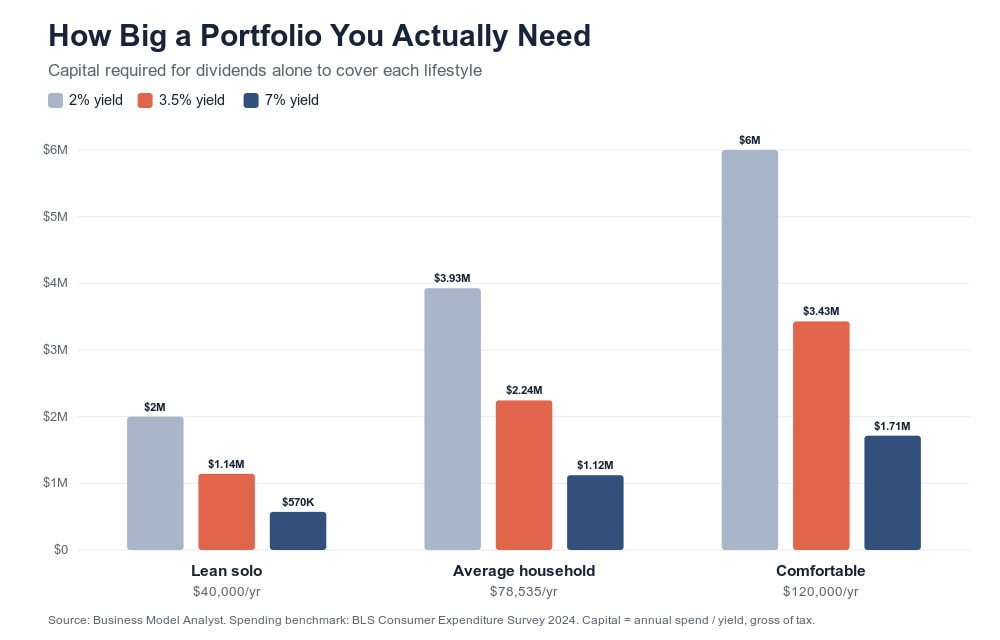
To cover the average household’s $78,535 at a safe 3.5% yield, you need about $2.24 million. Insist on the safety of a 2% broad-market yield and the number balloons to nearly $4 million. Push into 7% high-yield territory and it drops to $1.12 million, which is exactly why so many people are tempted by high-yield funds. That temptation is the most important thing to get right, so let us take it apart.
The trap: why the highest yield usually loses
The instinct is obvious. If 7% halves the portfolio you need, why not just buy the 7% funds? Because a high headline yield and a durable income stream are not the same thing.
Most 7%-plus yields come from covered-call ETFs (which cap your upside by selling options) or leveraged and REIT-heavy strategies. Their distributions are often flat or shrinking over time, and in many cases the fund’s share price slowly erodes, quietly returning your own capital to you and calling it income. A quality dividend payer does the opposite. SCHD, for example, has grown its dividend at roughly 8% to 11% a year over the past five years, and its share price tends to rise alongside the payout.
Watch what that does over time on a $1 million portfolio.
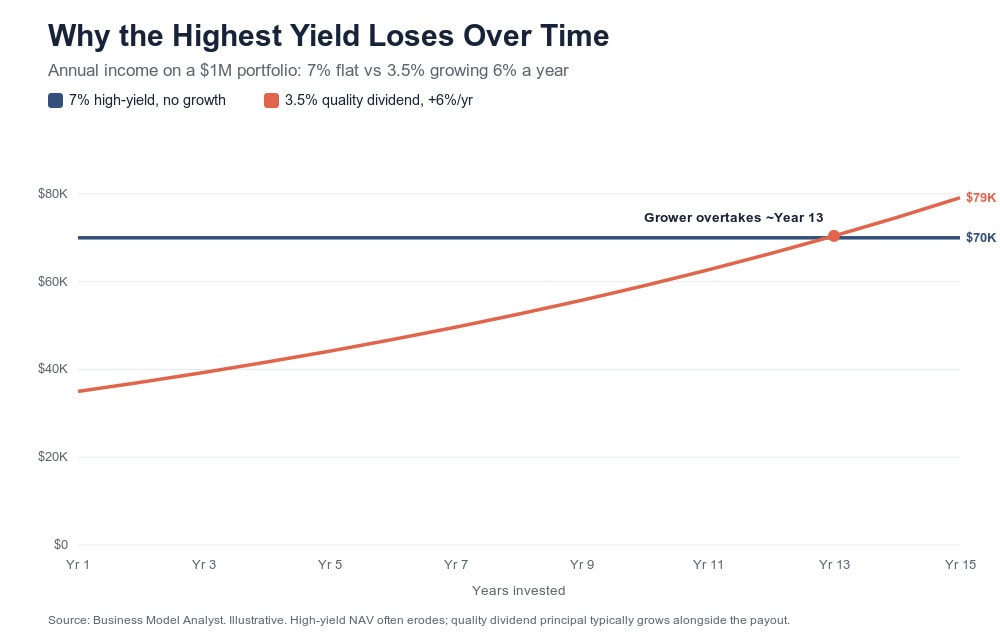
The 7% fund pays $70,000 in year one and, if you are lucky, $70,000 in year fifteen. The 3.5% quality grower starts at just $35,000, but rising about 6% a year it overtakes the high-yield fund around year 13 and keeps climbing, while your principal grows too. At faster historical growth rates the crossover comes even sooner. The high yield wins the first decade and loses the rest of your life. For someone actually planning to live off this income for thirty years, that is the whole ballgame.
The tax angle almost everyone ignores
Here is the part that rarely makes it into these articles, and it can change the math entirely. Qualified dividends, the kind most large US companies and quality dividend ETFs pay, are taxed at long-term capital gains rates, not ordinary income rates. And the lowest of those rates is 0%.
In the 2025 tax year, a married couple filing jointly with taxable income up to about $96,700 pays zero federal tax on their qualified dividends. Because taxable income is calculated after the standard deduction (around $30,000 for a couple), a household with little other income could receive well over $120,000 in gross qualified dividends and still owe nothing to the IRS. These thresholds adjust upward each year for inflation. Individual situations vary, state taxes differ, and this is not tax advice, so confirm your own numbers with a professional. But the structural point stands: dividend income is one of the most tax-efficient ways to fund a life in the entire US tax code, and it makes the “how much do I need” figure lower after tax than the gross charts suggest.
The counterargument: is dividend investing even the smart play?
A well-informed skeptic would push back on this entire premise, and they would have a point. Living off dividends means refusing to sell shares, which feels safe but is not obviously optimal. The total-return approach says you should own the best mix of assets for growth and simply sell a small slice each year, the classic “4% rule.” Because you can sell shares, you are not limited to a 1% to 3.5% dividend yield; you can safely spend around 4% of a diversified portfolio, which means you need less money than the dividend-only path requires. You also avoid tilting your whole portfolio toward a handful of dividend-heavy sectors and missing the growth of companies that reinvest instead of paying out.
The honest verdict: dividend-only investing trades some mathematical efficiency for psychological durability. Never touching your principal is easier to stick with in a crash than selling shares while prices are falling, and behavior is what actually determines outcomes. Neither approach is wrong. Just know that “live off dividends” is a discipline choice as much as a math choice, and the purest version leaves some money on the table for peace of mind.
If you are still assembling the income side of your life rather than the portfolio side, our breakdown of why passive income is harder than it looks and these automated business ideas for passive income are the realistic companions to this piece. And if you are choosing where to actually hold a dividend portfolio, our look at Fidelity’s competitors and alternatives covers the major brokerages, while the BlackRock business model explains the firm behind many of the dividend ETFs you will be buying.
Frequently asked questions
How much do I need to live off dividends?
For the average US household spending about $78,535 a year, roughly $2.2 million at a realistic 3.5% quality-dividend yield. For a lean solo budget near $40,000, about $1.1 million. The safer the yield you insist on, the more capital you need.
Can I live off dividends with $500,000?
At 3.5%, $500,000 pays about $17,500 a year. That can cover a frugal single person in a low-cost area, usually alongside other income like Social Security or part-time work, but it is tight as a sole income source.
What is a realistic dividend yield in 2026?
A broad S&P 500 fund yields about 1.05%. Quality dividend ETFs pay around 3% to 3.5%. Yields of 7% or more exist but usually come from covered-call or high-risk strategies whose payouts do not grow and whose principal can erode.
Are dividends taxed?
Qualified dividends are taxed at favorable long-term capital gains rates, including a 0% bracket for lower taxable incomes. This makes dividend income unusually tax-efficient, though rules vary by situation and state.
Is living off dividends better than the 4% rule?
Not necessarily. A total-return approach that sells a small slice of a diversified portfolio each year can require less money. Dividend investing wins mostly on discipline, since never selling is easier to stick with during a downturn.
The Business Model Analyst Take
Treat a dividend portfolio the way you would treat any business: the yield is the profit margin, and margin without growth is a slow death. The single biggest mistake in this space is optimizing for the headline yield, the equivalent of a company juicing this quarter’s earnings by starving next year’s. The 7% fund is a business paying out more than it earns and shrinking its own balance sheet to do it. The 3.5% quality grower is a business reinvesting enough to raise its payout every year for decades. Over a retirement-length horizon, the second one wins so decisively that the first only makes sense for someone who needs maximum cash now and does not care about ten years from now.
The other unglamorous truth is the number itself. Genuine dividend independence starts in the low seven figures and does not get comfortable until $2 million and up. That is not a reason to skip dividend investing. It is a reason to start early, reinvest relentlessly, favor payout growth over payout size, and let the tax efficiency and compounding do the heavy lifting. The investors who get there are rarely the ones who found the highest yield. They are the ones who owned the most boring quality payers the longest.