
The strategy that saved Lionsgate from another Borderlands is the same one that caps what its biggest hit ever can pay for. The number that matters is not $1 billion. It is $1.46 billion.
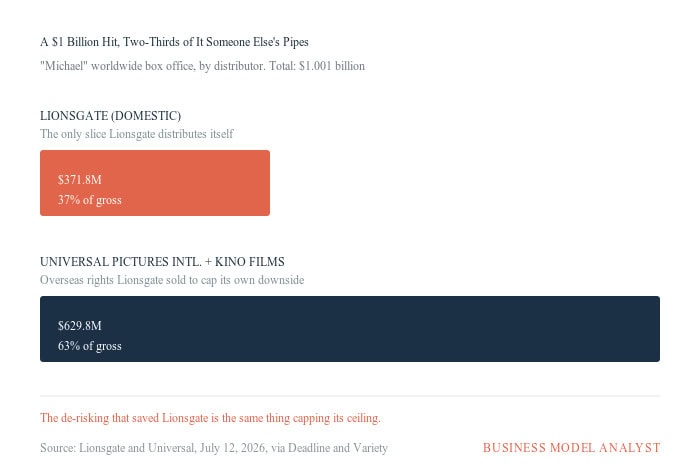
Lionsgate’s Michael Jackson biopic crossed $1.001 billion at the global box office over the weekend, the first biopic in history to do it and the first billion-dollar film in Lionsgate’s 27 years. But $629.8 million of that ran through Universal and Kino Films, not Lionsgate. The studio sold those rights on purpose, because selling them is how it survives. That trade has a bill attached, and it comes due in the ceiling.
A year ago Lionsgate stock traded at $5.76 and the only serious question in Hollywood was who would buy the carcass. Today the stock is north of $13, the studio owns two brand new theatrical franchises, and Morgan Stanley is calling it a comeback. All of that is real. It is also, on the numbers, not the same thing as being safe.
What Happened
“Michael” opened April 24 against pre-release projections of $65 million to $70 million and did $97.2 million domestically, a record opening for a musical biopic. It kept going. By June 14 it had passed “Bohemian Rhapsody” ($911 million) to become the highest-grossing music biopic ever. By June 28 it passed “Oppenheimer” ($975.8 million) to become the highest-grossing film about a real person, period. On July 12, after a strong run in Japan, Lionsgate and Universal confirmed the global total at $1.001 billion: $371.8 million domestic, $629.8 million international.
The film cost roughly $150 million by the studio’s account, with trade reports putting the figure between $155 million and $200 million after 2025 reshoots. Hollywood’s biggest studios passed on it. Decades of child-molestation allegations against Jackson made the project untouchable for companies with theme parks and toy licenses to protect. Lionsgate has neither, so it took the risk.
It was not the only one. “The Housemaid,” a thriller adapted from Freida McFadden’s novel, cost $35 million and collected $400.5 million. Sequels to both are in development. No other studio found two new theatrical franchises this year.
The Backstory
The collapse was not subtle. Lionsgate released 17 movies in 2024 and generated $251 million in domestic ticket sales, down 85% from its 2012 peak of $1.72 billion, when Katniss Everdeen, the Twilight vampires, Madea and the Expendables were all working at once. “Borderlands” cost $115 million and made $33 million worldwide. Shares hit their lowest point since theaters were closed for Covid.
Adam Fogelson, a former Universal Pictures chairman, took over the Lionsgate Motion Picture Group in 2024 and inherited a slate scrambled by the pandemic and the strikes. His first films started arriving late last year. Almost every one has worked, including “The Long Walk” and the sequel “Now You See Me: Now You Don’t.” Lionsgate now holds roughly 10% of the domestic box office this year, nearly double Warner Bros., according to IMDbPro.
The financial turn shows up in the filings. In the quarter ended March 31, before “Michael” opened, Lionsgate reported revenue of $906.5 million, operating income of $117.5 million (up 52% year over year), net income of $70.2 million, and adjusted OIBDA of $165.4 million, its best quarterly figure in twelve years. Free cash flow was $190.4 million.
The Plan
The pipeline is deep and almost entirely borrowed. A “Hunger Games” sequel arrives in November. Behind it: a “Rambo” prequel, two more “John Wick” films, “Now You See Me 4,” and two sequels to Mel Gibson’s “The Passion of the Christ.” Lionsgate has partnered with Jason Blum to reboot “The Blair Witch Project” and with James Wan to revive “Saw.” Fogelson says a “Michael” sequel update is coming later this summer, alongside a new “Dirty Dancing” with Jennifer Grey and continued efforts to restart “Twilight.”
On the television side, CEO Jon Feltheimer told analysts the studio would nearly double its scripted episode deliveries this year. And underneath all of it sits the asset nobody writes headlines about: a 20,000-title library that generated more than $1 billion in trailing twelve-month revenue for the third straight quarter.
The Business Model Angle
Here is the arithmetic the celebration skips.
Lionsgate’s standing practice is to sell most overseas distribution rights and to spend far less on marketing than its rivals. That is not a weakness. It is the entire reason the company is still standing. Pre-selling foreign territories converts a speculative $150 million bet into a partially de-risked one before a frame is shot. It is why “Borderlands” was a bad quarter instead of an extinction event.
But de-risking is symmetric. You do not get to sell the downside and keep the upside. Universal Pictures International and Kino Films handled 63% of “Michael’s” gross, and they did not do it for free. Lionsgate does not disclose title-level economics, so the exact split is opaque, but the direction is not: a billion-dollar film at Disney or Universal drops into a vertically integrated machine that re-monetizes it through parks, consumer products, and a wholly owned streamer. The same billion at Lionsgate is monetized once, partially, and then flows into the library.
That is the real Lionsgate business model, and it is worth naming honestly, because it is not a movie studio in the way people assume. It is a de-risked IP origination shop that feeds a library annuity. The films are the acquisition cost. The library is the revenue. Every hit permanently increases the size of the annuity, which is genuinely valuable and genuinely durable.
It just does not compound the way a conglomerate does. Compare it to the Disney business model, where a single character becomes a ride, a cruise line, a merchandise category, and a subscription retention tool. Disney’s Experiences segment threw off $10 billion in operating income in fiscal 2025, which is why, as the Disney SWOT analysis lays out, its films can underperform without threatening the enterprise. Lionsgate has no such cushion. When a film disappoints, the whole company feels it, and when a film explodes, only part of the company feels it.
Notably, the cheap-IP playbook is working better than the expensive one. “The Housemaid” cost $35 million and returned more than eleven times its budget. “Michael” cost four to five times as much and returned less than three times its budget on a gross Lionsgate mostly does not collect. That echoes what happened when a $10 million meme movie beat the franchises: in a market this fragmented, the return on low-cost, culturally native IP is beating the return on prestige swings.
The Risk
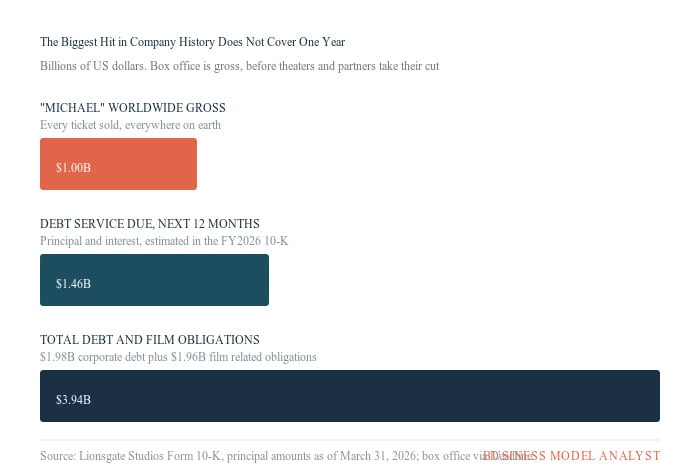
As of March 31, 2026, Lionsgate carried approximately $1.98 billion in corporate debt principal and another $1.96 billion in film-related obligations, roughly $3.94 billion in total. Its own 10-K estimates debt service, principal and interest, at about $1.46 billion over the next twelve months.
“Michael” grossed $1.001 billion worldwide. That is the whole box, before exhibitors keep their roughly half, before Universal takes its international cut, before marketing. The single biggest film in the history of the company does not cover one year of debt service at gross, let alone at net. That is not a scandal. It is what leverage looks like at a company with no second business. But it explains why a 130% stock move and a Morgan Stanley victory lap have not made the acquisition question go away.
Here is the counterintuitive part, and it is the thing worth watching. The hits did not buy Lionsgate independence. They built the shop window.
At $5.76, Lionsgate was a distressed asset with a broken slate and a two-class share structure. Nobody pays up for that. At $13-plus, with two proven new franchises, a billion-dollar library annuity, a cleaned-up single class of voting stock, and a Hunger Games sequel landing in November, it is a legible, priceable, easy-to-underwrite acquisition target. Sony, Hasbro, and Legendary have all circled before. Netflix was rumored last month and denied it. Mark Rachesky and Steven Mnuchin control roughly a quarter of the shares between them and now have something worth negotiating over.
Morgan Stanley’s Sean Diffley said the studio has proven it can stand alone, then added that the market still believes scale matters. Both halves of that sentence are true. The debt is why the second half wins.
Quick Questions
Did Lionsgate keep the $1 billion? No. It distributed $371.8 million of it domestically. Universal Pictures International and Kino Films distributed the other $629.8 million under rights Lionsgate sold in advance.
Was “Michael” profitable? Almost certainly yes, but not at the scale the headline implies. Lionsgate does not disclose title economics, and the pre-sold foreign rights mean the studio’s share of a $1 billion gross is far smaller than the number suggests.
Why did other studios pass on it? The child-molestation allegations against Jackson made the project a brand-safety risk for companies with theme parks, toy licenses, and family-facing consumer businesses to protect. Lionsgate has none of those exposures.
What is Lionsgate’s biggest business, really? The library. Its 20,000-title catalog has produced more than $1 billion in trailing twelve-month revenue for three consecutive quarters, a more reliable earnings base than any single slate.
Is Lionsgate going to be sold? Nobody has announced anything. But it is a more attractive and more easily valued target now than it was a year ago, and its debt load gives its two largest shareholders a rational reason to listen.
The Business Model Analyst Take
The trades wrote “the lion roars.” The more useful read is that Lionsgate just proved its model works exactly as designed, and that the design has a ceiling bolted to it.
Selling foreign rights and underspending on marketing is a coherent, disciplined answer to being the last independent in a business run by conglomerates. It caps the downside. It is why Lionsgate survived a slate that would have killed it in 2012. But the same mechanism means the company cannot capture a windfall when one arrives. A billion-dollar film is supposed to be the event that resets a balance sheet. At Lionsgate, it is a very good year that does not cover the interest.
That leaves exactly one strategic question, and it has nothing to do with the next movie. Lionsgate has to decide whether the library annuity plus a de-risked slate is a permanent, defensible standalone business, or whether it is a well-dressed asset waiting for a buyer with a distribution network to plug it into. The evidence points to the second. A conglomerate that owned “Michael” outright would have kept the foreign gross, pushed the IP into consumer products, and used it to drive a streamer. Lionsgate got the headline and a bigger library.
The bet Fogelson is making is that enough hits, fast enough, buy the company out of that trap. Watch the November “Hunger Games” release, and watch whether Lionsgate keeps more of the foreign rights on its next big swing. If it starts holding those rights, it believes in the standalone future. If it keeps selling them, it is optimizing an asset for sale.
Reporting based on The New York Times’ coverage of Lionsgate’s turnaround, with box office figures from Deadline, Variety, and Forbes, and financial data drawn from Lionsgate Studios’ fiscal 2026 Form 10-K and fourth-quarter earnings release.