
A leadership team sees revenue still rising and assumes the market is healthy. Two years later, hiring freezes begin, pricing gets tighter, and a competitor starts buying smaller players. Nothing “sudden” happened. They misread the life cycle of an industry.
Why Industries Rise and Fall
Managers often explain success and failure through execution alone. One company innovated better. Another hired better. A third marketed poorly. Those things matter, but they don’t explain why strong firms can still struggle when the economics of an industry shift under them.
That’s where the life cycle of an industry becomes useful. It gives leaders a way to interpret changing demand, changing competition, and changing profit pools as part of a broader pattern rather than as isolated events. The framework matters because industries don’t stay in one competitive state forever. They move from experimentation to expansion, then often into consolidation and slower growth, and in some cases into stagnation or contraction, as described in this overview of industry life cycles.
What executives usually miss
Organizations often notice change too late because they focus on company performance in isolation. They watch their own sales, their own costs, their own pipeline. They don’t ask the harder question: has the market shifted from rewarding entry and expansion to rewarding scale, efficiency, and staying power?
IBISWorld’s framing is especially practical. It treats life-cycle analysis as a relative test, not an absolute one. In the growth stage, an industry expands faster than GDP. In maturity, it grows at about the same rate as the economy. In decline, it grows more slowly than the economy. It also points to four indicators leaders can use in the field: product performance, the number of enterprises, technological change, and market acceptance, as outlined in IBISWorld’s guide to understanding industry life cycles.
Practical rule: Don’t ask whether your industry is growing. Ask whether it’s still growing faster than the broader economy, and whether that growth is attracting new entrants or forcing consolidation.
That shift changes almost every management decision.
A founder in an expanding category should think about customer acquisition, product-market fit, and speed. A CEO in a maturing category should think about concentration, cost position, and capital allocation. The same top-line momentum can hide very different strategic realities.
For a sharper lens on how strong companies are interpreted through strategic frameworks, this piece on the importance of strategic analysis in understanding successful companies is a useful complement. The key lesson is simple: companies don’t operate above industry structure. They operate inside it.
The Industry Life Cycle Model Explained
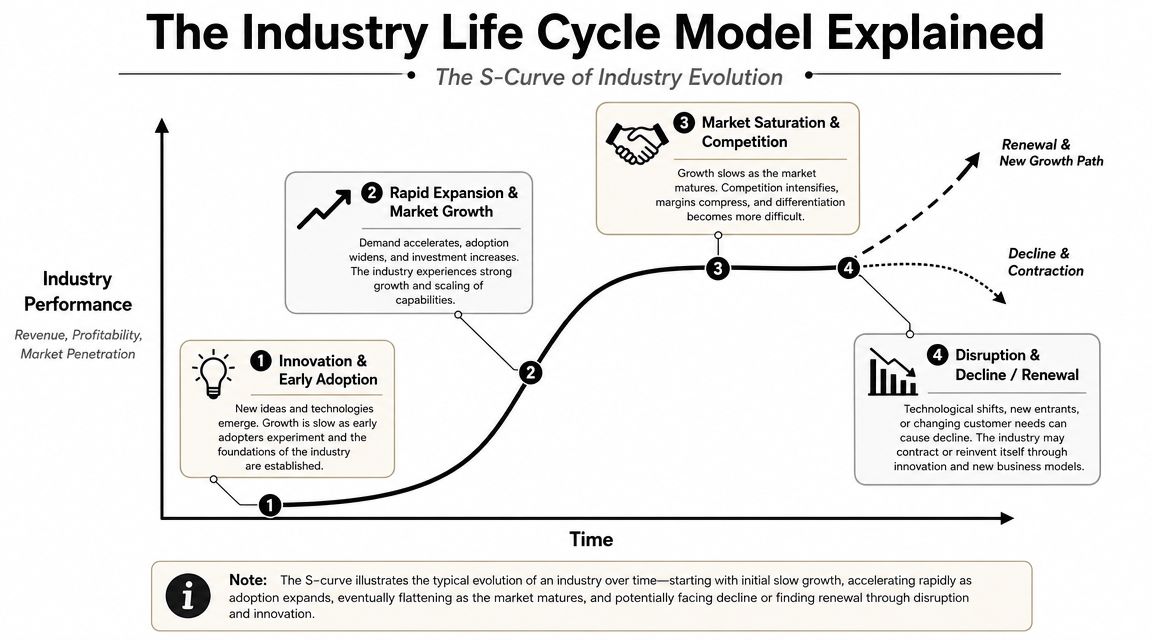
The model is easiest to understand as an S-curve. Early on, adoption is slow because the market is still learning what the product is and why it matters. Then growth accelerates as acceptance improves. Eventually the curve flattens as demand matures, competition intensifies, and differentiation gets harder to sustain. In some industries, the curve then bends downward. In others, renewal creates a second curve.
What the curve actually tracks
The curve isn’t just about sales. It captures the joint evolution of several forces:
- Demand formation changes from uncertain to broad-based.
- Competition moves from sparse participation to crowded entry, then often to consolidation.
- Profitability often starts unevenly, improves during strong expansion, then comes under pressure as standards emerge and rivalry increases.
- Innovation shifts from radical experimentation to more incremental improvements.
That’s why the framework remains one of the most useful tools in strategy. It doesn’t tell you the future with certainty, but it tells you what to watch.
Why the model is often misused
The most common mistake is treating the industry as if it has one clean label. Real markets rarely do. One segment can be in growth while another is already consolidating. One geography may still reward customer acquisition, while another rewards pricing discipline and retention.
That nuance matters. Umbrex notes a key point that many simplified explainers miss: one part of an industry may be in a shakeout while another is still in growth, so strategy should be built on observable indicators like demand growth, competitor count, and profitability rather than a single label for the whole market, as discussed in Umbrex’s industry life cycle model overview.
Stage labels are shorthand. Decisions should come from evidence.
What the model helps you decide
Used well, the life cycle of an industry helps leaders answer three practical questions:
What type of competition matters now
In early phases, the battle is often for adoption and share. Later, the battle shifts toward scale, cost position, and operational consistency.Which metrics deserve attention
Growth industries reward speed and capture. Mature industries reward efficiency and concentration.Which business model assumptions need revision
A pricing model, channel strategy, or partnership structure that worked in growth often weakens in maturity.
The model is powerful because it turns pattern recognition into action. It helps leaders avoid defending yesterday’s position in tomorrow’s market.
The Five Stages of Industry Evolution
A market rarely announces that it has changed stage. The signs show up first in operating decisions. A founder who spent two years winning customers with product education starts losing deals to lower-priced, standardized alternatives. A category leader with strong revenue growth sees margins tighten because distribution power is shifting to a smaller set of scaled competitors. The label matters less than the pattern behind it.
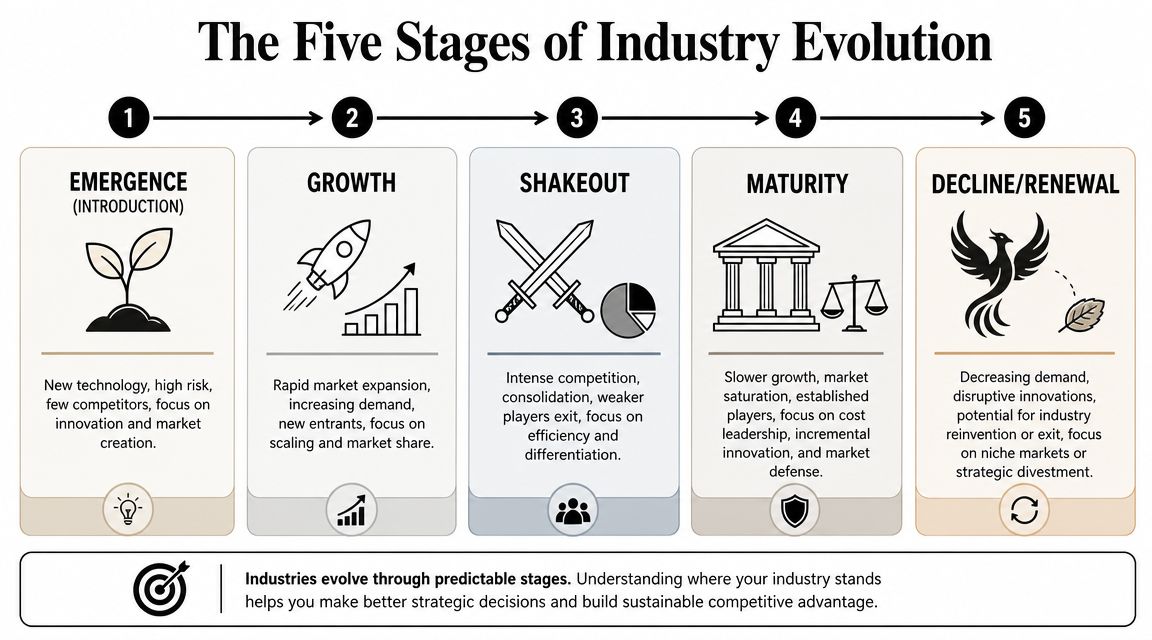
The standard model divides the life cycle of an industry into launch, growth, shakeout, maturity, and decline. For executives, its value is diagnostic. Each stage changes the mix of sensible investments across product, customer acquisition, hiring, pricing, and capital allocation. Leaders who identify that shift early can adjust before weaker economics force the change on them. That is why teams often pair industry stage analysis with tools such as SWOT, the Business Model Canvas, and targeted B2B market research to test whether their assumptions still fit market conditions.
Stage by stage logic
Launch
Launch begins when a new product category or delivery model reaches the market but demand is still unproven at scale. Buyers need education. Product design changes quickly. Distribution is usually fragmented, and customer feedback shapes the offer as much as the original business plan.
The core question is whether a real market exists, not whether the company can scale one yet.
In this stage, leaders should watch adoption quality more closely than volume. Are early customers repeating usage, referring others, and accepting a pricing structure that can support the business later? If the answer is no, top-line growth can create false confidence.
Growth
Growth starts when the market moves beyond early adopters and adoption broadens across segments, channels, or geographies. Revenue expands faster, new entrants arrive, and investors often reward share capture over near-term efficiency. Product improvements still matter, but category legitimacy is no longer the main constraint.
Competition changes here. The battle shifts from proving the category to shaping it. Firms that define customer expectations early often gain advantages in brand, channel access, data, and cost position that persist well after growth slows.
This is also the stage where weak diagnostics cause expensive mistakes. Many management teams treat rapid demand as evidence that every function is working. In practice, growth can hide poor retention, weak unit economics, and fragile positioning.
Shakeout
Shakeout is the sorting phase. Demand may still rise, but it no longer supports the number of competitors that entered during expansion. Exit rates increase. Capital becomes more selective. Customers compare offerings more directly, and weaker firms lose room to compensate for strategic flaws with market momentum.
The winning pattern becomes clearer. Scaled operators benefit from lower acquisition costs, stronger distribution, better supplier terms, or more reliable service. Smaller firms survive by owning a narrow segment, distinctive capability, or local advantage. Everyone else gets squeezed.
A useful video overview of the concept is below.
Maturity
Maturity begins when growth slows, standards stabilize, and buyers see fewer meaningful differences across core offers. Market share becomes harder to win. Profit pools concentrate around operators with scale, disciplined pricing, efficient operations, trusted brands, or privileged channel relationships.
This stage rewards management quality more than category excitement. Marginal improvements in procurement, fulfillment, retention, service levels, and capital productivity often matter more than headline innovation. Innovation still matters, but it usually works best when it improves economics, protects switching costs, or opens adjacent revenue streams rather than trying to remake the entire category.
Decline
Decline sets in when demand weakens structurally, substitutes improve, regulation changes the economics, or value moves to another layer of the chain. Some firms can still earn strong returns, but the logic changes. Growth for its own sake stops being a sensible objective.
The strategic options narrow to three. Harvest cash flows, focus on defensible niches, or redefine the category through renewal. The wrong move is treating decline like a temporary slowdown and continuing to invest as if broad-based expansion will return.
Industry life cycle stages at a glance
| Stage | Sales Growth | Competition | Key Focus | Profitability |
|---|---|---|---|---|
| Launch | Limited and uncertain | Few players | Validate demand, sharpen use case, refine pricing and channels | Uneven |
| Growth | Rapid | Rising entry | Scale operations, build share, strengthen retention and economics | Improving for strong operators |
| Shakeout | Slowing from earlier pace | Intense, then falling as weaker firms exit | Consolidate, differentiate, lower cost to serve, defend viable segments | Pressured |
| Maturity | Slower, more stable | Established rivals | Protect position, improve efficiency, allocate capital with discipline | More dependent on scale and discipline |
| Decline/Renewal | Flat or weakening | Fewer committed players, or new substitutes emerging | Harvest, reposition, specialize, or reinvent | Polarized |
A more useful way to read the stages
A stage model is only useful if leaders can connect it to decisions. The practical test is not whether the market is “early” or “late” in some abstract sense. It is whether the economics of competition are improving, stabilizing, or deteriorating.
A good diagnosis combines several signals. Revenue growth is one. Margin direction, customer acquisition efficiency, retention quality, concentration among top firms, hiring patterns, and capital intensity often reveal more. If demand is still rising but customer acquisition costs climb, weaker firms exit, and buyers increasingly prefer scaled providers, the industry may already be entering shakeout even while headline growth looks healthy. That is the kind of shift executives need to catch early, because strategy usually fails at the turning points, not in the middle of a stage.
A Diagnostic Toolkit to Pinpoint Your Stage
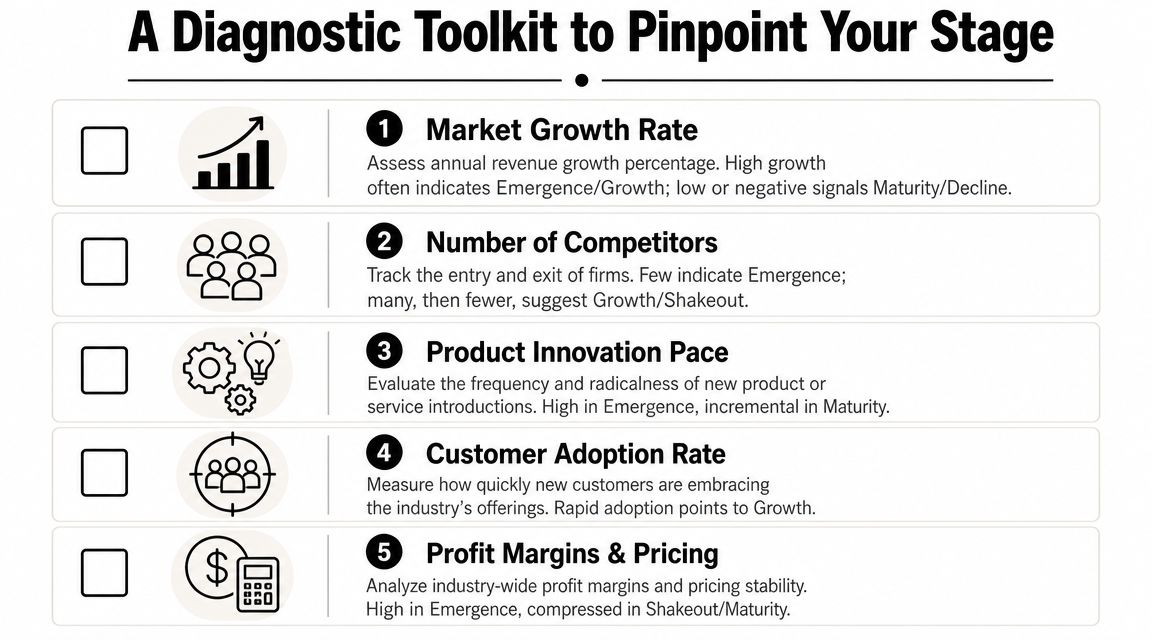
Teams frequently diagnose industry stage by instinct. They say the market “feels crowded” or “still seems early.” That’s not good enough. Stage diagnosis should work like a dashboard, combining external market signals with operating data from finance, marketing, product, and talent.
Start with a multi-metric view
Practitioner frameworks recommend tracking sales growth, user adoption trends, market share, competitive entry and exit, retention, ARPU, churn, burn rate, and recurring revenue to identify stage. The operative question is not solely whether the market is expanding. It’s whether acquisition efficiency and retention are still improving faster than competitive pressure and cost intensity, as outlined in this product life cycle diagnostic framework.
That gives you a better way to read the market.
Finance signals
Look for the pattern, not the point estimate. Are revenue gains still paired with improving unit economics, or is growth now costing more to sustain? If burn stays high while recurring revenue quality weakens, the market may be moving out of expansion.Marketing signals
Watch adoption, share capture, and acquisition efficiency together. Fast adoption with improving retention suggests the category is still being won. Flat share with rising acquisition friction suggests the category is getting harder to penetrate.Competitive signals
Count entrants and exits. New firms pouring in usually signal expansion. A drop in viable competitors, especially after pricing or funding pressure, often points to shakeout.
Add HR and operating evidence
HR data is often ignored in life-cycle analysis, but it’s useful because talent patterns reveal what the market demands.
Consider these questions:
Hiring mix
Are firms still building exploratory product teams and market education roles, or are they hiring for process control, procurement, and account retention?Sales profile
Do top performers win through evangelizing a new category, or through account penetration, contract renewal, and channel optimization?Leadership focus
Is the executive team debating product-market fit and category design, or plant utilization, pricing discipline, and portfolio rationalization?
These aren’t headline metrics, but they often expose stage shifts before annual reports do.
Management shortcut: If your team spends more time discussing efficiency, retention, and utilization than awareness, launch, and first-time adoption, the industry may have already crossed into a later stage.
Build a practical scoring sheet
A useful internal workshop can score the industry on five dimensions:
| Diagnostic area | Early-stage clue | Late-stage clue |
|---|---|---|
| Demand | Adoption still expanding rapidly | Demand stabilizing or fragmenting |
| Competition | New entrants increasing | Exit, consolidation, or concentration rising |
| Product | Frequent meaningful innovation | Mostly incremental upgrades |
| Customers | New customer education still central | Retention and wallet share matter more |
| Economics | Share capture improves returns | Scale and efficiency determine returns |
For teams that need outside input, structured B2B market research can help validate whether your internal view matches what buyers, competitors, and adjacent categories are signaling. The point isn’t to buy certainty. It’s to reduce self-deception.
Strategic Responses for Each Life Cycle Stage
A familiar pattern plays out in boardrooms. A company in a slowing category keeps spending as if demand is still accelerating. Another cuts investment too early in a category that is still opening up. Both teams may understand the life cycle in theory. They lose because they apply the wrong operating model to the stage they are in.
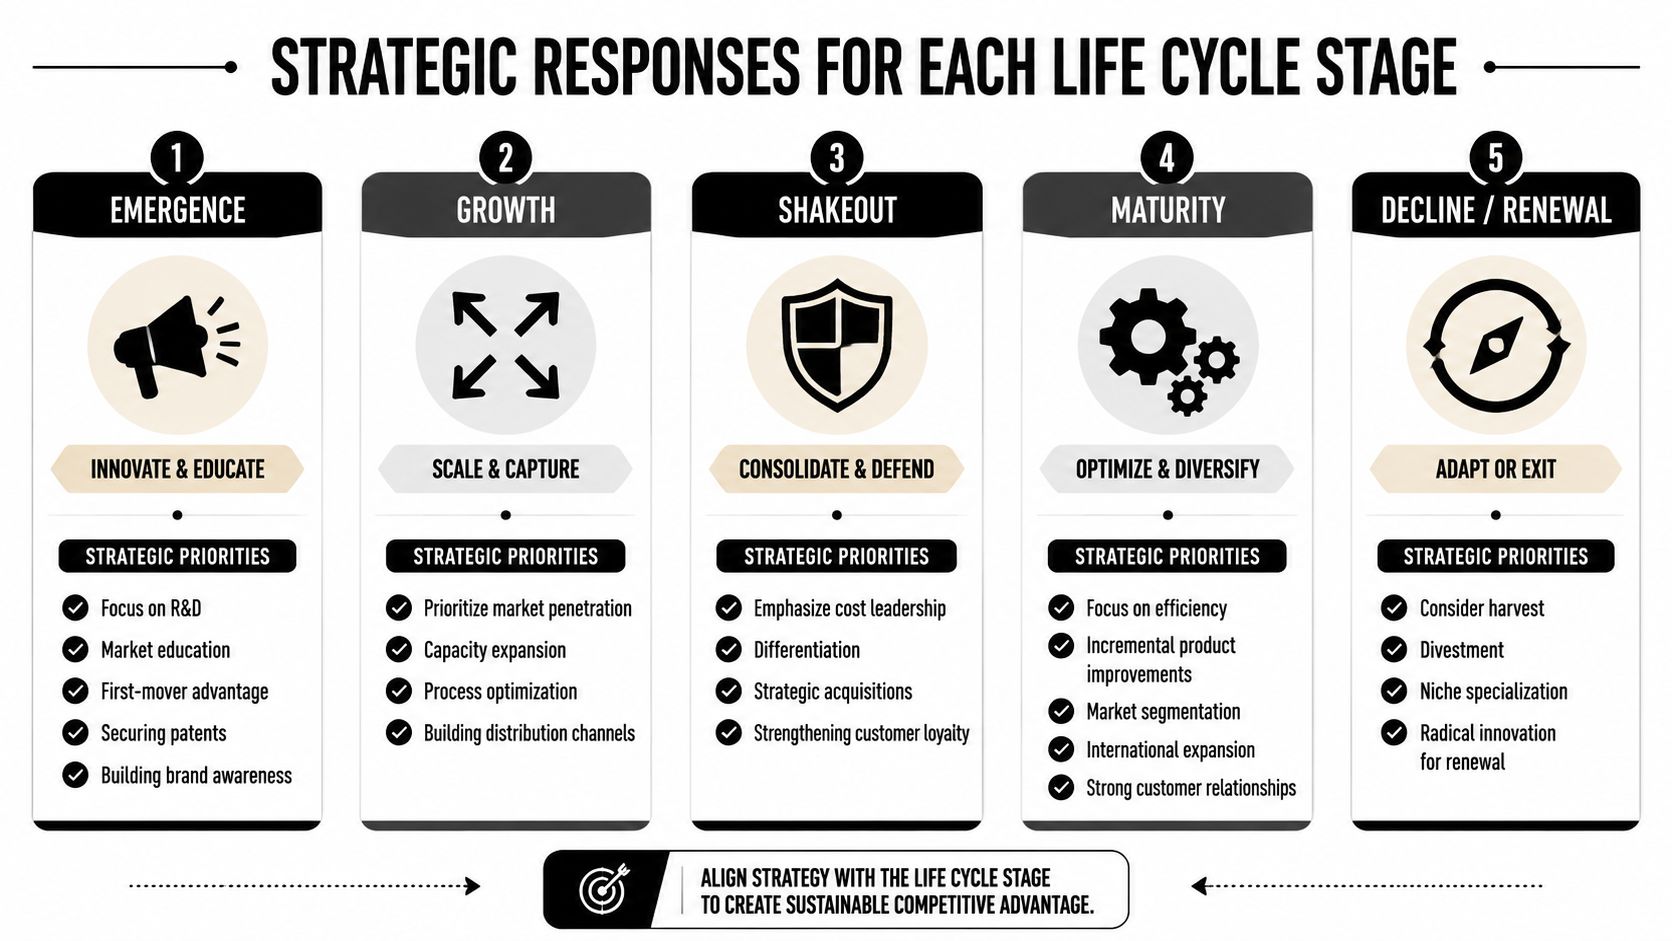
The practical question is simple. Once you have diagnosed the stage, what should change in capital allocation, go-to-market, hiring, and product priorities?
Emergence and growth
In emergence, the main risk is false certainty. Demand exists, but its shape is still unclear. Buyers may not agree on the use case, channels are still forming, and unit economics often look better in pilots than at scale. Leaders should treat the business model as provisional and review assumptions often.
Use the Business Model Canvas in emergence
The Business Model Canvas is useful at this stage because it forces explicit choices about customer segments, value proposition, channels, key partners, and revenue logic. A static canvas has little value. A revised canvas, updated as the team learns, becomes a decision record.
Priority areas usually include:
- Customer discovery to identify who adopts first and why
- Category education when buyers still need help understanding the problem
- Partner selection to build credibility and expand distribution faster
- Cash control because timing risk and strategic pivots are common
Growth requires a different posture. Once adoption starts to build, the constraint shifts from learning to execution. Capacity, distribution reach, onboarding quality, and retention discipline begin to matter as much as product novelty. If you’re trying to evaluate startup performance in a fast-moving category, benchmark frameworks can help distinguish real scaling from top-line growth that masks weak retention or poor contribution margins.
Shakeout and maturity
Shakeout is the stage where strategy gets less forgiving. Demand may still rise, but not fast enough to cover weak economics for every competitor. Firms with high acquisition costs, undifferentiated offers, or inconsistent operations start to fall behind. The winners usually combine cost discipline with a clear position in the segments that still offer profit pools.
Use SWOT in shakeout
A SWOT analysis is effective here because it forces a blunt comparison between internal capabilities and external pressure. In a shakeout, optimism is expensive.
Useful questions include:
- Are your costs low enough to withstand pricing pressure?
- Is your offer distinct enough to avoid direct commoditization?
- Do you have the balance sheet and management capacity to acquire weaker rivals?
- Which customer segments still justify investment, and which ones now dilute returns?
Many founders also need a more formal framework for business strategy for entrepreneurs at this point. The company is no longer choosing only how to grow. It is choosing where to defend, where to exit, and where to concentrate resources.
Use operating discipline in maturity
Maturity changes the basis of competition. Growth slows, customer expectations stabilize, and margin performance depends more on execution than novelty. That shifts management attention toward pricing discipline, service reliability, procurement, utilization, retention, and capital allocation.
The strongest moves in maturity often include:
- Segmenting the market to identify defendable pockets of value
- Improving utilization and process efficiency to protect margins
- Extending the offer through bundles, services, or adjacent revenue streams
- Protecting the installed base through switching costs, account depth, and renewal systems
Mature industries still produce strong returns. They reward firms that make ordinary activities harder to copy.
Decline and renewal
Decline demands sharper choices, not automatic retreat. Some categories are structurally shrinking. Others are transferring value to a new layer of the stack, a new channel, or a new customer need. Leaders who fail to separate those two situations often either harvest too early or invest in a business that no longer has a future.
A PESTLE analysis helps because decline is often driven by external shifts, including regulation, technology change, channel migration, cost inflation, or altered buyer behavior. The strategic options are then clearer. Harvest cash where the core is fading. Specialize where a niche still supports attractive economics. Rebuild around a new service, platform, or use case when the old product logic no longer fits the market.
The central discipline is matching the response to the stage before competitors do. Firms rarely fail because the life cycle is unknowable. They fail because they keep using yesterday’s playbook.
Case Studies From Introduction to Renewal
A modern way to see the life cycle of an industry is to look across categories that are moving at different speeds at the same time. That matters because life-cycle timing isn’t just historical. It’s operational.
Introduction and growth in today’s markets
Early generative AI tools are a good example of introduction logic. Buyers are still learning which use cases matter, vendors are still refining the product, and market education remains central. The winners won’t just have strong models. They’ll have a repeatable business model, clear adoption paths, and enough flexibility to adjust as the category definition settles.
Electric vehicles illustrate many traits of growth. Demand expansion, new entrants, fast product iteration, and large bets on capacity all fit the pattern. But even here, subsegments can diverge. Premium models, mass-market fleets, charging infrastructure, and software layers don’t all move in lockstep.
Shakeout and maturity in familiar categories
Consumer delivery platforms show what shakeout can look like. Early expansion invited many competitors. Later, cost pressure, funding realities, and local scale economics made survival harder. The category still exists, but not every participant can justify independent operation.
Smartphones are closer to maturity. Product innovation still matters, but many battles now revolve around ecosystem lock-in, installed base defense, service attachment, and supply-chain execution. In other words, advantage sits less in category creation and more in control of the surrounding system.
A mature category can still contain early-growth profit pools if value shifts from the product to services, software, or distribution.
Decline and renewal in legacy sectors
Print media offers the clearest decline and renewal contrast. The legacy print layer weakened as audiences and advertising moved elsewhere. But the story didn’t end there. Some publishers rebuilt around subscriptions, niche authority, digital communities, and platform-based distribution.
That pattern matches an important insight from academic work on industry transitions: life cycles can be disrupted or extended by downturns, regulation, and structural change, and recent transitions are shaped by value migration, where profits move from product to service or from traditional channels to platforms, as discussed in this analysis of stagnant and declining businesses.
If you study these transitions, a useful companion resource is this collection on business model evolution. It helps explain why some firms disappear with a declining layer while others reposition into the next one.
Using the Life Cycle as a Strategic Map
The life cycle of an industry isn’t a label to apply after the fact. It’s a map for resource allocation before the market forces the issue.
The practical sequence is straightforward. First, diagnose the stage with evidence rather than intuition. Second, identify whether the whole industry is moving together or whether different segments sit at different points on the curve. Third, match strategy to stage. That means learning and adaptation in launch, capture and capacity in growth, consolidation in shakeout, efficiency in maturity, and hard choices about reinvention or exit in decline.
Leaders who use the model well don’t ask, “What stage are we in?” and stop there. They ask better questions. Which metrics now matter most? Where is value leaving the old layer and forming in the new one? Which capabilities become more valuable if the market slows? Which assumptions in our business model expire before our product does?
That’s the primary use of the framework. It helps executives act before financial statements make the shift obvious.
The Business Model Analyst offers strategy content and tools that can help teams apply frameworks like the Business Model Canvas, SWOT, and business model evolution to real market decisions. If you’re trying to turn industry-stage insight into a clearer strategic response, The Business Model Analyst is a practical place to continue.