
Revenue rose 21% to DKK 41.9 billion on Formula 1, the World Cup and Pokémon. Then Lego turned a 26% operating margin into a 5% free cash flow margin, on purpose.
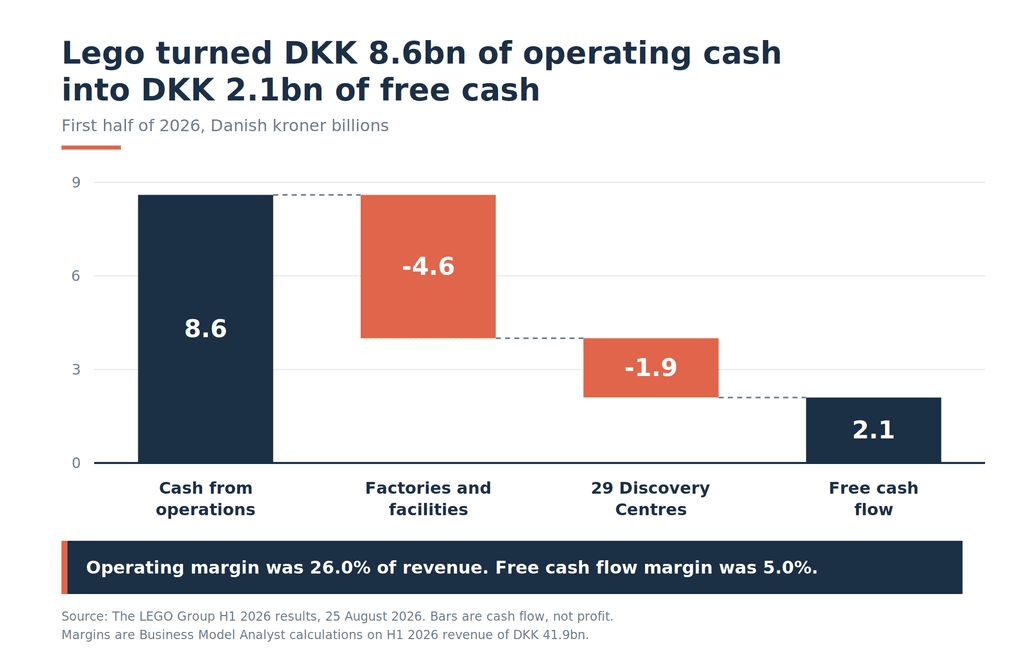
Lego’s first half of 2026 was its best ever, with revenue up 21% to DKK 41.9 billion (about $6.5 billion) and net profit up 32% to DKK 8.6 billion. Most of the demand came from intellectual property Lego does not own. The interesting part is what happened next: Lego spent DKK 4.6 billion on factories and another DKK 1.9 billion buying 29 Discovery Centres back from Merlin Entertainments, leaving only DKK 2.1 billion of free cash. That is the business model in one cash flow statement. Lego rents the characters and owns everything that turns them into money.
Back in March, Lego told the world that 2026 would be a quiet year. Single-digit revenue growth. Net profit roughly flat against 2025. Heavy spending on sustainability and digital would eat the difference.
Five months later the company reported the strongest half in its 94-year history, beating its own forecast on both lines by a mile. When a private company misses its guidance by that margin, there is no share price to punish and no analyst to answer to. There is only the question of what it actually bought with the money.
What Happened
On 25 August 2026, Lego reported first-half revenue of DKK 41.9 billion, up 21% from DKK 34.6 billion a year earlier. In constant currency, growth was 26%, meaning a stronger krone shaved five points off the headline. Consumer sales, which measure what shoppers actually paid at the till, rose 22%.
Operating profit climbed 22% to DKK 10.9 billion. Net profit rose 32% to DKK 8.6 billion, up from DKK 6.5 billion. Cash from operations jumped 47% to DKK 8.6 billion.
The company launched more than 330 new products in six months, another record. Bestselling themes were a mix of homegrown and licensed lines: Speed Champions, Botanicals, Technic, Icons and Star Wars. CEO Niels B Christiansen credited Formula 1, the FIFA World Cup 2026 and KPop Demon Hunters for the demand spike, plus a new Pokémon partnership and the launch of SMART Play, a sensor-based platform that so far appears in Star Wars and Pokémon sets.
Headcount is now around 34,000. The branded store estate stands at 1,106 locations.
And then the spending. Lego put DKK 4.6 billion into factories and facilities, including the new Virginia plant and distribution centre due to open in 2027, and the newly opened Kornmarken Campus in Billund. It put another DKK 1.9 billion into buying 29 LEGO and LEGOLAND Discovery Centres from Merlin Entertainments, sites that draw around five million visitors a year. Free cash flow landed at DKK 2.1 billion.
The Backstory
Lego has been the world’s largest toy company by revenue for years, and it is not close. Full-year 2025 revenue was DKK 83.5 billion with operating profit of DKK 22.0 billion, a 26.4% operating margin and a 20% net margin. Return on equity was 36.7%. Mattel and Hasbro combined do not reach that profit pool.
It has also been quietly winning share for a decade. In 2025, consumer sales grew 16% against a global toy market that grew 7%. That is a company outgrowing its category by more than two to one.
The category has now woken up. Circana put global toy value sales up 14% in the first half of 2026, the fastest pace in years, against 9.5% for the trailing twelve months. In the US, dollar sales rose 17%, the strongest first half in six years, with unit volumes up 12% and average selling prices up 4%. The buyers driving it are not children. Adult-only households accounted for 55% of US toy sales, and adults plus teens generated close to 60% of the industry’s dollar gains.
That is the market Lego just grew 22% into. It is worth sitting with, because it changes what the headline number means.
The Plan
Read the release as a spending plan rather than a sales report and it gets clearer.
Lego is building a factory and a regional distribution centre in Virginia, both due in 2027. It opened Kornmarken Campus in Billund in June, a 100,000 square metre manufacturing innovation centre housing more than 1,800 people whose job is to develop and scale new production technology. It started construction on its largest solar park to date, 160,000 panels producing 99 GWh a year, sized to match the company’s electricity needs in Billund.
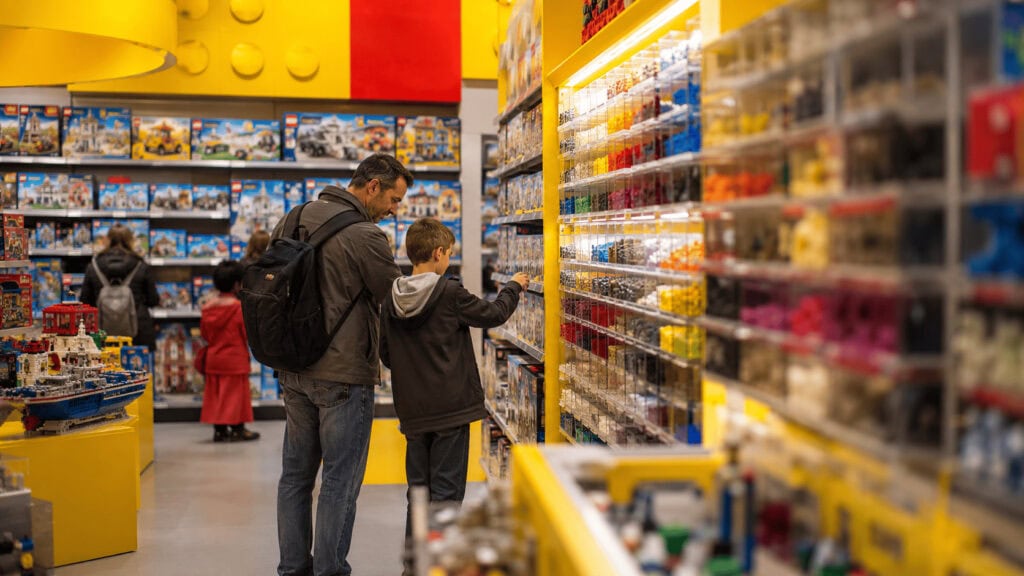
And it bought the Discovery Centres. Those are the indoor, mall-scale LEGO attractions, distinct from the full LEGOLAND parks. Until this year they were run by Merlin Entertainments under licence. Now Lego runs them itself.
Every one of those line items is Lego paying cash to own a link in its own chain that it previously rented or did not control: the molds, the plant, the power, the venue.
Meanwhile, on the demand side, it did the opposite. It rented Formula 1. It rented the World Cup. It rented Pokémon, Star Wars and a Netflix animated musical about K-pop demon hunters.
The Business Model Angle
Here is the tension worth naming. Lego’s growth engine in H1 2026 ran mostly on characters and properties owned by other people, and licensing normally costs you margin. Royalty rates in toys typically run in the high single digits to low teens of wholesale. Every competitor bidding for the same hot property pays roughly the same rate.
So why did Lego’s licensed-heavy half arrive at a 26.0% operating margin, statistically identical to the 26.0% it earned in the first half of 2025?
Because the royalty is only one input, and Lego owns almost all the others. It designs the set. It molds the brick in its own factories. It ships through its own distribution network. It sells through 1,106 branded stores, its own website, and retail partners it has spent decades training. When a license lands, Lego captures the design margin, the manufacturing margin and a growing share of the retail margin. A competitor who outsources molding to a contract manufacturer in Asia and sells through Walmart captures one of the three.
That is why Lego can bid for the same license as everyone else and still be the highest-value home for it. The licensor gets more money from Lego because Lego generates more revenue per license than anyone else, across a price ladder that runs from a $30 starter set to a $250 collector build off the same property. The royalty rate is the same. The base it applies to is not.
Which reframes what the H1 2026 spending is actually for. The DKK 6.5 billion that went into factories and Discovery Centres is not a side project or a sustainability line item. It is Lego buying more of the chain that makes borrowed IP profitable. Owning the conversion layer is the moat. The characters are rented, and rented characters are fine when you own the factory.
Two computed figures worth holding onto:
The Discovery Centres cost roughly DKK 65 million each, or about $10.2 million per site. Against roughly five million annual visitors across the 29 locations, Lego paid about DKK 380 per annual visitor, somewhere near the price of one family’s admission. For a brand where the physical experience is the marketing, that is not an expensive way to stop paying a licensee to represent you.
The margin-to-cash gap is the real story. Lego earned 26.0 cents of operating profit on every krone of revenue and kept 5.0 cents of free cash. Capital expenditure alone ran at 11.0% of revenue. A public company printing a 26% operating margin would face relentless pressure to return most of that cash. Lego, owned 75% by KIRKBI and 25% by the LEGO Foundation, converts it into owned capacity instead. Same margin, entirely different destination.
The Risk
The market did a lot of the work this time. In 2025, Lego grew consumer sales at 2.3 times the toy market’s rate. In H1 2026, it grew at 1.6 times. The absolute growth number got bigger and the relative outperformance got smaller. Lego is now surfing a category-wide adult-collector boom rather than defying a flat market, and booms in collectibles have a way of ending abruptly.
The bottom line grew faster than the business. Operating profit rose 22%. Net profit rose 32%. That ten-point gap sits below the operating line, in a half where currency was a five-point headwind on revenue. Half-year releases carry no notes, so the composition of that gain, whether hedging, financial income or tax, is not disclosed. Anyone treating the 32% as underlying earnings growth is guessing.
The Merlin purchase has a family in the middle of it. KIRKBI owns 75% of the LEGO Group. KIRKBI also owns 50% of Merlin Entertainments, a stake it took to that level in the 2019 take-private alongside Blackstone and CPPIB. So Lego paid DKK 1.9 billion of shareholder cash to a business half-owned by its own controlling shareholder. That may well be a fair price for a strategic asset. It is also a transaction with nobody independent on the other side of the table, and no minority investors to ask.
Owned distribution is thinner than 1,106 suggests. Lego’s own 2025 breakdown put roughly 800 of about 1,100 branded stores in the Certified Store category, meaning they are operated by retail partners rather than by Lego. The estate is branded. It is not all owned.
And the capex lands into an unknown second half. Lego guided to a soft 2026 in March and then beat it by twenty points. Either Billund set the bar deliberately low, or the second half comes in materially weaker against a tough comparison base. The factories in Virginia open in 2027 regardless.
Quick Questions
Is Lego publicly traded? No. Lego A/S is privately held, owned 75% by KIRKBI A/S, the Kirk Kristiansen family’s investment vehicle, and 25% by the LEGO Foundation. There are no shares to buy.
How much of Lego’s business is licensed IP? Lego does not break out licensed versus homegrown revenue. The H1 2026 bestseller list mixed both, with Speed Champions, Botanicals, Technic and Icons alongside Star Wars, and the named growth drivers were Formula 1, the FIFA World Cup 2026, KPop Demon Hunters and a new Pokémon partnership.
Why is free cash flow so much lower than profit? Because Lego spends heavily on physical assets. In the first half of 2026 it put DKK 4.6 billion into factories and facilities and DKK 1.9 billion into acquiring the Discovery Centres, consuming about 76% of its operating cash flow.
What did Lego buy from Merlin Entertainments? Twenty-nine LEGO and LEGOLAND Discovery Centres, the indoor attraction format, for DKK 1.9 billion. They attract around five million visitors a year. The full LEGOLAND parks remain within Merlin.
Did Lego beat its own guidance? Comfortably. In March 2026 the company projected single-digit revenue growth and net profit in line with 2025. The first half delivered 21% revenue growth and 32% net profit growth.
The Business Model Analyst Take
The easy read on this half is that Lego is unstoppable and the brand sells itself. That read misses the trade.
Lego made a specific bet a long time ago and doubled down on it this half: give up owning the story, keep owning the object and the path it travels. Disney owns Star Wars and collects a royalty. Formula 1 owns the grid and collects a fee. Lego owns the mold, the plant, the power supply, the box on the shelf and now the room the kid walks into at the mall. In an industry where hit properties rotate every eighteen months, the durable asset is not the character. It is the machine that can turn any character into a product at 26% margins within a season.
The version of this you can steal is simple. When your growth depends on inputs you rent, spend your profits buying the parts of the chain that make those inputs worth more in your hands than in anyone else’s. That is what a moat looks like when you do not own the IP.
The version you should be careful about is the guidance. A company that told its own people to expect a flat year, then printed a record, is either sandbagging or about to have a hard second half. Lego has committed to the factories either way.