
Every wire priced Tuesday’s offer as an AI data center trade. UGI’s own filings, and KKR’s last three deals, describe a propane roll-up.
KKR has offered $42.50 a share for UGI Corporation, about $9 billion of equity and roughly $15 billion once you count the debt. The coverage explained it with data centers and natural gas. The more useful explanation sits in the buyer’s calendar. Three weeks before this bid, KKR agreed to buy DCC Energy. For the previous nine months, UGI had been selling its European propane businesses to DCC. The AI story is what makes the price defensible to a limited partner. The propane routes are what make KKR, specifically, the buyer.
Here is the part that should have led every story about this deal. On October 21, 2025, UGI International agreed to sell its Austrian liquid gas business to DCC for an enterprise value of 55 million euros, and handed DCC its AvantiGas cylinder business in Britain on the same day. On January 15, 2026, it agreed to sell its LPG operations in the Czech Republic, Hungary, Poland and Slovakia to DCC for about 48 million euros. UGI booked a $64 million non-cash impairment on the Central European assets on the way out. Those five businesses closed into DCC by late May. On April 29, KKR and Energy Capital Partners made their first approach to DCC. On July 27, they agreed to buy it. On August 18, KKR bid for the company that had been feeding it.
What Happened
KKR proposed $42.50 a share in cash. UGI closed Monday at $35.09, which puts the premium at 21.1% and the equity check at roughly $9.1 billion against about 214.7 million shares outstanding. The stock jumped as much as 14% on Tuesday and was briefly halted for volatility at $37.20. Its 52-week range going in was $31.62 to $41.34, so the offer sits above anywhere the shares have traded in a year.
The $9 billion headline is the equity, not the price of the asset. UGI carried $6.839 billion of long-term debt including current maturities at March 31, 2026, against $523 million of cash and restricted cash at June 30. Net that out and the enterprise changing hands is closer to $15 billion. Corporate leverage stood at 3.8 times at the end of June. AmeriGas sat at 4.3 times on its own.
There is no deal. UGI has not said whether it will engage, KKR declined to comment, and an unsolicited proposal reported by a newspaper is a long way from a signed merger agreement.
One detail the headlines got wrong on their own terms. UGI is described everywhere as a natural gas and electricity distributor. It agreed on April 28 to sell its entire electric division to Argo Infrastructure Partners for about $470 million: 2,700 miles of transmission and distribution line, 14 substations and more than 63,000 customers in Luzerne and Wyoming counties, closing in the first quarter of calendar 2027. The electricity half of the headline is already under contract to someone else.
The Backstory
UGI spent fiscal 2026 telling investors it was simplifying. Julie Fazio, who runs UGI International, framed the European exits as concentrating on “markets where we have the strongest competitive positions.” The European footprint went from 15 countries to 14, and retail volumes from roughly 875 million gallons in 2024 to roughly 820 million in 2025. Management cut its fiscal 2026 earnings guidance in May, from $2.90 to $3.15 a share down to $2.75 to $2.90, and reaffirmed the lower range on August 5.
Read forward, that is a tidy-up. Read backward from Tuesday, it is a pre-sale inventory clean, and the buyer of the discarded inventory is now the buyer’s sibling.
DCC’s side of the ledger is worth understanding, because it explains what KKR just bought. DCC Energy runs Flogas in Britain, Ireland, Sweden and Norway, Butagaz in France, Benegas in the Benelux and Tega in Germany. In the United States it describes itself as the country’s seventh-largest propane provider, operating in 21 states with more than 900 employees. For the year to March 2026 it produced £634.0 million of adjusted continuing operating profit on £15.4 billion of revenue, a 16.8% return on capital employed and 108% free cash flow conversion, with energy volumes down 3.2%. KKR and ECP chased it from £4.95 billion in April to £5.75 billion in July. Ryan Miller, a managing director in KKR’s infrastructure arm, said delivering the next phase would take “significant operational transformation.”
Now line the two companies up. AmeriGas is the largest retail propane distributor in the United States, serving more than 1.7 million customers in all 50 states from roughly 1,900 locations. DCC Propane is number seven. In France, UGI owns Antargaz and DCC owns Butagaz, and each has at various points been described as the country’s second-largest LPG supplier. DCC paid Shell 464 million euros for Butagaz in 2015, the same year UGI bought Totalgaz.
The Plan
If both deals complete, KKR ends up holding the largest propane distributor in America, the seventh largest, two of the three companies that matter in French bottled and tank gas, and five European businesses UGI sold to DCC for about 103 million euros before anyone knew who would end up owning them.
That is not an AI thesis. That is a consolidation thesis in a shrinking category, and it is the oldest play in private equity.
KKR does not need UGI for AI power. It built a dedicated vehicle for that in June, Helix Digital Infrastructure, alongside the Kuwait Investment Authority, Nvidia and Vistra, with more than $10 billion committed. It bought EDF’s North American power development business the same month for about $4.2 billion of equity. It put insurance money into Williams’ behind-the-meter power projects in July. KKR manages $758 billion. When it wants exposure to data center electricity, it has already shown you exactly what that purchase looks like, and it does not look like a propane truck fleet in Pennsylvania.
The Business Model Angle
Propane delivery is a route business. The truck drives whether the tank at the end of the street gets filled or not, so the cost that matters is cost per stop, and cost per stop falls as customers per mile rises. Density is the entire margin structure.
UGI’s June quarter shows what happens when density goes the wrong way. AmeriGas retail gallons fell 10%. Total margin fell $26 million. Operating and administrative expenses moved by exactly zero dollars, holding at $220 million. Segment EBIT went from a $28 million loss to a $53 million loss. Weather-adjusted and excluding a Hawaii disposal, volumes were still down 6%. UGI even raised AmeriGas capital spending 35% in the quarter, to $27 million, into that.
That is not a bad quarter. That is the arithmetic of a fixed network serving a declining category, and no operating improvement fixes it, because the cost is in the geography rather than the management. You cannot cut your way to density. You can only buy it.
Which is the whole point. A shrinking distribution business is worth ordinary money to a financial buyer and unusual money to a buyer who already owns the routes on the next road over, because that buyer can merge two half-empty routes into one full one. AmeriGas is worth more to whoever owns DCC Propane than to anyone else in the world. Right now that is going to be KKR.
Compare that with the half of UGI everyone is talking about. The Utilities segment serves roughly 700,000 customers across 45 Pennsylvania counties and is targeting 9% or better rate base growth through 2029 on a $1.7 billion capital program, with a settled $65 million Pennsylvania rate increase pending commission approval. It is a fine asset. It is also an asset with no synergy available to anyone, because a regulated utility earns a set return on the capital it deploys and owning a second one in another state does not change that. You cannot roll up a rate base. You can only fund it.
So the segment that justifies the headline is the segment where KKR has no edge, and the segment nobody wrote about is the one where its edge is unique. That inversion is the story.
The Risk
The overlap that creates the value is the same overlap a regulator gets to examine. In France, Antargaz and Butagaz sit alongside Primagaz at the top of a highly concentrated tank propane market, and there is precedent: when UGI bought Totalgaz in 2015, the French competition authority cleared it only on condition that UGI give up its interests in several LPG import and storage depots. Britain has a Flogas and an AvantiGas problem of its own now. American propane is fragmented enough nationally that a first plus seventh combination is not automatically a federal issue, but AmeriGas has been to this rodeo: it settled FTC charges in 2014 over coordinating a cylinder fill reduction with Ferrellgas, when the two controlled roughly 80% of the wholesale exchange tank market.
The utility needs Pennsylvania Public Utility Commission approval for a change of control, and state commissions have historically extracted conditions from private equity buyers of regulated assets. Leverage is the other problem. AmeriGas is already at 4.3 times, and buyout structures do not usually take leverage down.
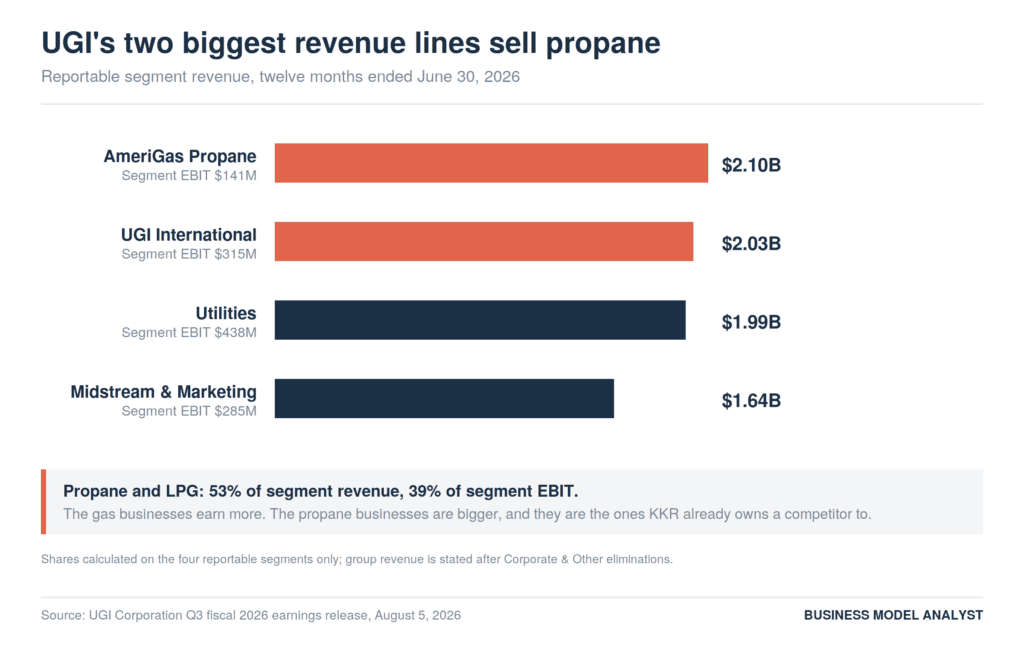
And the honest counterargument deserves room, because it is not weak. UGI’s gas businesses do earn 61% of segment EBIT. Bob Flexon pointed in the August earnings release to “load growth from data centers and power generation.” The Prime Data Centers partnership announced in May contemplates more than 100,000 dekatherms a day within three to five years, roughly 36 billion cubic feet annually against 378 billion of total gas utility throughput in fiscal 2025, with UGI keeping about 15 billion cubic feet of storage and the mineral rights. Marcellus gas under a Pennsylvania rate base is a real asset in 2026, and it may be most of why $42.50 rather than $38 is the number. The claim here is narrower than “the AI story is fake.” It is that the AI story explains the price and the propane explains the bidder.
Quick Questions
Is this a done deal? No. It is an unsolicited proposal reported by a newspaper. UGI has not indicated whether it will engage.
Why $9 billion for a $7.5 billion company? The $9 billion is the equity at $42.50 a share. Add roughly $6.3 billion of net debt and the enterprise is closer to $15 billion.
Doesn’t UGI make most of its money from gas? Yes. Utilities and Midstream produced 61% of segment EBIT in the twelve months to June. Propane and LPG produced 53% of segment revenue, and they are the only parts where owning DCC changes what the assets are worth.
Is propane actually declining? Retail gallons fell 10% at both AmeriGas and UGI International in the June quarter, though the international drop was mostly divestitures. AmeriGas was down 6% weather-adjusted excluding a disposal.
Could regulators block it? France is the obvious pressure point, and there is a 2015 precedent for conditions on exactly this pair of companies’ overlap.
The Business Model Analyst Take
The reliable tell in any takeover is not what the acquirer says it wants. It is what the acquirer already owns.
Every buyer arrives with a narrative, and in 2026 the narrative is always electricity. It works because it is partly true, it prices well with investment committees, and it lets a bid for a gas utility founded in 1882 read as a growth story instead of a value story. But narratives explain price. Portfolios explain buyers. KKR’s portfolio, as of three weeks ago, contains a propane business on two continents that is short exactly the density AmeriGas and Antargaz would supply.
There is a lesson in this for anyone running a business with a shrinking top line, and it is more encouraging than it looks. UGI spent a year being punished for a portfolio the market could not value, trading flat while the S&P added 20%. The volumes were falling. The cost base would not move. And the thing that finally repriced the company was not a turnaround. It was the arrival of a buyer for whom the same declining assets were worth more than they were worth to the market, because he already owned the piece that made them fit.
That is the second use of a melting asset. The first is to run it. The second is to be the last one holding it when the routes consolidate. Both are legitimate businesses, and they are not the same business, and a board that does not know which one it is in will keep optimizing a portfolio it should be selling. UGI, to be fair to Bob Flexon, appears to have known. It just sold the pieces one at a time to the company that was about to become its bidder.