
The $9.6 billion price is an NFL record. It is also a venture capital bet, and the payoff date is 2029.
A group led by Vinod Khosla has agreed to buy the Seattle Seahawks for $9.612 billion, the highest price ever paid for an NFL franchise. Against the team’s most recent estimated operating income of $143 million, that is roughly 67 times earnings and about 15 times revenue. Nobody buys a football team on cash flow. Khosla is buying an option on what the NFL’s media rights are worth after 2029.
Three days ago, Vinod Khosla sat down with The Wall Street Journal and explained that his entire investing method is about option value: make bets where the downside is capped and the upside is enormous, and let asymmetry do the work. Then he went out and made a $9.6 billion one. The Seahawks deal looks like a trophy purchase. Read the multiples and it is something stranger, and more interesting.
What Happened
The Khosla family has agreed to purchase the Seattle Seahawks from the estate of Microsoft co-founder Paul Allen. Terms were not officially disclosed, but multiple league sources put the price at $9.612 billion, a record for an NFL franchise and the second-highest price ever paid for an American sports team.
The deal is subject to approval by NFL owners, who have been asked to hold a date in late August for a special meeting. As a condition, the Khosla family must give up the 3.1% stake in the San Francisco 49ers it bought in 2025 at a valuation above $8.5 billion. League rules do not allow ownership positions in two clubs.
Khosla, the founder of Khosla Ventures and co-founder of Sun Microsystems, has a net worth of roughly $13.8 billion. His firm was the first venture investor in OpenAI and wrote early checks into DoorDash, Stripe, and Instacart. He has never operated a sports franchise.
The Backstory
Paul Allen bought the Seahawks in 1997 for $194 million and kept them in Seattle after the previous owner tried to move the team to Southern California. That $194 million turned into $9.612 billion, a 49.5x return over 29 years. Compounded, it works out to about 14.4% a year, comfortably ahead of the long-run average return of the S&P 500, and Allen also got three decades of owning a football team.
Allen died in 2018. His sister Jody has run the franchise as executor of the trust, under a directive to sell both the Seahawks and the NBA’s Portland Trail Blazers and route the proceeds to charity. NFL rules do not permit estates and trusts to hold equity indefinitely, so the sale was always coming. The timing was the variable.
Two things fixed it. A provision tied to the 1997 public financing of Lumen Field required 10% of any gross sale price to be shared with the state if the team sold before May 2025. That clock ran out. Then, in February, the Seahawks beat the New England Patriots to win the Super Bowl. The sale process was announced within weeks. Selling a champion is not sentimental, it is optimal.
The Plan
Khosla’s group has said almost nothing about strategy beyond the standard language about stewardship and the Allen legacy. The composition of the investor group has not been disclosed.
What is knowable is the asset. The Seahawks generated an estimated $624 million in revenue and $143 million in operating income in the 2024 season, with roughly $433 million of the average NFL team’s revenue arriving from the league’s shared national pool of media, sponsorship, and merchandise money. Lumen Field is one of the league’s better home-field assets and took nearly $20 million in upgrades ahead of the 2026 World Cup. John Schneider and Mike Macdonald are widely rated as one of the strongest general manager and head coach pairings in football.
In other words, Khosla is not buying a turnaround. There is very little for a new owner to fix, which is unusual, and which is part of why the price is what it is.
The Business Model Angle
Here is the part most coverage will skip. An NFL franchise is not really an operating business. It is a claim on a shared revenue pool with a fixed number of units.
| Metric | Seahawks (2024 season) |
|---|---|
| Estimated revenue | $624M |
| Estimated operating income | $143M |
| Sale price | $9.612B |
| Price to revenue | 15.4x |
| Price to operating income | 67.2x |
| Forbes valuation, Aug 2025 | $6.7B |
| Premium to that valuation | 43% |
Sixty-seven times earnings is a growth-software multiple attached to a business whose product is 20 football games a year. That only makes sense if you believe the revenue line is about to move sharply.
The case that it will: the NFL’s national media agreements locked in about $125.5 billion over a decade, currently worth roughly $12.4 billion a year, and the league can opt out of most of those deals in 2029. Live sport is the last piece of television that cannot be time-shifted, skipped, or replaced by an algorithm, and the bidders are no longer just networks. Netflix has already turned NFL games into its most-streamed events and is building live sport into its ad business. Fox just spent $22 billion buying Roku to own the distribution layer under its sports rights. Amazon, YouTube, and Apple all have balance sheets that make the current NFL contracts look cheap.
Every dollar of that reset gets divided 32 ways, automatically, with no product development, no sales team, and no execution risk on the owner’s part. That is the actual asset. Supply is fixed at 32 units and has not increased since 2002. Demand now includes private equity, which the league began admitting in 2024 with stakes capped at 10%, and which put a permanent bid under franchise valuations. Khosla is not paying 67 times earnings for 2026 earnings. He is paying for a call option on 2030, and option value is the thesis he has spent forty years selling.
The Risk
The bet has three soft spots.
The first is that the 2029 reset is already in the price. Everyone can read the same media contracts. If franchise valuations have priced a rich renewal and the renewal merely matches expectations, Khosla has bought a bond yielding 1.5% with an enormous entry fee.
The second is that live sport is a hedge against cord-cutting only until the streamers stop competing with each other. Consolidation in distribution, the Fox and Roku deal being the template, means fewer bidders at the next auction, not more. Scarcity works both ways.
The third is that the illiquidity is real. A 3.1% limited-partner stake in the 49ers is a financial instrument. Control of an NFL club is a 30-year commitment with a league office attached, and Khosla, who signed the Giving Pledge and has said out loud that capital gains should be taxed like ordinary income, now owns the most conspicuously appreciating asset class in America.
Quick Questions
Is the sale final? No. It requires approval from NFL owners, expected at a special meeting in late August.
Why must Khosla sell his 49ers stake? NFL rules prohibit holding equity in two franchises. He and his son bought 3.1% of the 49ers in 2025 at a valuation above $8.5 billion.
Where does the money go? Paul Allen’s estate is directed to donate sale proceeds to charity under his Giving Pledge commitment.
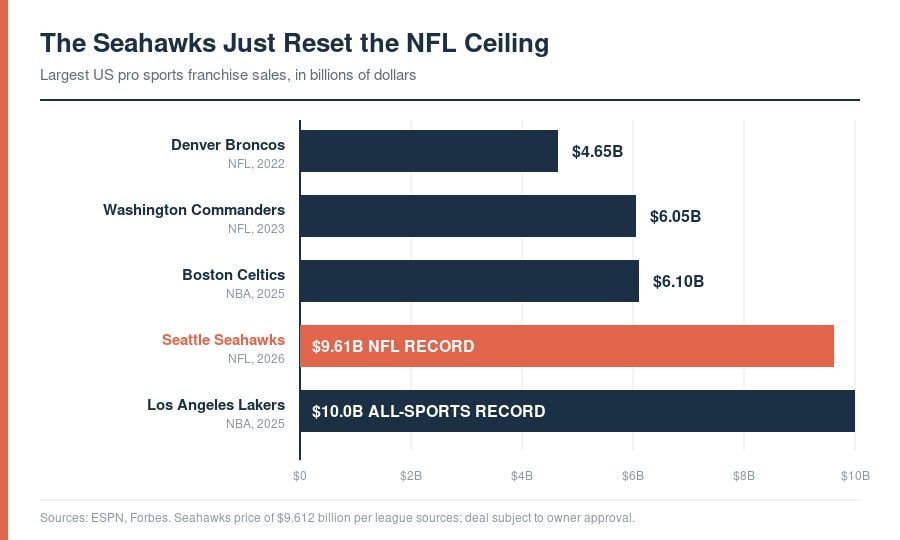
Is $9.6 billion the biggest sports deal ever? No. Mark Walter’s purchase of the Los Angeles Lakers at $10 billion in 2025 still leads. The Seahawks price is the NFL record.
The Business Model Analyst Take
Stop thinking about this as a sports transaction and the logic snaps into focus. Khosla just bought a fixed-supply claim on the last unskippable content on television, at a moment when the buyers of that content are the richest companies on earth and the current contract expires in three years.
The lesson for founders is not “buy a football team.” It is this: the most valuable position in any market is not the one that makes the product. It is the one that owns a permanent, non-dilutable share of a revenue pool that other people are forced to bid up. Allen made 14.4% a year for 29 years without ever having to out-execute anybody. He just had to own one of 32 seats.
Ask yourself what the 32 seats are in your industry, and whether you own one. That question is worth more than any growth hack.
And the honest counterweight: 67 times earnings is a price that forgives no mistakes. If the 2029 media reset lands flat, this deal will be studied as the moment scarcity stopped being an argument and became a bubble. Khosla built his career on bets where being wrong costs you 1x and being right pays 100x. This one does not work that way. He is risking $9.6 billion to maybe make two.