
Deere & Company runs its strengths on a decade clock and its threats on a quarterly one. Read the four quadrants on the same scale and you will misprice the company in both directions.
Deere finished the third quarter of fiscal 2026 with a 14.4% operating margin in equipment operations while its own forecast called for large agricultural equipment sales in the United States and Canada to fall 15% to 20% for the year. The stock rose 8.59% on the print, to $630.48. Two weeks earlier AGCO had told investors its mid-cycle margin ambition was 14% to 15%, a number it hopes to reach when the market recovers. Deere posted that number at what its chairman called the bottom.
That gap is the useful starting point for a SWOT analysis of Deere, and almost no published version of one accounts for it. The standard treatment lists brand strength, dealer coverage and precision technology under Strengths, then lists commodity prices, tariffs and farm income under Threats, and scores them as if they were comparable quantities. They are not. Deere’s advantages took twenty years to build and would take twenty years to dismantle. Its threats reprice every ninety days. The mismatch explains why Deere looks fragile in every downturn headline and never turns out to be, and it also points at the one danger that matters, which is the only threat on the slow clock.
What a SWOT Analysis Does
A SWOT analysis sorts a company’s position into four buckets: Strengths and Weaknesses, which sit inside the business and under management control, and Opportunities and Threats, which sit outside it. Albert Humphrey developed the framework at the Stanford Research Institute in the 1960s to work out why corporate planning kept failing.
The framework has a known flaw. It presents four lists of equal visual weight, which invites you to treat a threat that could arrive next quarter and a strength that took a generation to build as comparable line items. For a cyclical industrial like Deere, that flaw does most of the damage. If you want the mechanics of the framework itself, start with our guides to SWOT analysis and how to do a SWOT analysis.
Deere at a Glance
| Measure | FY2025 (ended Nov 2, 2025) | Q3 FY2026 (ended Aug 2, 2026) |
|---|---|---|
| Total net sales and revenues | $45,684M, down 12% | $12,608M, up 5% |
| Equipment operations net sales | $38,917M, down 13% | $10,999M, up 6% |
| Net income attributable to Deere | $5,027M ($18.50 per share) | $1,379M ($5.10 per share) |
| Equipment operations operating margin | 12.6% | 14.4% |
| Production & Precision Ag | $17,311M sales, 15.4% margin | $3,998M, down 6%, 13.2% margin |
| Small Ag & Turf | $10,224M sales, 11.8% margin | $3,383M, up 12%, 18.4% margin |
| Construction & Forestry | $11,382M sales, 9.0% margin | $3,618M, up 18%, 12.1% margin |
| Financial Services | $5,821M revenue, $890M net income | $219M net income |
Fiscal 2026 guidance, raised at the Q3 call on August 20, puts net income at $4.75 billion to $5.00 billion and equipment operations cash flow at $5.0 billion to $5.5 billion.
Our John Deere business model teardown works through the machinery of how this company makes money: the captive credit book that holds two thirds of consolidated assets, the deliberate underproduction that defends used-equipment values, precision technology sold as an attach rate rather than a product line, and why the repair lock was never the moat. This piece stays on competitive position, policy exposure and channel risk, and does not re-run that arithmetic.
The Slow Clock: Strengths
A margin floor no competitor comes close to
The single most useful competitive fact about Deere in 2026 is what it earns when conditions are bad.
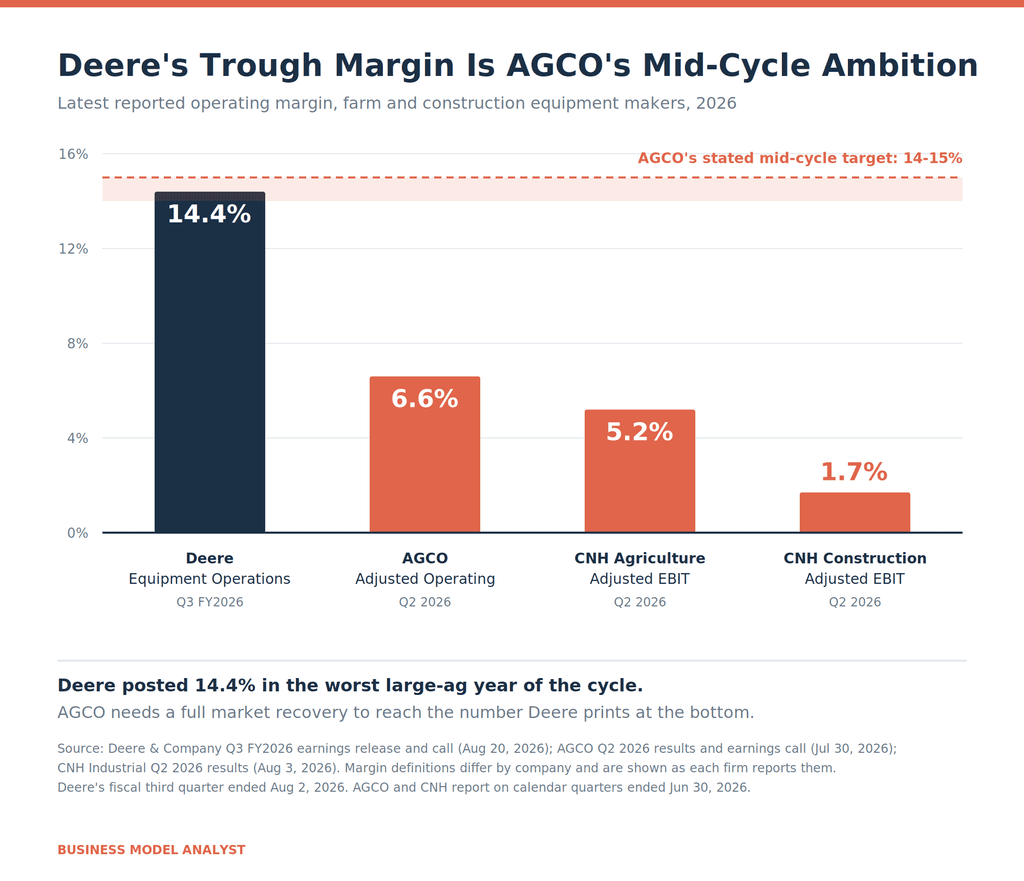
AGCO reported a 6.6% adjusted operating margin for the June quarter, down 170 basis points year over year, and guided the full year to roughly 7.5%. CNH reported 5.2% adjusted EBIT in Agriculture and 1.7% in Construction, guiding Industrial Activities to 3.2% to 3.8% for the year. Deere printed 14.4% for the quarter and guides its worst segment, Production & Precision Ag, to 11% to 12% for the full year.
Read that against AGCO’s own recovery case. Management has told investors it is targeting 14% to 15% at mid-cycle. Deere’s floor is AGCO’s ceiling. Whatever the four quadrants say about brand or technology, that spread is the strength, because it determines who can fund research through a downturn and who has to stop.
R&D that does not flex with the cycle
Deere spent $2,311 million on research and development in fiscal 2025 against $2,290 million in fiscal 2024, holding the dollar figure flat while equipment sales fell 13%. Research intensity rose from 5.1% to 5.9% of equipment sales as a result. AGCO, by contrast, is running a program to extract $60 million to $70 million of operational efficiency benefits this year and cut its own sales and margin guidance in July. CNH is chasing 100 to 150 basis points of sourcing margin improvement by 2030.
Those are the moves of companies protecting a number. Deere is buying the next cycle.
Segment mix that pays the bills when the farm does not
Small Ag & Turf grew 12% in the third quarter at an 18.4% margin. Construction & Forestry grew 18% at 12.1%, with order books running four to five months against a normal two to three, filled by infrastructure, data center and energy work. Deere raised the Small Ag & Turf full-year margin forecast to 14.5% to 15.5% and Construction & Forestry to 10.5% to 11.5%, up from 9.0% in fiscal 2025.
The flagship large-ag business shrank while the other two carried the year. For a company most readers file under “tractors,” roughly 64% of third-quarter equipment sales came from somewhere other than Production & Precision Ag.
A dealer channel built for the machines Deere now sells
Deere runs about 2,050 dealer points across the United States and Canada, roughly 1,600 in agriculture and 450 in construction and forestry, all independently owned. The relevant number is not the count but the capability. Since the 2002 Dealer of Tomorrow program, Deere has pushed its network toward larger groups that can afford certified precision specialists, shared parts inventory and technician training. In 2026 Deere still has more dealer groups running five or more agricultural stores than any other brand.
Selling See & Spray to a third of the North American sprayer order book for model year 2027 requires people in the field who can commission it. Deere spent two decades building that layer.
The Slow Clock: Weaknesses
The tariff bill scales with the footprint
Deere expects roughly $1.1 billion in direct tariff expense in fiscal 2026, and about $750 million net after the refunds it has recognized. AGCO expects $115 million gross and $95 million net. Comparing the raw dollars tells you Deere is bigger. Comparing them against sales tells you something else.
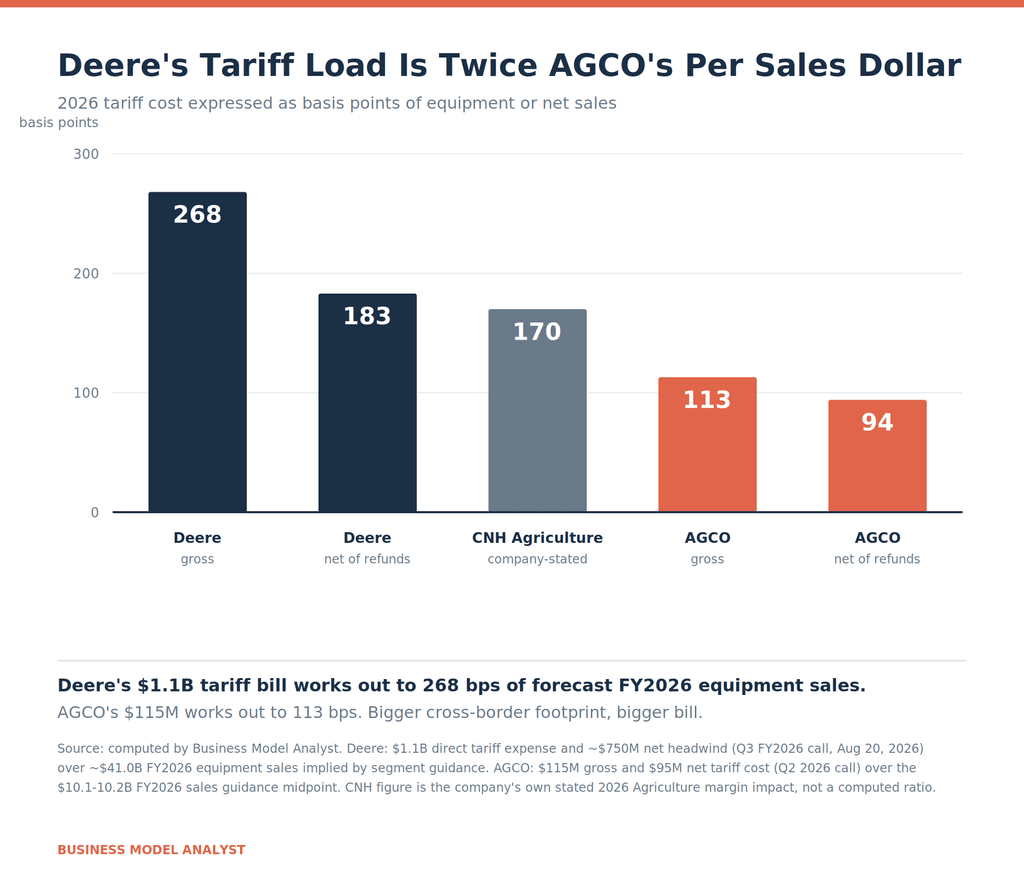
Deere’s segment guidance implies about $41.0 billion of equipment sales for fiscal 2026. The $1.1 billion works out to 268 basis points. AGCO’s $115 million against its $10.1 billion to $10.2 billion guidance works out to 113. CNH puts its own 2026 Agriculture margin impact at 170 basis points, and its Construction impact at 470, which the company attributes to a heavier reliance on imported finished equipment.
Deere carries more than twice AGCO’s tariff load per dollar of sales because Deere makes more things in more countries and moves more components across more borders. The manufacturing footprint that produces the cost advantage in a normal year produces the tariff bill in this one. The definitions here differ slightly by company and the arithmetic is ours, not theirs, but the direction is not in dispute.
Deere expects a direct run rate near $1 billion in fiscal 2027 on no refund assumption at all.
Two of the three big geographies are broken at once
About 34% of Deere’s revenue comes from outside the United States and Canada, and the two regions that matter most in that share are the two performing worst.
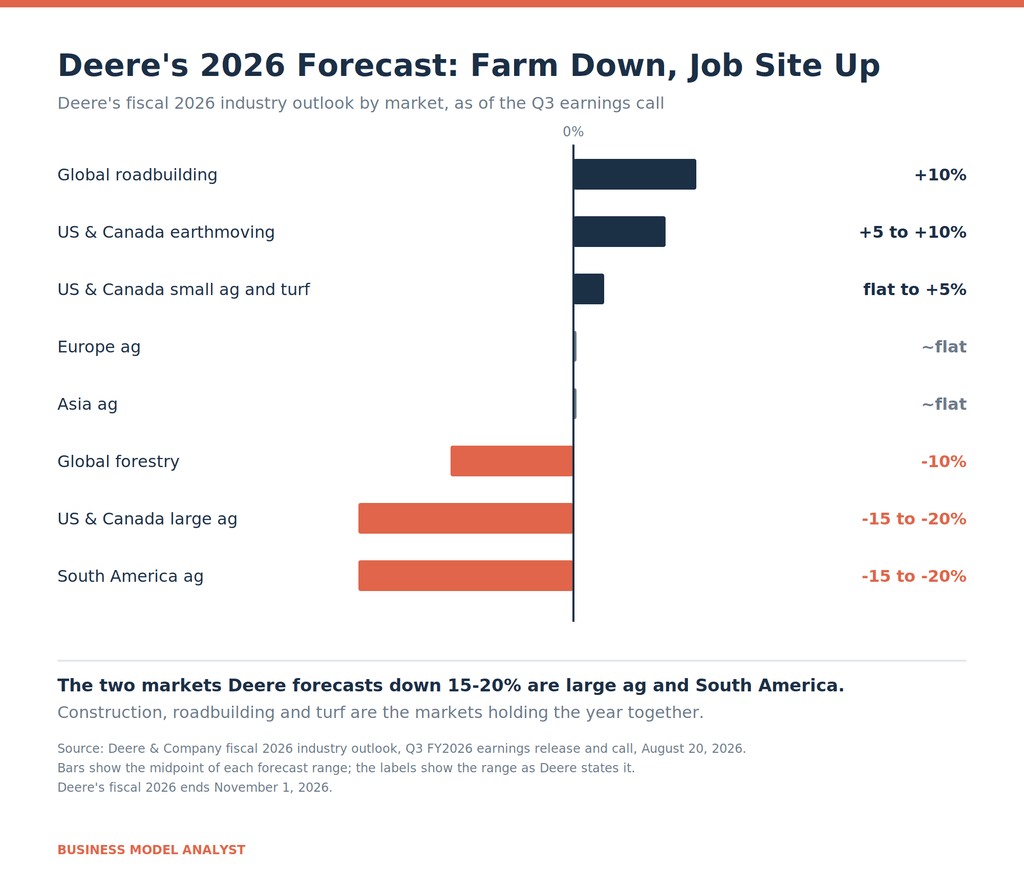
Deere forecasts South American industry sales down 15% to 20% on production costs and interest rates, and Europe roughly flat. The peer data confirms this is regional rather than a share problem: CNH’s agriculture sales in South America fell 27% year over year in the second quarter, and AGCO’s Latin America net sales fell 25% in constant currency. Everyone is losing there together.
That is cold comfort. A US-heavy revenue mix leaves Deere levered to a single country’s farm policy, and Brazil, the growth market of the last decade, is currently subtracting.
Precision adoption is wide but shallow
Deere reported 520 million engaged acres and roughly 1.2 million connected machines in the third quarter, against Leap Ambitions targets for 2026 of 500 million acres and 1.5 million machines. The acre target is met at 104%. The machine target sits at 80%.
Look at the quality of the engagement and the gap widens. Of the 520 million engaged acres, 190 million qualify as highly engaged, roughly 37%. Monthly active digital users number 450,000. The stated goal of 10% recurring revenue by 2030 depends on machines and subscriptions, not on acres, and machines are the number running behind.
The trough discipline caps the upside too
Deere is deliberately underproducing by a few percentage points in Production & Precision Ag and Construction & Forestry to protect channel inventory and used values. Used high-horsepower tractor inventory for model years 2023 and 2024 is down roughly 40% year over year and the new-to-used price spread has normalized, so the policy is working. CNH is running the same play at 4% underproduction.
The cost is that Deere cannot chase volume in a soft market without unwinding the thing that makes its aftermarket and financing economics work. In a share war, Deere is structurally the one who does not fight. That is a choice, and a defensible one, but it belongs in the weakness column rather than the strength column where most analyses put it.
The Fast Clock: Opportunities
The cycle turning
Deere’s own language in the August release was that 2026 marks the bottom, with a strong fourth-quarter order book across all segments. Used inventory has cleared, fleets have aged, and the new-used spread has converged. CNH’s management describes the same conditions.
If that read holds, Deere enters the recovery with cleaner channel inventory than it had going into the last upcycle and with research spending that never paused.
Construction demand that has nothing to do with farming
Global roadbuilding is forecast up roughly 10% and US and Canada earthmoving up 5% to 10%, driven by infrastructure, data center construction and power generation projects. Deere’s Construction & Forestry backlog now extends into fiscal 2027. Roughly 30% to 35% of earthmoving transactions start as rentals, which gives Deere a second path into fleets that are not ready to buy.
This is the growth pool that does not depend on corn prices, and it is the one where Deere is the challenger rather than the incumbent.
Excavators Deere designs itself
Deere launched three of its own excavator models in spring 2026, with a three to four year rollout planned and further models coming in spring 2027. Replacing sourced product with in-house design moves margin from a supplier’s income statement to Deere’s, and management flagged a positive customer response as part of the reason for raising Construction & Forestry guidance.
Government money, arriving now
The USDA forecasts 2026 net farm income of $153.4 billion, down 0.7%, with direct government payments of $44.3 billion, up 45.2% from $30.5 billion in 2025 under ARC and PLC provisions plus disaster aid. Farm cash receipts are falling and transfers are rising to fill the gap. Whatever that says about the health of the sector, it is spendable money in the hands of Deere’s customers during the year Deere expects to trough.
The repair settlement as a product
The stipulated order Deere entered in the Northern District of Illinois in July 2026 commits it to ten years of tool and software access parity for farmers and independent shops. On the August call, CFO Brent Norwood told analysts the order formalizes support Deere already provided and backs the life cycle solutions ambition. Anyone modeling this as pure cost is modeling it wrong, which our business model piece covers at length.
The Fast Clock: Threats
Kubota is winning where Deere earns the most
Every competitive analysis of Deere frames the fight as Deere against CNH and AGCO. Both are shrinking. The company actually taking ground is Kubota.
Kubota’s first half of 2026 brought revenue up 16.2% and operating profit up 64.7%, and it raised full-year guidance to a 12.2% operating margin against 8.8% in 2025. North American revenue in its Farm & Industrial Machinery segment rose 25% in the June quarter, and global construction equipment sales rose 36.4%.
Kubota competes at the compact and utility end. That is Small Ag & Turf, the segment that just delivered Deere’s highest margin at 18.4% and the one Deere guided up 15% for the year. The threat is not to the combine business. It is to the business that is currently subsidizing the combine business through the trough.
Tariff policy, with no refund assumption
The $382 million of refunds Deere recognized in fiscal 2026, including $110 million in the third quarter, followed the Section 232 rate on European imports dropping from 25% to 15% on June 1. Deere’s fiscal 2027 planning assumes none of that repeats. A policy that moved once in Deere’s favor can move again in the other direction, and the company has told investors to expect roughly $1 billion of direct cost either way.
Farm income that depends on Washington
Government transfers at $44.3 billion represent about 29% of 2026 net farm income. Crop cash receipts are up 1.2% nominally and down 0.7% in real terms, while production expenses run at $477.7 billion. The demand that Deere’s fiscal 2027 recovery case rests on is partly an appropriations outcome, and appropriations change faster than combines wear out.
The slow threat: consolidation is hitting a ceiling
Here is the one that belongs on the decade clock, and the one no competitor page has.
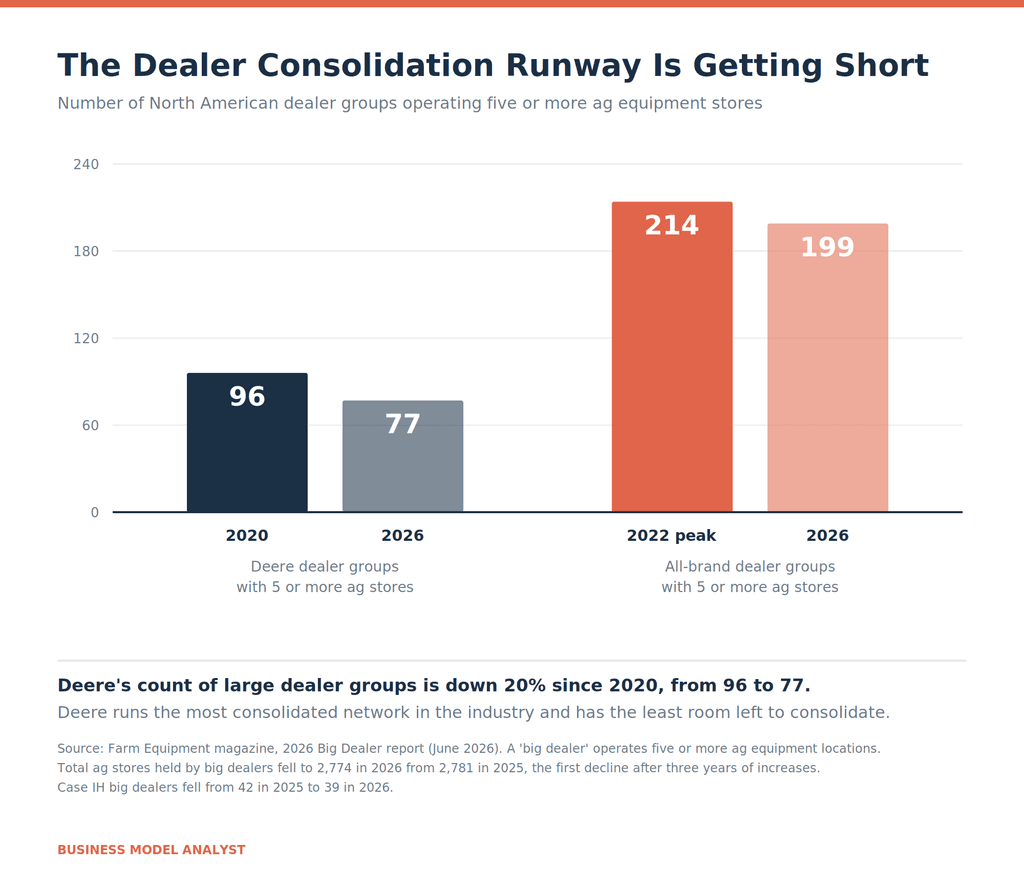
Deere’s count of dealer groups running five or more agricultural stores has fallen from 96 in 2020 to 77 in 2026. Across all brands the count peaked at 214 in 2022 and now sits at 199, a fourth consecutive annual decline, and in 2026 the total number of stores those groups own fell for the first time in four years, to 2,774 from 2,781. Case IH went from 42 big dealers to 39 in a single year.
Deere has run this program since 2002 and it worked, on Deere’s own terms: bigger dealers meant better precision support, higher customer satisfaction and better dealer profitability. Running it further now means running into competition regulators.
In January 2026, Enns Brothers and Greenvalley Equipment announced a merger of their Manitoba John Deere operations, 13 locations combined. Canada’s Competition Bureau opened a review on January 23. The file closed on May 1 with the transaction abandoned by the parties. Greenvalley’s president told RealAgriculture the roadblocks and delays made proceeding impractical. Thirteen stores in one Canadian province, in a deal small enough that it may not have triggered mandatory notification, and the Bureau still looked at it and the parties still walked.
Read that against the Operations Center. Deere’s digital platform gets more valuable as more machines and more acres connect, and connecting them requires dealers with certified specialists in reach of the farm. Deere needs its dealers consolidated enough to invest and dispersed enough to serve. Regulators now have an opinion about where that line sits, and farmers rely on local dealer support during planting and harvest windows measured in days, which makes service competition a live antitrust question rather than a theoretical one.
Nothing here breaks in a quarter. It compounds over a decade, in exactly the direction Deere’s technology strategy needs it not to.
The Matrix
| Helpful | Harmful | |
|---|---|---|
| Internal | Strengths. 14.4% equipment margin at the cycle bottom against AGCO’s 6.6% and CNH Agriculture’s 5.2%. R&D held flat in dollars through a 13% sales decline. Small Ag & Turf at 18.4% and Construction & Forestry order books into FY2027. The most consolidated capable dealer network in the industry, roughly 2,050 points in the US and Canada. A captive credit book holding two thirds of consolidated assets. | Weaknesses. Tariff cost at 268 basis points of sales versus AGCO’s 113. About 34% of revenue outside the US and Canada, with South America down 15% to 20% and Europe flat. Connected machines at 80% of the 2026 target while acres run at 104%. Only 37% of engaged acres are highly engaged. Underproduction discipline forfeits share in a soft market. |
| External | Opportunities. Management calls 2026 the bottom, with a strong Q4 order book across all segments. Roadbuilding up 10% and earthmoving up 5% to 10% on infrastructure, data centers and energy. Three Deere-designed excavators launched in 2026 on a three to four year rollout. $44.3 billion of direct government payments, up 45.2%. The July 2026 repair order as a life cycle solutions channel. | Threats. Kubota growing 25% in North American farm and industrial machinery, aimed at Deere’s highest-margin segment. A roughly $1 billion fiscal 2027 tariff run rate with no refund assumed. Farm demand resting on appropriations, with transfers at 29% of net farm income. Dealer consolidation meeting competition regulators, as the abandoned Enns Brothers and Greenvalley merger showed in May 2026. |
What the Two Clocks Change
Sort the quadrants by how fast each item can move and the analysis reorganizes itself.
Everything in Deere’s Threats column except one item reprices inside a year. Tariff rates changed twice in 2026 alone. Farm bill payments are an annual appropriation. Kubota’s North American surge is running against a weak comparison and a strong yen effect. Commodity prices do what commodity prices do. These are real costs and they are worth several hundred million dollars a year, but none of them touches the reason Deere out-earns AGCO by eight percentage points at the bottom of a cycle.
Everything in the Strengths column takes a decade to move. A dealer network with certified precision specialists, an installed base of 1.2 million connected machines, a credit book with a residual-value history long enough to underwrite against, a research budget that survives downturns. A competitor who decided today to build any of those would be a decade from mattering.
The exception runs the other way, and that is the finding. Dealer consolidation sits in the Threats column but moves on the slow clock, which is what makes it dangerous. Deere cannot fix it with pricing, cannot hedge it, and cannot outspend it. It can only be managed across years, in negotiation with regulators in two countries who have started paying attention. Every published Deere SWOT lists commodity prices as the top threat. Commodity prices are noise on a decade horizon. The permission to keep consolidating a dealer network is not.
For anyone using this as a template: run your own quadrants through the same filter. Ask how long each item would take to reverse. The Strengths that reverse in a quarter are not strengths, and the Threats that reverse in a quarter are weather.
FAQ
What is John Deere’s biggest strength in 2026? Earnings durability at the bottom of the cycle. Deere posted a 14.4% equipment operations operating margin in the quarter ended August 2, 2026, while forecasting a 15% to 20% decline in its largest market. AGCO reported 6.6% and CNH reported 5.2% in Agriculture over roughly the same period.
What is John Deere’s biggest weakness? Tariff exposure per dollar of sales. Deere’s roughly $1.1 billion fiscal 2026 direct tariff expense works out to about 268 basis points of forecast equipment sales, against roughly 113 for AGCO. Deere’s manufacturing footprint spans more countries and moves more components across more borders.
Who is John Deere’s most serious competitor? By revenue and market position, Caterpillar in construction and CNH in agriculture. By momentum, Kubota, whose North American farm and industrial machinery revenue rose 25% in the June quarter and which competes hardest in Small Ag & Turf, Deere’s highest-margin segment at 18.4%.
How exposed is Deere to farm policy? The USDA forecasts $44.3 billion of direct government payments in 2026, up 45.2%, against net farm income of $153.4 billion. Transfers are roughly 29% of what US farmers earn, which puts a meaningful share of Deere’s demand on an appropriations cycle.
Did the right to repair settlement hurt Deere? Not on the evidence so far. Deere agreed to a $99 million class settlement in April 2026 and entered a stipulated order in July committing to ten years of tool and software access parity. On the August 20 call, CFO Brent Norwood described the order as formalizing support Deere already provided and as consistent with its life cycle solutions ambitions.
Is Deere’s precision agriculture strategy working? Partly. Engaged acres reached 520 million against a 2026 target of 500 million. Connected machines reached roughly 1.2 million against a target of 1.5 million. The revenue model depends on machines and subscriptions rather than acres, so the number running behind is the one that matters.
Why does dealer consolidation matter to Deere? Precision equipment needs dealers large enough to employ certified specialists and stock shared parts inventory. Deere has pushed toward that structure since 2002 and now has 77 dealer groups with five or more ag stores, down from 96 in 2020. In May 2026, Canada’s Competition Bureau review led two Manitoba Deere dealers to abandon a 13-store merger, the first visible sign that the strategy has a regulatory ceiling.
The Business Model Analyst Take
Deere is the rare industrial where the SWOT framework actively misleads, because the framework has no time axis and Deere’s position is entirely about time. Give it one and the picture clarifies: a company whose advantages compound over decades, whose visible threats reprice quarterly, and whose one genuine long-horizon risk sits in the wrong box on every chart anyone has drawn.
Watch the dealer count, not the corn price. Deere spent twenty-four years building a channel capable of selling and supporting software-defined machinery, and it built it by making dealers bigger. The razor and blade logic of the whole model, cheap access to a base you monetize over its life, needs that channel intact and capable. Big dealers are the delivery mechanism.
Canada’s Competition Bureau just demonstrated that a thirteen-store combination in one province is now worth a look. Deere’s next decade of technology revenue depends on a network structure that regulators in two countries have started to question. That is a slower and less dramatic problem than a tariff headline, which is exactly why it is the one worth tracking.