
Google spent $5.1 billion in two years buying AI researchers back. This week it ran the trade in reverse, writing a seed check and a cloud contract to let four of its most important ones walk out.
Alphabet closed down 3.9% on Wednesday, giving up roughly $190 billion of market value, after Jeff Dean and three colleagues resigned to found Discovery Loop. Google is a founding investor in the new company and will supply its compute. The loss on the day was close to Alphabet’s entire 2026 AI capital budget. That gap between what Alphabet can put on a balance sheet and what the market thinks it owns is the story.
Sundar Pichai sent a memo on Wednesday titled “The next chapter of our AI momentum.” By the close, investors had removed from Alphabet roughly what the company plans to spend on data centers for the whole of 2026.
What Happened
Jeff Dean, Google’s chief scientist and its 30th employee, is leaving after 27 years to become chief executive of Discovery Loop, an independent public benefit corporation. He takes three people with him: Sanjay Ghemawat, his collaborator since 1999 and one of only two Google engineers ever named senior fellow; Quoc Le, a Google Brain co-founder whose sequence-to-sequence work sits under modern machine translation; and Oriol Vinyals, the DeepMind vice president who built AlphaStar and co-led Gemini. Dean says the four have worked together for stretches running from 14 to 30 years.
Radical Ventures and Khosla Ventures are co-leading the seed round. It has not closed, and nobody will name a valuation. Alphabet is a founding investor and the cloud partner, and Dean told the New York Times that Alphabet has committed to supply the compute the company needs for at least the next year.
Pichai bundled a second announcement into the same memo, and most coverage buried it. Demis Hassabis is giving up the Google DeepMind chief executive title to become the unit’s chairman and chief scientist of Alphabet, while continuing to run Isomorphic Labs. Koray Kavukcuoglu, DeepMind’s chief technology officer for 13 years, takes over daily operations as senior vice president, reporting to Pichai. Google DeepMind no longer has a chief executive.
Alphabet touched $381.81 before the news broke, fell below $356 within minutes, and settled at $360.71 against Tuesday’s $375.35 close. On a $4.61 trillion base, that is about $190 billion at the close and nearer $260 billion at the low.
The Backstory
Google has been losing this cohort all year. David Silver left in February. Noam Shazeer, a co-author of the 2017 transformer paper and a Gemini co-lead, went to OpenAI in June alongside policy hire Dean Ball, a move we read at the time as pre-IPO bench-stacking. John Jumper, who shared the 2024 Nobel in chemistry with Hassabis for AlphaFold, went to Anthropic. Peter Norvig, 25 years the head of Google research, went to Recursive Superintelligence, as did Tim Rocktäschel.
Investors have already repriced this once. On June 22, Alphabet closed 5.1% lower after two researchers left within days of each other, its worst single session in a year at the time. Wednesday was the second people-driven drawdown in six weeks.
The product backdrop is not helping. Gemini 3.5 Pro was supposed to ship in June. Bloomberg reported it fell short of internal targets; Axios reported low morale as a contributing factor. Hassabis has told staff Gemini 4 is coming. It will be the first flagship model Google ships without the researcher who has shaped its AI work since 2011.
Google’s answer to talent loss used to be a checkbook. In August 2024 it paid $2.7 billion for a non-exclusive license to Character.AI’s technology, a structure that also brought Shazeer, Daniel De Freitas and about 30 researchers back into DeepMind and kept the deal below Hart-Scott-Rodino filing thresholds. The DOJ later looked at whether that was the point. In July 2025 Google paid about $2.4 billion for a Windsurf license and its founders after OpenAI’s $3 billion acquisition collapsed. Call it $5.1 billion across 24 months to import researchers.
Shazeer, the name the $2.7 billion deal was built around, resigned 22 months later.
The Plan
Discovery Loop wants to automate the experimental loop itself: propose an experiment, run it, evaluate the result, iterate, thousands of times in parallel. The company will start on machine learning research and engineering, then extend to hardware design, drug discovery and clean energy. Underneath sits recursive self-improvement, the idea that AI systems can improve themselves with little human involvement.
“We think there is opportunity for A.I. to more fully automate what has traditionally been a very human-intensive experimental loop,” Dean told the Times. Vinyals put the case for leaving more plainly: extreme focus works best when the thing you care about is the only thing the company does.
Google gets a collaboration on ML systems research, an equity position, and a cloud customer.
The Business Model Angle
Alphabet has now run both directions of the same trade inside two years, and the second direction is cheaper.
The acquihire is a purchase. You pay $2.7 billion up front, you book an intangible, and you hope the person stays. When they resign, nothing happens in the accounts, because a company cannot capitalize a human being and therefore cannot impair one either. Google’s marquee talent import walked out 22 months later and produced no write-down, no charge, no line item. The asset was never on the books to begin with.
The spin-out is an option. Alphabet writes a seed check into a round it does not control, signs a compute agreement that converts the commitment into Google Cloud revenue rather than cost, and takes a collaboration on ML systems research in exchange. If Discovery Loop works, Alphabet owns a slice and has a view inside. If it fails, Alphabet loses a seed check. Either way the four researchers are collaborators rather than competitors, which is worth more than the equity.
Google has run this play before. Alphabet already sits on Safe Superintelligence’s cap table, and Google Cloud already supplies that lab with TPUs. When Nvidia put a reported $5 billion into SSI for rare access to research that has produced no product, it was buying the same thing Alphabet is buying here. The template across the sector now reads: fund the lab, sell it compute, secure the look inside.
Here is what the market did with that. Alphabet added 11,830 net employees during Q2, taking headcount from 187,103 to 198,933, and nobody moved the stock. Four people resigned in August and investors took off $190 billion. At $4.61 trillion, an average Alphabet employee carries about $23.2 million of market value. The four departing researchers were repriced at roughly $47.5 billion each, about 2,000 times the average.
The metric is crude on purpose. It shows that investors do not value Alphabet’s headcount, they value about a dozen names inside it, and Alphabet’s accounting has no way to represent the difference.
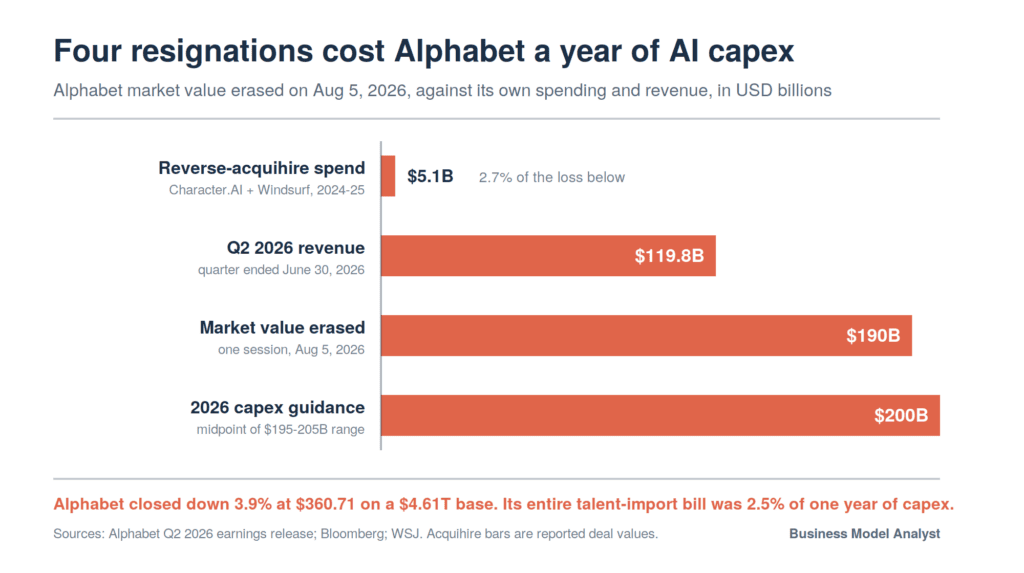
The comparison that should worry Pichai sits in that chart. Alphabet’s entire two-year talent-import bill, both marquee deals combined, came to 2.5% of a single year of capital expenditure. The company can capitalize $200 billion of servers, buildings and TPUs. It can capitalize none of the people who decide what to run on them.
| Alphabet Q2 2026 | Result | Change |
|---|---|---|
| Revenue | $119.8B | +24% |
| Google Cloud revenue | $24.8B | +82% |
| Cloud operating income | $8.8B | from $2.8B |
| Cloud backlog | $514B | from $106B a year ago |
| Operating income | $40.8B | +30% |
| Operating margin | 34% | +2 pts |
| Capital expenditure | $44.9B | +100% |
| Free cash flow | -$5.9B | negative |
Every operating line accelerated. The market has stopped pricing that income statement and started pricing the org chart.
The Risk
The obvious risk is that Discovery Loop is the second-most important thing that happened on Wednesday. Losing four researchers is survivable for a company with 198,933 employees. Losing the chief executive of your AI lab and your chief scientist in the same memo, while your flagship model runs months late, is a different kind of problem. Kavukcuoglu inherits Gemini model development, frontier research, the Gemini app and the developer platforms, and reports to a chief executive who is not a researcher. Google merged Brain and DeepMind in April 2023 to pool exactly this work. Three years later the merged unit has no chief executive and has lost the chief scientist that merger created.
The second risk is that the funding structure keeps the talent close without keeping any of the value. Alphabet’s seed position in a company it does not control is not a hedge against Discovery Loop succeeding at recursive self-improvement. If Dean’s team automates ML research at the scale he describes, a minority stake and a one-year compute contract will look like the cheapest thing Alphabet ever gave away.
Third, the compute commitment runs for at least a year. After that, Discovery Loop is free to shop, and every hyperscaler and chip vendor in the market will bid for the account. Alphabet’s cloud relationship buys visibility on a clock.
The honest counterargument runs the other way, and it has teeth. Semafor reports Hassabis had been handing day-to-day work to Kavukcuoglu for roughly a year and was not pushed out. He struggled with being a corporate executive rather than a scientist, and his energy has gone to Isomorphic Labs. Read that way, Wednesday formalized a transition already complete and freed a Nobel laureate to do the work he is best at, while Kavukcuoglu, who built DeepMind’s deep learning team and shipped WaveNet and DQN, takes operations. Dean is 58 and had run the same building for 27 years. Companies survive founder-scientists leaving. Alphabet’s Q2 print, with a $514 billion cloud backlog and a capex guide the market already choked on, says the demand is real regardless of whose name is on the paper. A 3.9% move on a single day is sentiment, not a valuation.
Quick Questions
Is Google funding a competitor? Not directly. Discovery Loop is targeting automated experimentation for science and engineering rather than consumer chatbots, and Pichai has committed to collaborate on ML systems research. The overlap risk sits in recursive self-improvement, which is also what Google DeepMind is chasing.
Why a public benefit corporation? The PBC structure lets directors weigh public benefit against shareholder returns without breaching duty. Dean said the company might make decisions that are not in its purest financial interest. Anthropic and OpenAI use versions of the same structure, which now functions as a recruiting signal as much as a governance one.
Does the $190 billion mean anything? Single-session moves are noise more often than not. The pattern is the signal: two people-driven drawdowns in six weeks, on a stock that also sold off on capex guidance in July. Investors have found three ways to be unhappy with Alphabet this summer and none of them involve demand.
Should Alphabet shareholders care about the compute deal? It is small relative to a $514 billion cloud backlog. Watch it as a template instead. If Alphabet keeps converting departures into seed positions plus cloud contracts, that is a deliberate policy on how to handle talent it can no longer hold.
The Business Model Analyst Take
Google’s talent strategy has been repriced, and the new price is lower.
For two years the company treated researchers as assets to be acquired, paying $5.1 billion for two licensing structures whose real purpose was employment contracts. That approach produced a $2.7 billion deal whose central figure resigned 22 months later with no accounting consequence, because you cannot depreciate someone who can quit. On Wednesday Alphabet stopped buying and started underwriting. A seed check and a cloud contract cost a rounding error, generate revenue instead of consuming it, and buy a collaboration agreement plus an option on the outcome. As corporate finance, it is better in every dimension.
The market disagreed, and the market has the stronger argument. Alphabet will spend around $200 billion this year on infrastructure it can own, depreciate and defend. It cannot own the twelve or so people who know what to build with it, and on Wednesday four of them left. The capital-intensity thesis holds that whoever owns the most compute wins. Discovery Loop is a bet that whoever knows what to run on it wins, funded, hosted and now partly owned by the company holding the compute.
Alphabet is hedged either way. That is the tell. When a company writes a check to the thing that might make its $200 billion buildout less valuable, it has already priced the risk that margins in this stack migrate away from the people paying for it. Investors just did the same arithmetic and marked the stock down accordingly.
For anyone building a company on scarce technical talent, the lesson costs nothing to learn from Alphabet’s example: your balance sheet will always tell you that the building is the asset. Your market cap will keep telling you otherwise.