
The 20% Hormuz toll grabbed the headlines and vanished in 48 hours. The real cost is a permanent shift from efficiency to redundancy, and it quietly moves margin from the companies that ship goods to the ones that insure and reroute them.
Businesses spent 40 years optimizing supply chains for the lowest possible cost. The Iran war is forcing them to optimize for survival instead, paying a permanent “resilience premium” of backup inventory, alternate routes, and war-risk insurance. That premium is a cost line for manufacturers, but it is a fresh revenue stream for insurers, freight forwarders, and infrastructure builders.
Here is the tell most coverage is missing. When a story is really about geopolitics, the smart money watches the diplomats. When it is really about business models, the smart money watches who gets to reprice. Right now, the people repricing are not in Tehran or Washington. They are in Lloyd’s of London.
What Happened
On July 14, the United States reinstated its naval blockade of Iranian ports, the second time in the 2026 war. A day earlier, President Trump had floated charging commercial shippers 20% of their cargo’s value to fund US “security” in the Strait of Hormuz, a fee analysts said could double shipping costs. By Tuesday he had scrapped it, replacing the toll with a promise of Gulf-state investment into the US.
So the number everyone wrote about on Monday was gone by Tuesday. But the underlying costs did not move with it. Freight rates are still running about 84% above a year ago. Maersk is trucking containers overland from a Saudi Red Sea port to Gulf states at roughly $1,000 extra per box. And the International Monetary Fund now expects global inflation to climb to 4.7% in 2026 from 4.1% in 2025, driven by pricier energy, metals, fertilizer, and food.
The toll was theater. The rerouting is structural.
The Backstory
The war began on February 28, 2026, when the US and Israel launched airstrikes on Iran. Iran retaliated by attacking merchant ships and mining the Strait of Hormuz, the chokepoint that normally carries about a quarter of the world’s seaborne oil and a fifth of its liquefied natural gas. Commercial traffic through the strait fell more than 90%.
A June memorandum of understanding briefly calmed things. Then three vessels were attacked in early July, the US resumed strikes, and the truce effectively collapsed. Every time the shooting restarts, the risk clock resets to zero.
That reset is the whole point. For four decades, the dominant operating model in global business was “just-in-time”: hold as little inventory as possible, source from the single cheapest supplier, and trust that goods will arrive exactly when needed. Toyota built the template, and everyone from electronics to pharma to fast fashion copied it. It works beautifully until a chokepoint closes. Then it fails all at once.
The Plan
Executives are not waiting for the war to end. A survey of more than 500 chief executives at companies with over $500 million in revenue found that nearly three-quarters would accept a cost increase of more than 10% to guarantee supply-chain resilience. The mindset has shifted from reacting fast to building functions that are “permanently crisis-ready.”
In practice that means duplicating everything the old model stripped out: second and third suppliers in other regions, extra warehouses, stockpiled components, and alternate routes that bypass the strait entirely. Kuwait is studying a mothballed pipeline through the Golan Heights that has not run in 35 years. Oman is expanding ports outside the strait. Iraq, Saudi Arabia, and Turkey are exploring new pipelines and rail links. One analyst called it a “spaghetti junction” of redundant infrastructure sprouting across the Gulf.
None of this is cheap. And that is exactly why it matters for the business model, not just the news cycle.
The Business Model Angle
Here is the part almost nobody is pricing correctly. Resilience is not a cost that vanishes. It is a cost that gets reassigned. Every dollar a manufacturer now spends on redundancy is a dollar of revenue for whoever provides that redundancy.
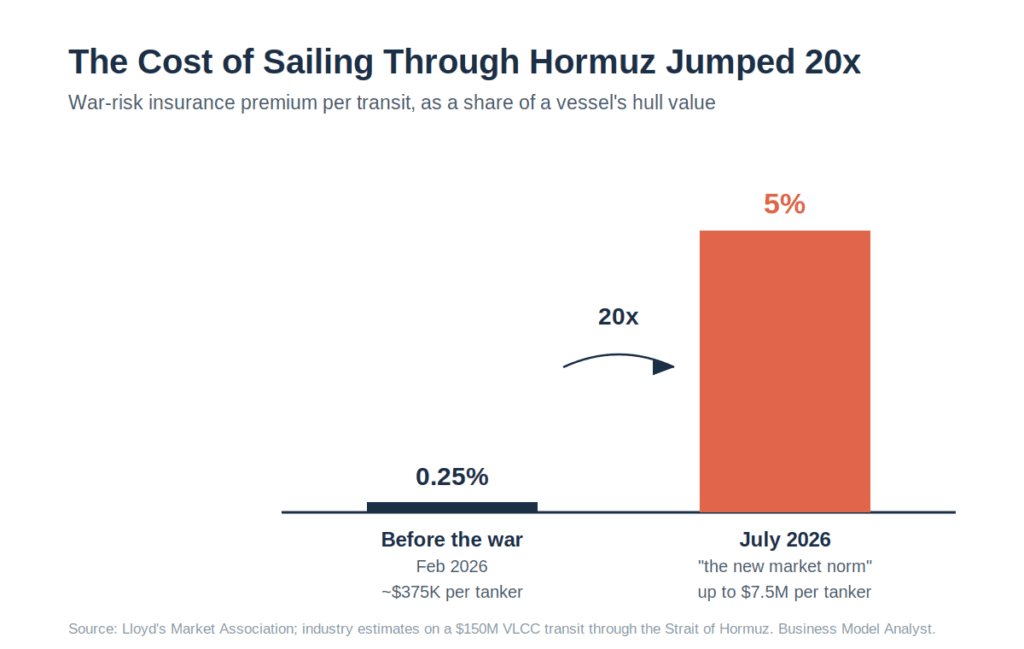
Look at war-risk insurance, the cleanest example. Standard marine hull cover explicitly excludes war, mines, and military action, so shippers must buy separate war-risk insurance priced as a percentage of the vessel’s value. Before the war, that premium sat near 0.25% of hull value for a Hormuz transit. Today it is around 5%, which the head of marine at the Lloyd’s Market Association calls “the new market norm.” On a $150 million tanker, that is a jump from roughly $375,000 to as much as $7.5 million, for the same ship, same cargo, same route. The only thing that changed was perceived risk, and insurers repriced it instantly.
That is a 20x increase in a single line item, and it flows almost entirely to underwriters. Freight forwarders capture the next slice: Maersk’s $1,000-per-container overland workaround is a cost to its customers but billable revenue to Maersk. Port operators, pipeline builders, and warehousing firms capture the capital-expenditure wave. The efficiency era rewarded whoever could strip cost out of the chain. The resilience era rewards whoever owns the redundancy that everyone suddenly needs to buy.
So the strategic question is not “will prices rise.” They will. The question is which business models sit on the receiving end of the resilience premium, and which ones simply eat it. Asset-light optimizers who out-sourced their moat to the cheapest supplier are the losers. Owners of hard-to-replicate capacity, insurers, and toll-takers on alternate routes are the winners.
The Risk
The obvious risk is that this reverses. If the war ends cleanly and the strait stays open for a sustained stretch, insurers will downgrade the risk zone and premiums will fall. Brokers think a phased rollback could start as late as Q4 2026, with normalization not before early 2027, so the window is real but not permanent.
The subtler risk is a demand shock. If the resilience premium plus energy inflation pushes consumer prices too high, buyers pull back, and the extra volume everyone is building capacity for never fully materializes. Redundancy you paid for but do not use is just stranded cost. There is also a counterintuitive twist worth noting: higher energy prices from the war have actually helped pull China out of deflation, a reminder that “inflation is bad for everyone” is too blunt. Who wins and loses depends entirely on where you sit in the chain.
Quick Questions
Is the 20% Hormuz toll still happening? No. Trump floated it on July 13 and rescinded it on July 14, replacing it with promised Gulf-state investment in the US. But shipping costs stayed elevated for other reasons: rerouting, insurance, and blockade risk.
Why are prices staying high if the strait is technically open? Insurance and freight markets move on perceived risk, not just physical access. War-risk premiums remain roughly 20x pre-war levels, and every new incident resets the clock insurers use to judge stability.
What is the “resilience premium”? It is the extra ongoing cost of running redundant supply chains: backup suppliers, extra inventory, alternate routes, and higher insurance. Nearly three-quarters of large-company CEOs say they would accept a 10%-plus cost increase to secure it.
Which businesses benefit from all this? War-risk insurers and underwriters, integrated logistics firms charging for workarounds, and builders of alternate infrastructure like pipelines, ports, and storage. Their revenue rises precisely because everyone else’s costs do.
The Business Model Analyst Take
The Iran war will fade from the front page. The operating-model shift it accelerated will not. For 40 years, “efficient” and “profitable” were treated as the same word, and the just-in-time playbook rewarded companies for stripping out every ounce of slack. That era is closing. The new default is redundancy, and redundancy is not free.
If you run a business, the actionable lesson is not “brace for higher costs.” It is “figure out which side of the resilience premium you are on.” Companies that own scarce, hard-to-copy capacity get to charge for the security everyone now wants. Companies that optimized themselves into a single cheap supplier just discovered their moat was really a liability. As one former US energy official put it, we have left the world of economizing for the most efficient option and entered the world of paying for redundancy. In that world, the winners are not the cheapest operators. They are the ones who sell resilience to everyone else.