
Washington’s designation list can only punish counterparties that need dollars. China’s independent refiners stopped needing them years ago. The trade only broke when the instrument switched from financial to physical.
On August 24, Treasury Secretary Scott Bessent announced “Operation Economic Outcast,” roughly 60 new designations and five new sectors exposed to secondary sanctions. Notably absent: any major Chinese bank. Beijing still responded furiously. But the thing that actually cut Iranian crude flowing to China was not the sanctions list. It was the naval blockade reimposed on July 13. China’s Iranian imports have fallen from around 1.34 million barrels per day in the first half of the year to roughly 534,000 in August. Financial sanctions sorted the trade. Physical force stopped it.
Asked on Monday why he was warning Iran’s trading partners instead of penalizing them, Bessent gave an answer that explains more about American economic power than the entire press conference did: “Why would I want to blow up the global financial system?”
That is not a gaffe. It is a pricing statement. The United States owns the world’s dominant payment network, and the value of owning it is precisely what caps how hard it can be used as a weapon. Every platform operator eventually learns the same thing about its biggest seller: you can ban them, but the ban costs you more than it costs them.
What Happened
Bessent unveiled the campaign at Treasury on Monday, describing it as an economic D-Day and setting the objective as cutting off every economic lifeline sustaining Tehran. The Treasury Department named five sectors it says prop up Iran’s economy, digital assets, technology, gold, aviation and shipping, and imposed sanctions on nearly 60 entities, individuals and vessels. The designated parties sit in the United Arab Emirates, Hong Kong, mainland China, Singapore and Switzerland.
What was not on the list mattered more than what was. No systemically important Chinese financial institution appeared. Pressed on whether the administration would go after Chinese banks, Bessent pointed to quiet diplomacy and declined to commit. He also flagged an action against an unnamed large international financial institution later in the week, without specifics.
Beijing responded on Tuesday anyway, warning that it would take every measure needed to protect its own interests and accusing Washington of destabilizing global finance. State media ran an editorial cartoon depicting American sanctions use as an addiction.
The timing is awkward. Xi Jinping is expected in the United States next month for talks with President Trump, and the one-year pause China agreed to on rare-earth export controls lapses only weeks after that meeting.
Meanwhile, in the physical market, something much larger was already happening.
The Backstory
For four decades, the American sanctions instrument has worked the same way. The United States sits at the center of dollar clearing, so it can threaten to cut any bank or company off from dollar transactions if that party deals with a designated entity. The threat is the product. Access is the currency. Exclusion is the enforcement.
It is, structurally, the same logic that lets any payment intermediary earn a toll on volume it does not own, which is the foundation of how fintechs make money. The difference is that Treasury collects its toll in compliance rather than basis points.
That instrument has a flaw that gets discussed far less than it should: it only works on counterparties that need the network.
China’s three state oil majors need it. They carry extensive relationships with Western banks, dollar-denominated debt, international project finance and listed equity. They have stayed away from Iranian crude for exactly that reason.
China’s independent refiners, the Shandong “teapots,” do not need it. Their financing runs largely through smaller Chinese regional banks with limited US correspondent relationships, which insulates the trade from OFAC-driven banking compliance pressure. Much of the settlement happens in renminbi or crypto. The cargoes get relabeled as Malaysian or Omani and transferred ship to ship off Malaysia before reaching Chinese ports. Nothing in that chain touches a dollar correspondent account.
So here is what a decade of escalating designations actually accomplished. It did not stop the trade. It sorted it. Every round of sanctions removed another dollar-exposed participant and left behind a residual population that was immune by construction. Washington has added more than 1,000 entities to the list since the start of this presidential term, more than 400 of them tied to Iran since the war began on February 28. The barrels kept moving, because by then they were moving through balance sheets the weapon could not reach.
The precedent everyone cites is 2012, when the Obama administration sanctioned Bank of Kunlun, a Chinese lender owned by China National Petroleum Corporation, over its Iranian dealings. That worked because Kunlun was inside the network. The teapots’ financiers never were.
The exit door has also gotten wider. China’s Cross-Border Interbank Payment System settled about 180 trillion yuan in 2025 across 8.44 million transactions and 1,766 participants. Roughly 30% of China’s trade is now settled in renminbi, up from about 10% in 2017, and China and Russia settle the overwhelming majority of their bilateral trade in national currencies. None of that displaces the dollar. All of it reduces the number of transactions the dollar weapon can touch.
The Plan
Read Bessent’s announcement as a document about capability rather than intent and it says something different from the press release.
The secondary-sanctions expansion is optionality, not action. He described it as a warning shot and a resetting of expectations, with penalties available in the coming weeks if Iran does not move or if partners do not comply. The 60 designations are enforcement theater at the periphery: shipping agents, brokers, procurement fronts, vessels. Real, cumulative, and nowhere near the arteries.
The arteries were never the target, because targeting them means targeting China, and China holds a counter-instrument that Washington cannot match. Beijing spent the last trade war demonstrating control over critical minerals and supply chains, and the rare-earth reprieve expires almost immediately after the Xi-Trump meeting. Confronting Beijing over Iranian oil would put a rare-earth cutoff on the table during a negotiation the administration wants to keep alive.
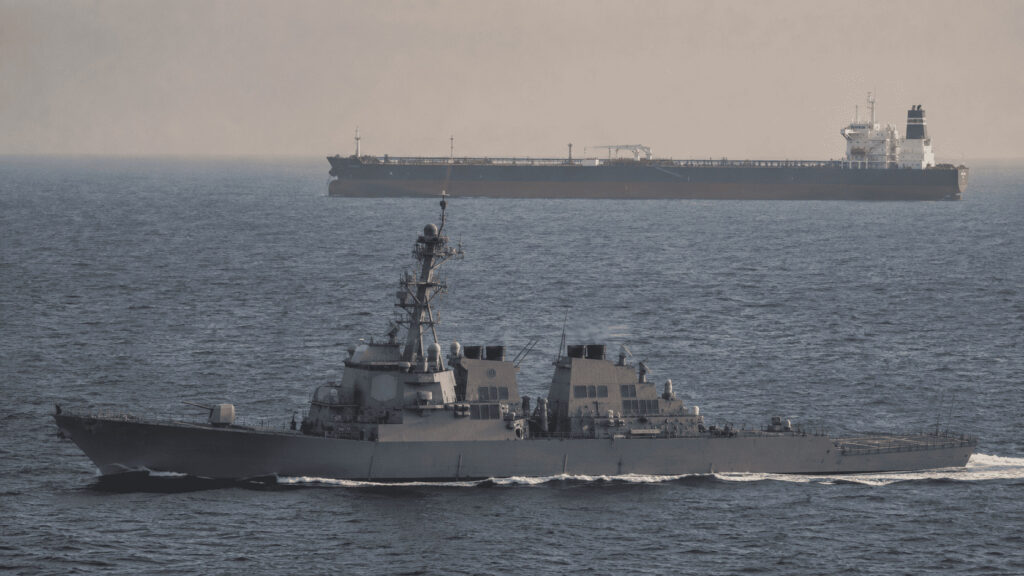
So the administration reached for the one lever that does not require Chinese consent. On July 13 it reimposed a naval blockade on Iranian ports.
US Central Command reported that American forces have redirected 65 commercial vessels, disabled three and boarded two since the blockade resumed, and no Iranian supertanker has been seen crossing the Strait of Hormuz since July. Iranian crude in floating storage outside the blockade zone has fallen to roughly 80 million barrels from about 105 million before July 13. Kpler’s preliminary figures put China’s August imports of Iranian crude at about 534,000 barrels per day, down from roughly 823,000 in July.
Six months of designations moved the number very little. Six weeks of warships moved it more than half.
The Business Model Angle
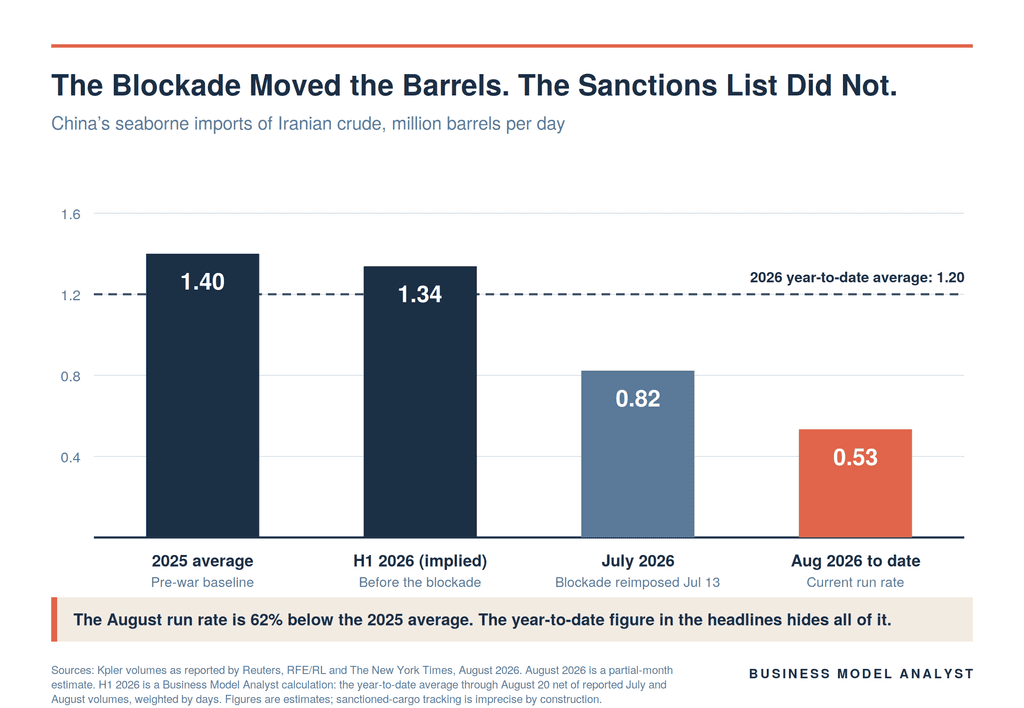
Start with the number everyone is quoting. Kpler’s year-to-date figure of about 1.2 million barrels per day is described as only slightly below the same period last year, and that framing is doing enormous work. It is a stale average.
Run the arithmetic. If the year-to-date average through August 20 is 1.20, July printed 0.823 and August is running at 0.534, then the first half of 2026 must have averaged roughly 1.34 million barrels per day. Against that implied first-half baseline, the current run rate is down about 60%. Against the 2025 average of 1.4 million, it is down about 62%. The headline number is not measuring the present. It is measuring a period that ended six weeks ago, diluted across seven months.
That distinction is the whole story, because it identifies which instrument worked.
Now the second-order effect, which is where this gets interesting for anyone who thinks in business models. The teapots’ entire competitive position was the discount. They are sub-scale refiners, about a fifth of Chinese refining capacity, that cannot beat Sinopec or PetroChina on cost, scale, or product slate. They have none of the structural advantages that make an integrated major work, where owning everything from the wellhead to the pump is the whole point of the ExxonMobil business model. What they had was access to a feedstock nobody else would touch, priced below market because the seller had no other buyer. The discount was not a perk. It was the business model.
Iranian Light was being offered at a discount of around $3 a barrel earlier this month. Within days it was being offered at a premium of roughly $2 to ICE Brent. That five-dollar swing does not squeeze a margin. It deletes one. A teapot buying Iranian crude at a premium is paying more than a state major pays for fully legal barrels, while carrying every unit of sanctions risk the majors decline to hold. Analysts are already seeing them shift toward Brazilian and Iraqi supply.
Sit with the implication. For years, American financial sanctions were the mechanism that created the discount. They removed Iran’s other buyers, destroyed its bargaining power, and handed the resulting price concession to whichever counterparty was willing to hold the compliance risk. Functionally, the sanctions program transferred margin from Tehran to a specific tier of Chinese private refiners. It subsidized them. The blockade is what finally took the subsidy away, and it is doing more damage to Shandong’s independent refining sector than a decade of designations ever did.
The founder-level lesson underneath all of this has nothing to do with geopolitics. Your enforcement power over any counterparty is a ratio: how much of their business runs through you, divided by how much of yours runs through them. When that ratio is high you have a platform. When it inverts you have customer concentration risk, and the polite name for that is a negotiation. Bessent stated the denominator out loud on Monday when he asked why he would want to blow up the financial system. The network he would have to damage to punish China is the same network that gives the punishment its force.
The other lesson is about substitution. Every use of a network-exclusion weapon is also a marketing campaign for the alternative. Not because the alternative is better, but because the cost of building one stops looking theoretical.
The Risk
The bear case against this reading is real and worth stating plainly.
Dollar dominance is not in question. The renminbi accounts for under 3% of global payments through SWIFT against 51% for the dollar. Around 80% of CIPS traffic still relies on SWIFT for messaging. The substitute rail is not a rail yet. It is a hedge.
The August collapse may not be all blockade. Teapot demand was already weakening before July. Chinese authorities allowed loss-making independents to cut run rates in June, crude and fuel stockpiles were comfortable, and Beijing has been tightening import quotas for independents to consolidate the sector around the state majors. Part of what looks like enforcement success may be a demand-side story wearing a supply-side costume. Anyone building a thesis on the 534,000 figure should hold it loosely until September data lands.
The threat still works without being executed. Even without designating a major Chinese bank, international banks tend to pre-comply. As the Asia Group’s Han Lin put it, big global banks will become materially more conservative about transactions with Chinese financial institutions, because nobody wants to test an American regulator. Deterrence delivered through private risk committees does not show up in a designation count.
Blockades are expensive and do not scale. Redirecting 65 vessels is a military operation with a running cost, a legal exposure, and a hard ceiling. It works against Iran because Iran cannot contest it. There is no version of this instrument that gets pointed at a peer.
And it may not hold. Dark-fleet operators have adapted to every previous constraint. Cargoes running without transponders, restocked floating storage, or a negotiated end to the war would all put the barrels back on the water quickly.
Quick Questions
Did the new sanctions target China? Only at the edges. More than a dozen small Hong Kong and mainland companies appear on the list. No major Chinese bank does.
Why won’t Washington sanction Chinese banks? Because the collateral damage runs both ways. The 2018 sanctions on Rusal, then the world’s second-largest aluminum producer, sent that market into disarray. A systemically important Chinese bank is orders of magnitude larger. Beijing also holds rare-earth export controls whose one-year pause expires just after next month’s Xi-Trump meeting.
So are the sanctions working? The blockade is working. The designation list, judged on flow volumes alone, has a weak track record against counterparties with no dollar exposure.
What does this do to the teapot refiners? It removes their reason to exist. They compete on discounted sanctioned feedstock, not on scale or efficiency. With Iranian crude briefly pricing above Brent, that advantage inverts and they are left holding compliance risk with no compensation for it.
Is the dollar losing its power? Not yet, and not on these numbers. What it is losing is reach. The number of transactions that must pass through a dollar correspondent account keeps shrinking, and every enforcement action shrinks it a little more.
The Business Model Analyst Take
There is a moment in the life of every dominant platform where the enforcement mechanism stops being the point of leverage and starts being the point of exposure. You notice it when the operator stops enforcing against the biggest counterparties and starts negotiating with them instead, while continuing to enforce vigorously against the small ones who cannot fight back. Sixty shipping brokers and a handful of Hong Kong shells got designated on Monday. The banks moving the actual money did not.
That is not incompetence. It is a rational read of a ratio that has moved. The dollar network is still the most valuable piece of economic infrastructure on the planet, and the reason it cannot be used at full power against China is that using it at full power is what would end its monopoly. The weapon and the asset are the same object.
Which is why the interesting part of this week is not the press conference. It is the fact that when Washington genuinely needed to move barrels rather than headlines, it did not reach for the payment rail at all. It sent ships. Financial leverage is a tax on a channel you control. Physical leverage is a constraint on a supply chain. Once your counterparty has exited your channel, only the second one is still yours to pull.
Every operator running a platform should read that as a warning about their own take rate. Pricing power is not a permanent property of a network. It is a function of how many participants still have to be in it, and that population is always quietly shrinking at the edges, one counterparty at a time, long before anyone announces they have left.