Roark spent roughly $17.6 billion assembling a multi-brand restaurant platform and now wants $20 billion for it. The franchise filings show one brand carrying the whole thing.
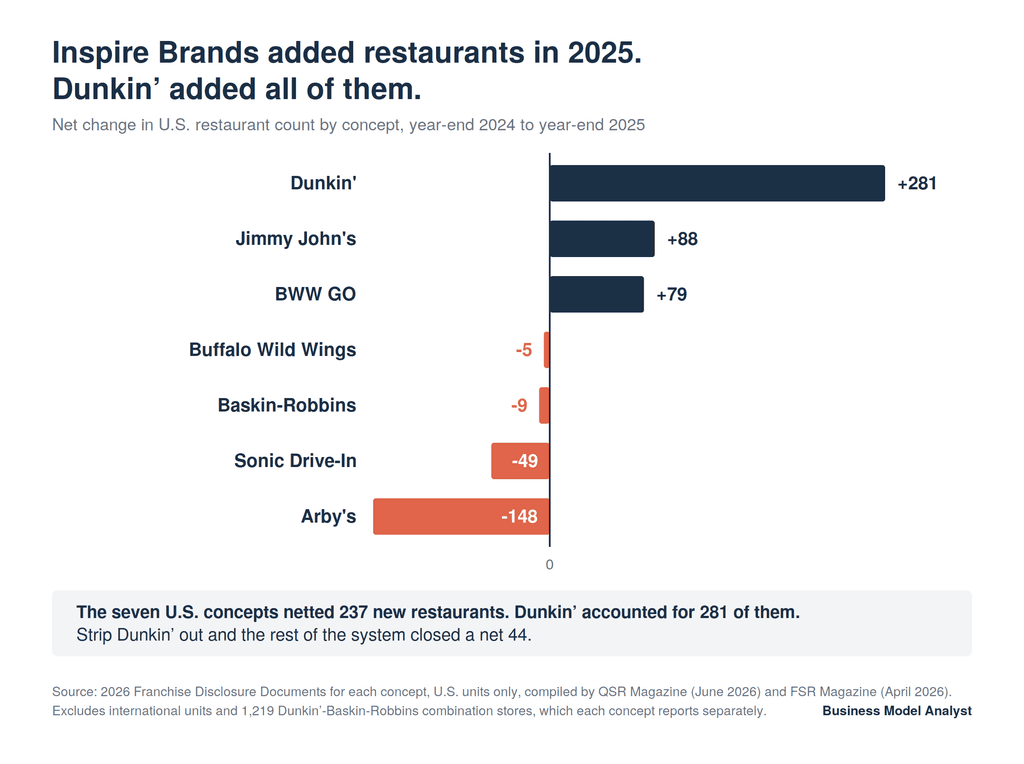
Inspire Brands runs Dunkin’, Arby’s, Sonic, Jimmy John’s, Buffalo Wild Wings and Baskin-Robbins, and it is preparing an offering that could come as early as the end of this year. The pitch is diversification: six categories, 33,000-plus restaurants, one platform. The 2026 franchise disclosure documents tell a narrower story. Across the seven U.S. concepts, the company netted 237 new restaurants in 2025. Dunkin’ alone added 281. Remove it and the rest of the system closed a net 44 locations.
A friend of mine who owns two sandwich franchises put it well when the filing news broke in May. He asked which brand he was being invited to buy. That question has an answer, and the answer is not six.
What Happened
The Wall Street Journal reported this morning that Inspire Brands is eyeing an offering as early as the end of 2026, naming it alongside smart-ring maker Oura in a wave of listings queued up after Labor Day. The company had already taken the formal step: a confidential S-1 submitted to the SEC on May 8, with JPMorgan and Bank of America hired to run the book. Reported targets put the raise near $2 billion and the valuation near $20 billion.
Inspire says the proceeds go to repaying borrowings under its existing term loan facility, plus fees. That is a debt-reduction offering, which tells you what the balance sheet looks like after eight years of acquisitions.
Two numbers frame the ask. Inspire reports about $33.4 billion in annual system sales across more than 33,300 restaurants. And on July 30, Jersey Mike’s priced the largest restaurant IPO in two decades at $23 a share, opened at $21, and closed its first day down about 6%, landing at a $7.3 billion valuation on roughly $4.2 billion of system sales.
The Backstory
Inspire began in February 2018 when Arby’s Restaurant Group, already controlled by Roark Capital, closed a $2.9 billion deal for Buffalo Wild Wings. Sonic followed for $2.3 billion. Jimmy John’s arrived through a transfer from one Roark entity to another, with disclosed consideration of $830.1 million for the common units and unit-based awards plus a $313.4 million tax receivable agreement. Then Dunkin’ Brands, including Baskin-Robbins, for $11.3 billion in 2020.
Add the disclosed figures and you get roughly $17.6 billion of acquisition consideration. Dunkin’ Brands is $11.3 billion of it, or 64%. One of the four deals was Roark selling an asset to a company Roark already backed.
Paul Brown, who ran brands and commercial services at Hilton before co-founding Inspire, has been chief executive throughout. The stated logic of the group has been scale in shared functions: one supply chain, one data and loyalty stack, one development team placing multiple brands on the same real estate. Dunkin’ arrived last, cost the most, and came with the only asset in the portfolio that was compounding units.
Worth flagging the basis before going further. Every unit figure below comes from the 2026 franchise disclosure documents, covering U.S. restaurants only, compiled by QSR Magazine in June and FSR Magazine in April. Inspire’s own submission to the QSR 50 puts Arby’s 2025 decline at 100 units rather than the 148 in the FDD, and its headline Dunkin’ count of 9,999 includes the 1,219 Dunkin’-Baskin combination stores that the FDD tables report separately. The two sets are measuring different things. This piece uses the FDD consistently.
The Plan
The equity story writes itself from the top line. A $33.4 billion system across six categories, most of it franchised, throwing off royalties that require almost no capital. Coffee hedges wings. Ice cream hedges sandwiches. When one category softens, another carries the quarter.
Underneath that story, the 2025 development plans point one direction. Dunkin’ projects 406 gross franchised openings for 2026 and carries 228 signed agreements with no restaurant open yet. Jimmy John’s projects 87 and carries 75 signed agreements. Arby’s projects 11 gross new outlets and nine signed agreements, with no company openings planned. Sonic projects 16 and holds 12 agreements. Buffalo Wild Wings projects 16 franchise openings and no company debuts.
Two brands hold 303 of the group’s signed-but-unopened agreements. The other four hold 58 between them.
The Business Model Angle
One brand is doing the compounding. Dunkin’ went from 8,118 U.S. restaurants to 8,780 over three years, a gain of 662. In 2025 it added a net 281 while Arby’s closed 148, Sonic closed 49, Baskin-Robbins closed nine and Buffalo Wild Wings closed five. Jimmy John’s added 88 and the BWW GO offshoot added 79, which is real, though GO is 219 stores against a group of 20,598 U.S. units. Dunkin’ accounted for 119% of the group’s net U.S. unit growth. That is the whole diversification argument inverted: a portfolio is supposed to spread the sources of growth, and this one has concentrated them. Roark put 64% of its acquisition dollars into the brand that now produces more than all of the unit growth. The capital allocation was correct. The platform framing is what does not survive contact with the filings.
The company owns restaurants in the wrong brands. Inspire operates 1,943 of its 20,598 U.S. restaurants directly, which is 9.4% and already high for a franchisor. The distribution is the part nobody has run. In the four concepts that shrank last year, Inspire owns 1,842 of 8,822 restaurants, or 20.9%. In the three that grew, it owns 101 of 11,776, or 0.9%. Arby’s and Buffalo Wild Wings together account for 79.8% of every company-operated restaurant in the group.
That split matters because of a margin structure this site has documented at McDonald’s, where the franchisor cleared 82.5 cents on the dollar of franchised revenue in 2025 while its own restaurants cleared 11.6 cents (see McDonald’s Q2 2026: Guest Counts Fell, the Landlord Margin Didn’t). Company-operated restaurants carry food cost, labor, occupancy and the full operating leverage of a fixed-cost box. Franchised restaurants send a royalty check. Inspire has parked the volatile, capital-hungry P&L inside the two brands with negative unit momentum and kept the clean royalty stream inside the two that are growing. A public investor buys both, blended, at one multiple.
Arby’s spent 2025 fixing that, which is its own tell. The chain sold 115 company restaurants to franchisees during the year. Across 2023 and 2024 combined, it sold one. A franchisor refranchising 115 units in the twelve months before it files an S-1 is dressing the P&L for the offering, the same maneuver Restaurant Brands ran with Carrols before it started selling those restaurants back down (see Burger King’s Q2 2026 Comp Is a Refranchising Pitch).
The synergy has a footprint, and the footprint is flat. Multi-brand co-location is the thing Inspire can do that a single-brand franchisor cannot. Two concepts, one lease, one crew, two dayparts. The company has been talking about it for years. Count the restaurants.
The flagship format is Dunkin’-Baskin, which has existed since Allied-Lyons put the two brands under one roof in 1990. There are 1,219 of those stores in the U.S. That count grew by 31 in 2023, then fell 14 in 2024 and 50 in 2025, a three-year net loss of 33. Openings went 52, then 31, then 12. For 2026 the FDD projects 26 gross combo openings and zero signed agreements without a store open yet.
The new-generation combos run the other way and are much smaller. Dunkin’ with Jimmy John’s has produced about 32 stores since 2023 across sixteen states. Arby’s with Dunkin’ has produced about five since 2024. Sonic with Jimmy John’s has produced one. Call it 38 restaurants over three years.
Net multi-brand progress across three years: roughly five restaurants, on a base above 20,000. The oldest and largest co-location format is contracting slightly faster than the new ones are being built. Whatever synergy Inspire is selling, its own real estate is not yet expressing it.
The Risk
The acquisition-cost comparison is the weakest number here, and it should be treated that way. The $17.6 billion of disclosed consideration against a reported $20 billion target implies about 13% of headline appreciation across eight years. That figure excludes assumed debt in several of the deals, excludes whatever the Arby’s platform was worth in 2018 before any of this started, and excludes every dividend, recapitalization and management fee Roark has taken out along the way. Private equity returns come from leverage and cash extraction, not from headline-to-headline arithmetic. Roark’s actual IRR on Inspire could be strong while that 13% looks thin. The $20 billion is also a reported target, not a priced deal.
Concentration is not automatically a defect. Dunkin’ is 8,780 of 20,598 U.S. restaurants and more than $13 billion of U.S. system sales. A company whose largest brand opens roughly 300 restaurants a year and holds 228 signed agreements is a growth company, whatever the other five do. Plenty of investors would rather own one compounding asset with five stable cash generators attached than six mediocre ones. The counter is that they can already own that shape more cheaply: at $20 billion on $33.4 billion of system sales, Inspire is asking for 0.60 times system sales, while the market paid Jersey Mike’s 1.74 times for a single brand that is 99% franchised (see Jersey Mike’s IPO: Inside the $12 Billion Sandwich Play). Buyers pay up for concentration when the concentrated thing is growing.
The company-owned units may be strategy rather than drag. Holding the restaurants in a struggling brand is how you fix it, because you cannot force 2,300 franchisees to remodel and you can force yourself. Arby’s selling 115 stores in 2025 is consistent with fix-then-refranchise, not only with pre-IPO cosmetics. If Buffalo Wild Wings works through the same sequence, the ownership mix looks different in three years.
BWW GO is a genuine second act. The offshoot went from 140 units to 219 in 2025 and from 90 franchised to 194, while corporate halved its own count from 50 to 25. Buildout runs $375,845 to $919,500 against $2.464 million to $4.9 million for a traditional Buffalo Wild Wings. Franchised GO stores averaged $928,702 in 2025. A capital-light format that existing franchisees will fund is exactly what a shrinking full-service brand needs, and Inspire says most GO commitments come from operators it already has.
All of this is U.S.-only. The FDD covers roughly 20,600 restaurants. Inspire reports more than 33,300 worldwide. Baskin-Robbins in particular has a large international base that the U.S. tables do not touch, and the international picture could invert several of these readings. Until the S-1 goes public, nobody outside the company knows the segment economics, the leverage, or how much of that $33.4 billion sits abroad.
Quick Questions
Is Inspire Brands a good business? It is a large one with a compounding coffee brand at the center and four legacy positions attached. The individual pieces are not in question. What is in question is whether bolting them together produced anything the pieces would not have produced separately, and three years of combo data says not much yet.
Why does the company-owned split matter to an investor? Because company-operated restaurants and franchised restaurants are different businesses with different margins and different capital needs, and Inspire has concentrated the harder one inside its weakest brands. Blending them into a single multiple hides that.
Does the Jersey Mike’s debut predict anything? It sets the most recent public price for a franchisor and shows appetite exists at a premium for a single-brand grower. It also broke issue on day one, which is a caution about pricing rather than about the category.
Is Dunkin’ worth owning on its own? Dunkin’ Brands traded publicly from 2011 until Inspire bought it in 2020, so investors have seen this asset unbundled before. The rest of the portfolio is what changed. For the underlying mechanics, see our Dunkin’ Donuts business model breakdown and the current Dunkin’ Donuts SWOT analysis.
What settles the argument? The public S-1. If Inspire reports segment results by brand, the concentration becomes visible in dollars rather than in unit counts. If it reports one blended number, that choice is itself the answer.
The Business Model Analyst Take
Portfolio companies get built on a promise that the whole is worth more than the parts, and that promise is testable. Shared supply chain should show up as margin. Shared development should show up as buildings holding two brands. Shared loyalty data should show up as traffic moving between concepts. Inspire has had six to eight years and $17.6 billion to produce those effects, and the clearest evidence available before the S-1 goes public is that its combined restaurants netted about five units over three years while one brand supplied all the growth.
That does not make Inspire a bad company. It makes it a Dunkin’ company with five attachments, being marketed as something else. Public markets have a long record of pricing that structure below the sum of its parts, which is why Yum spun out China and then sold Pizza Hut, and why the highest multiples in the sector sit on single-brand franchisors like Domino’s and Wingstop. Roark is bringing a conglomerate to a market that discounts conglomerates, three weeks after that market paid a premium for the opposite.
For any founder assembling a group, the lesson is cheaper than $17.6 billion. Acquiring adjacent brands buys revenue on day one. It does not buy the operating linkages that justify the multiple. Those have to be built afterward, they show up in physical evidence like shared leases and shared crews, and if they are not visible in three years of unit data they are not there. Inspire will find out in a prospectus whether anyone else counted.