India processes billions of digital transactions every month through public rails that have no real peer in scale or adoption. For any company assessing entry, that matters more than headline growth. It changes how customers pay, how firms verify identity, how compliance is enforced, and how quickly new business models can spread.
India now demands first-tier strategic attention. The opportunity is clear, but the operating model cannot be generic. A standard emerging-market template often misses the central feature of India's business environment: state-backed Digital Public Infrastructure, or DPI, has become an accelerant across politics, economics, society, technology, environment, and regulation.
That changes the purpose of a PESTEL analysis. It is no longer just a way to list external forces. In India, it is a way to test whether a business model fits a market where public digital rails shape private competition. UPI affects unit economics in payments and commerce. Aadhaar changes onboarding and fraud controls. Digital service delivery changes how quickly policy intent can become operational reality, although execution still varies by state. Companies that understand these mechanisms can lower customer acquisition costs, shorten verification cycles, and reach smaller cities faster. Companies that do not often misprice risk.
The implication is broader than technology adoption. DPI increases state capacity in some areas while also raising the bar on data governance, interoperability, and compliance design. Political decisions can move into operating conditions quickly, which makes a grounded view of political factors affecting business decisions especially relevant in India. Regional geopolitics also matter for supply chains, capital flows, and regulatory posture, and the South Asia policy guide for G20 gives useful context on that wider setting.
A serious India PESTEL analysis therefore starts with one question. Can your business model work in a market where digital infrastructure is public, scale is immediate, and local variation remains high?
India PESTEL Analysis A Strategic Overview
A useful India PESTEL analysis starts with a reframing. India is not merely a high-growth market. It is a market where scale, heterogeneity, and digital infrastructure coexist. That combination creates upside for firms that localize well and sharp penalties for firms that assume one national playbook will work everywhere.
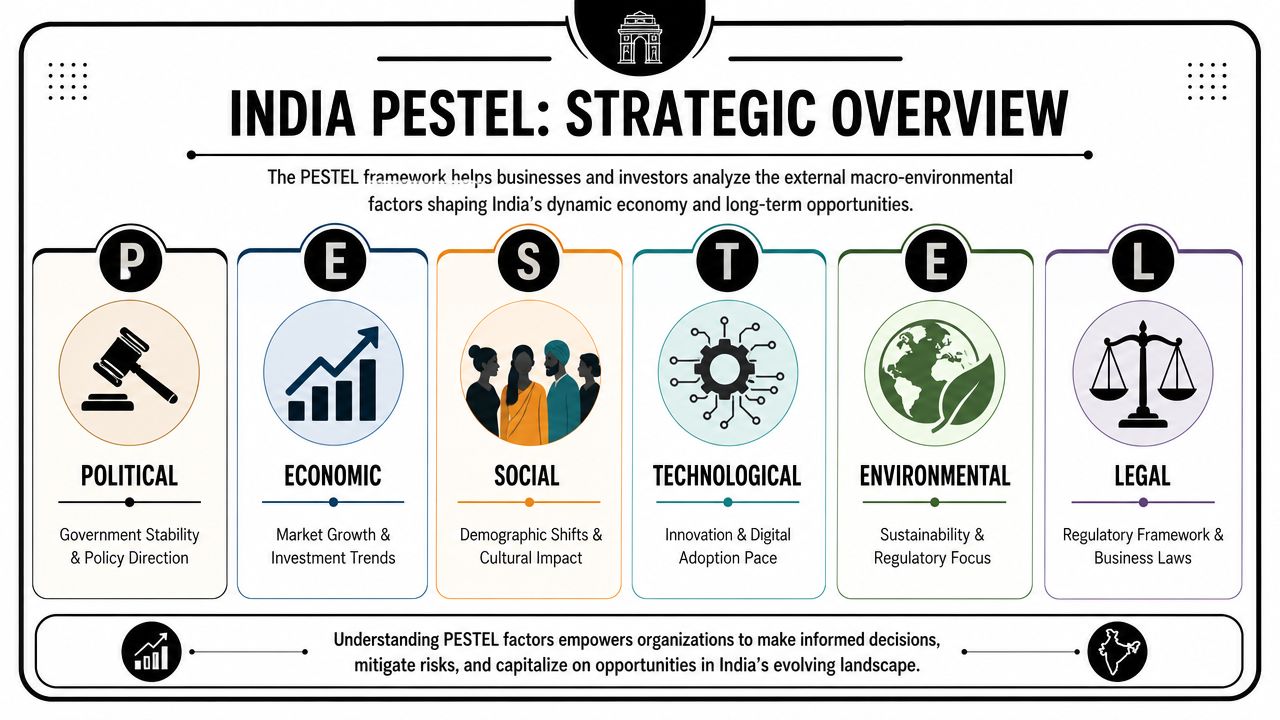
Executives often use PESTEL as a checklist. In India, that's too shallow. The better use is to test a business model against six different forms of friction: policy friction, demand volatility, social fragmentation, digital acceleration, sustainability pressure, and compliance complexity. If you need a quick refresher on the framework itself, this concise guide to PESTLE analysis is a practical baseline.
Why India looks different from a standard PESTEL map
India's macro story is easy to summarize and easy to misread. A large economy with strong growth attracts investment. A vast population signals demand. But strategic success depends on whether a company understands how those macro facts convert into operating conditions.
Three points stand out:
- Scale changes entry sequencing. India's size means national ambition can make sense, but execution usually has to be regional, category-specific, and phased.
- DPI changes competitive baselines. Fast payments and digital onboarding reduce some frictions while increasing the penalty for outdated operating models.
- Federal complexity persists. India offers one large market in aggregate, but regulation, enforcement, consumer behavior, and channel economics still vary materially across states.
For leaders trying to place India in a wider geopolitical context, the country's role in major blocs also matters. This primer on what is BRICS helps frame why India increasingly matters not just as a domestic demand story, but as a strategic node in global capital, trade, and diplomacy.
Executive snapshot
| PESTEL factor | What matters most | Business implication |
|---|---|---|
| Political | Policy direction is consequential, but state-level execution can diverge | Build a market-entry model that includes state selection, not just country selection |
| Economic | Large GDP and strong growth coexist with inflation, rate, and currency exposure | Stress-test pricing, margins, and working capital from day one |
| Social | Demand is deep but segmented by region, language, income, and trust | Localize offer design, channels, and messaging |
| Technological | DPI has made digital payments and digital service delivery operational basics | Integrate payments, onboarding, and data workflows early |
| Environmental | Sustainability pressure is rising through regulation and public scrutiny | Treat environmental compliance as operating design, not CSR |
| Legal | The rules are navigable, but compliance quality affects speed and scalability | Invest in legal architecture before expansion accelerates |
India rewards companies that treat infrastructure, regulation, and customer behavior as one integrated system rather than six separate PESTEL boxes.
The Political and Legal Landscape
Political and legal conditions in India don't merely set boundaries. They determine how quickly a strategy can move from presentation deck to operating reality. The central government can define direction, but state governments, regulators, and local authorities shape a large share of actual execution.
Political strategy in India is partly national and heavily local
A common error in India market entry is to study central policy and stop there. That misses the operational layer where approvals, incentives, inspections, labor administration, and infrastructure access often differ by state. For companies deciding where to launch, that means “India entry” is usually shorthand for choosing a first operating corridor, a first compliance environment, and a first political counterpart ecosystem.
Many market-entry models break. They assume political risk is about headline instability. In practice, the sharper issue is administrative variability. Two states can offer very different timelines, relationships with industry, and implementation quality even under the same national framework.
A helpful comparative read for executives watching the region through a policy lens is this South Asia policy guide for G20. It's useful not because it predicts firm-level outcomes, but because it places India's policy posture inside a broader regional context.
What legal complexity looks like in practice
The legal environment matters less as a theoretical risk and more as an operating cost. Companies usually feel it through licensing, taxation, contracts, employment, land use, product compliance, and data handling. The central lesson is simple: India is navigable, but shortcuts age badly.
For many firms, the legal agenda clusters into a few recurring questions:
- Entity and market structure: What form should the operating presence take, and where should activities sit?
- Commercial enforceability: How will contracts, channel agreements, and service commitments be drafted for practical enforcement?
- Regulatory sequencing: Which approvals must be in place before launch, and which can be staged?
- State divergence: Which compliance items look national on paper but vary in administration locally?
DPI changes politics and law at the same time
Digital Public Infrastructure alters the political and legal environment in a subtle way. It increases the state's ability to digitize interactions with firms and consumers, but it also raises expectations that companies will operate in formats that fit those rails. That means regulatory compliance, customer verification, and transaction recording increasingly interact with digital systems rather than paper-heavy workarounds.
A company that ignores this shift can still enter India. It just enters at a disadvantage.
Practical rule: In India, legal readiness isn't a post-entry clean-up task. It's part of market design. Choose states, partners, and rollout phases based on compliance executability, not only on demand potential.
For a deeper look at how public decisions shape commercial conditions, this overview of political factors affecting business is a useful complement to an India-specific analysis.
Economic Environment and Market Dynamics
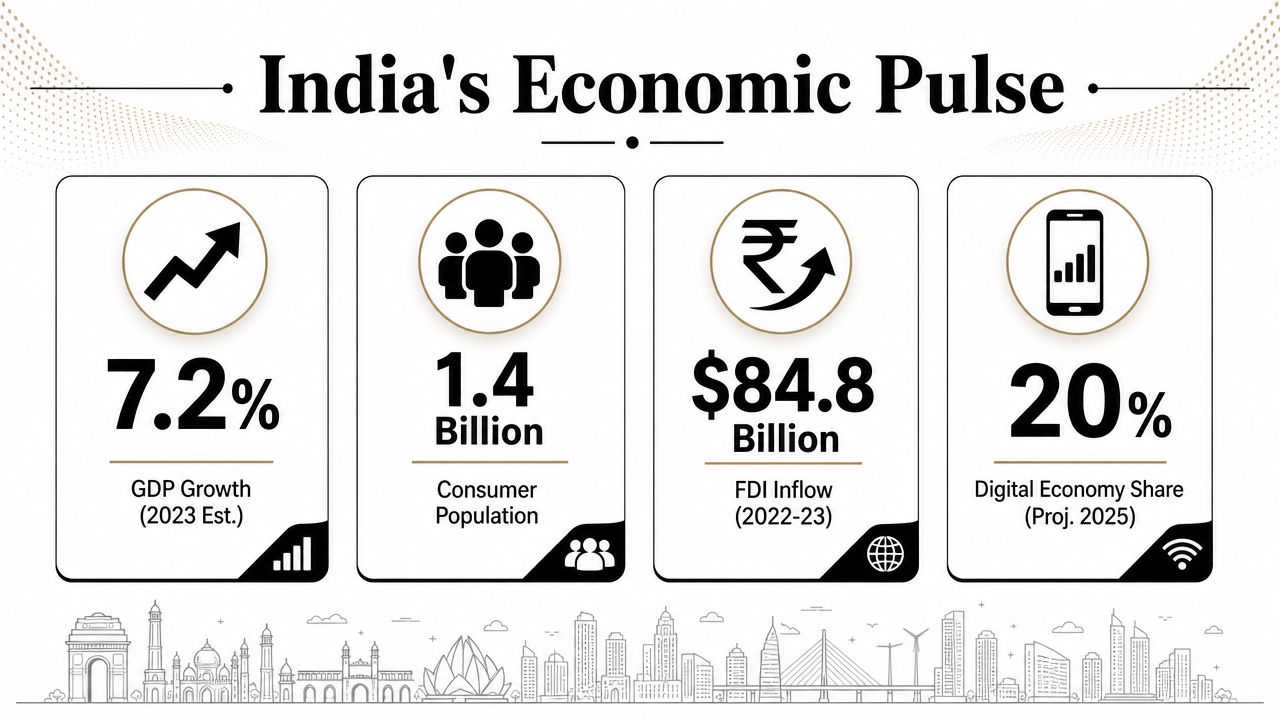
A market expanding at more than 6% a year changes competitive math, but in India the bigger strategic issue is how growth is mediated by digital rails that compress distribution costs, formalize transactions, and intensify price transparency at the same time.
The economic case for India rests less on headline scale, already noted earlier, and more on how demand, payments, identity, and service delivery are being rewired together. That combination allows companies to reach customers faster than in many other large emerging markets. It also makes weak business models fail faster. India's Digital Public Infrastructure, especially Aadhaar-linked verification, UPI-based payments, and account aggregation layers, reduces friction in onboarding and collection. As a result, revenue can scale quickly, but so can customer switching, discount pressure, and scrutiny of unit economics.
A visual summary helps frame the scale question, even if any strategy still needs deeper segmentation work.
Growth quality matters more than growth headlines
India remains one of the fastest-growing major economies. The IMF projected GDP growth of 6.5% in 2025, while businesses still face exposure to inflation, interest rates, and currency movement, as outlined in this PESTEL macro-risk reference. For market entrants, the practical implication is straightforward. Demand expansion does not guarantee margin expansion.
DPI changes the economic equation here. Faster payments through UPI can improve cash conversion cycles for merchants, platforms, and service providers. Digital KYC can cut onboarding cost in banking, fintech, telecom, insurance, and gig platforms. Public digital rails can therefore reduce operating friction that would otherwise erode profits in a volatile macro setting. The same rails also lower barriers for local competitors, which means any cost advantage created by digitization can be competed away quickly.
This short video is useful for executives who want a faster visual read on India's economic backdrop before working through a full operating model.
India is one economy on paper and many economies in practice
Executives often overestimate how transferable a single national proposition will be. Income bands, logistics density, channel economics, and digital adoption vary sharply by city tier and state. A product that works in Bengaluru or Gurgaon can struggle in a lower-density market where fulfillment costs, distributor influence, and local trust signals look very different.
That is why India should be treated as a sequencing problem, not only a scale opportunity. The first strategic question is not total addressable market. It is where customer acquisition, servicing, and collections can work together at acceptable payback.
DPI sharpens this point. Public digital infrastructure creates national rails, but monetization still depends on local commercial conditions. UPI may standardize payment acceptance, yet basket size, repeat frequency, and willingness to pay remain highly uneven. The result is a market where technology can nationalize access faster than it nationalizes demand.
For firms building digital operations, this explanation of how infrastructure shapes modern digital business models is a useful companion to India-specific market planning.
Volatility shows up in the operating model
The largest planning errors in India usually come from treating macro volatility as a finance issue instead of an operating issue. Inflation can change consumer mix. Interest rates can weaken the economics of financed purchases. Currency movement can pressure imported inputs, cloud costs, semiconductor exposure, and premium SKUs priced against global benchmarks.
The effect differs by model:
- Consumer brands may see healthy demand but weaker realized margins if discounts and input costs rise together.
- Import-heavy businesses can lose flexibility when FX shifts hit landed cost before pricing can be reset.
- Subscription and platform models may acquire users cheaply through digital channels, then discover retention economics are weaker outside top urban clusters.
- Capital-intensive entrants can face delayed breakeven if financing costs rise faster than utilization.
DPI can cushion some of this pressure. It can lower collection risk, improve transaction visibility, and support smaller-ticket digital commerce. It does not remove macro exposure. It changes where the pressure appears. In many cases, volatility moves from front-end demand generation to back-end pricing, fulfillment, and working capital management.
The strategic reading for market entry
The economic question is whether a business model can convert Indian demand into durable returns under conditions of fast digital adoption and uneven monetization. That requires more than a growth thesis.
| Economic dimension | Opportunity | Risk |
|---|---|---|
| High aggregate growth | Faster category creation and room for new entrants | Overbuilding capacity on optimistic forecasts |
| DPI-enabled distribution | Lower onboarding, payment, and servicing costs | Faster customer comparison and weaker differentiation |
| Regional demand variation | Multiple entry wedges by segment and geography | Poor expansion sequencing can destroy CAC to LTV |
| Macro volatility | Space for value, premium, and hybrid models | Inflation, rates, and FX can quickly compress margins |
A better board question is this: can the company hold margins if customer acquisition becomes cheaper, price discovery becomes sharper, and local competitors use the same public rails?
The strongest entrants usually localize sourcing where feasible, build tiered pricing by city and customer cohort, and stress-test working capital assumptions before scaling. They also make targeted capability choices early, including choosing technical partners for Web3 and AI when the model depends on data-heavy products, digital trust, or complex platform integration. In India, economic upside belongs to firms that combine demand capture with execution discipline.
Socio-Cultural and Environmental Forces
India's social context is not background texture. It shapes conversion, retention, trust, and brand legitimacy. Companies that enter with a clean national narrative but weak local adaptation often discover that product-market fit in India is cultural before it is commercial.
Demand is broad, but identity is local
India combines scale with fragmentation. Consumers don't encounter brands inside one shared language, one shared urban form, or one shared purchasing pattern. They evaluate value through local references, social norms, family influence, and region-specific expectations.
That has two direct implications for strategy. First, localization isn't cosmetic. It affects packaging, messaging, customer support, onboarding, service formats, and channel design. Second, the fastest way to waste growth capital in India is to assume metro behavior describes the entire market.
Some firms enter with a premium national brand and then learn they need a portfolio of micro-positioning choices:
- Urban digital-first buyers often respond to convenience, trust signals, and seamless payments.
- Aspirational value-conscious customers may want branded reliability but still evaluate every price step carefully.
- Regional consumer groups can reward brands that adapt language, service norms, and product framing to local context.
Digital behavior is social behavior now
In India, digital adoption is not only a technology shift. It is a social shift. Customers increasingly treat digital interaction as part of normal commercial life, but trust still has to be earned. That means onboarding, payment flows, customer support, and returns processes all signal whether a company understands how people buy.
DPI carries a social consequence. When digital rails become common, customer patience for clumsy experiences falls. A weak checkout flow, a cash-only bias, or poor digital service recovery doesn't feel old-fashioned. It feels unreliable.
Indian consumers don't just compare your product with direct competitors. They compare your experience with the smoothest transaction they had anywhere else this week.
Environmental pressure is becoming commercially relevant
Environmental factors in India are no longer confined to heavy industry. They increasingly affect consumer brands, retailers, logistics operators, manufacturers, and service businesses through packaging norms, waste expectations, water use, and broader sustainability scrutiny.
The strategic mistake is to treat environment as a reputation issue only. In India, it increasingly affects access, permitting, procurement, packaging choices, and operating discipline. Firms that delay adaptation often end up paying twice. First through redesign under deadline pressure, then through inconsistent field execution across states.
A practical response usually includes:
- Packaging review: Reduce formats likely to create friction with local waste expectations or evolving rules.
- Operational discipline: Build water, energy, and waste considerations into site design and vendor standards.
- Market positioning: Present sustainability in ways that support value and reliability, not just abstract corporate messaging.
What this means for market entry
Social and environmental forces combine in one important way. India rewards businesses that show respect for context. Customers want ease and trust. Communities want accountability. Regulators want compliance that can survive inspection, not just presentation.
That combination favors firms that localize without fragmenting themselves operationally. The art is to create one strategic spine and multiple local expressions.
Technological and Infrastructure Drivers
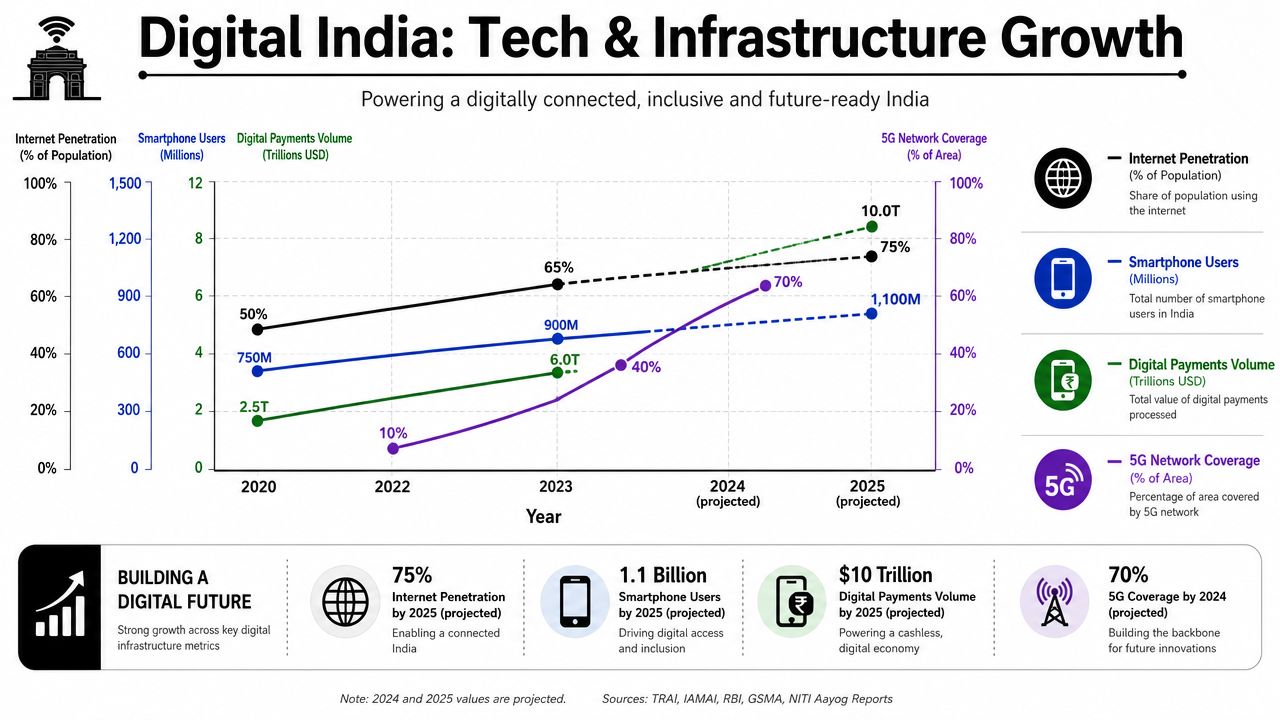
India's technological environment is often described too narrowly as digitization. That misses the fundamental shift. India's business environment is being reshaped by public digital rails that lower transaction friction and compress the time between customer intent and commercial completion.
DPI is the operating system, not a side feature
The strongest technology insight in any India PESTEL analysis is that Digital Public Infrastructure has changed the default operating environment. Companies aren't merely choosing whether to go digital. They're entering a market where digital payments, identity-linked processes, and digitally mediated service delivery increasingly define what “normal” looks like.
India's Unified Payments Interface, or UPI, processed more than 13 billion transactions in a single month in 2025, making it a critical payment rail for firms operating in the country, according to this UPI scale reference. That number matters because it changes strategic assumptions. Payments are no longer just back-end plumbing. In India, payment architecture affects customer acquisition, conversion, SME distribution, reconciliation, and fraud exposure.
What UPI changes for business models
UPI's scale has several practical implications. It reduces dependence on cash handling. It supports low-friction commerce for both consumers and small businesses. It also creates pressure on firms whose checkout, partner-settlement, or field-collection models still assume slower, more expensive payment behavior.
That is why technology strategy in India now starts with applied questions:
- Can customers pay instantly in the flow they already prefer?
- Can distributors, agents, or sellers settle without manual friction?
- Can the business connect payment data to retention, credit, or service decisions?
A company that answers yes doesn't merely modernize its stack. It improves conversion and operating control at the same time.
Infrastructure means digital and physical together
DPI doesn't eliminate physical bottlenecks. It changes how painful those bottlenecks feel. Poor logistics, uneven warehousing quality, regional delivery complexity, and infrastructure gaps still affect service levels. But digital rails let companies see, route, collect, and verify faster than before. That can partially offset friction, but it doesn't erase it.
The best operators in India design for both layers:
| Infrastructure layer | What to assess | Strategic consequence |
|---|---|---|
| Digital rails | Payments, onboarding, service delivery, KYC workflows | Faster conversion and lower transaction friction |
| Physical networks | Warehousing, transport links, fulfillment reach, local last mile | Determines whether demand can be served profitably |
| Operational integration | Data flows between channels, payments, support, and logistics | Turns fragmented operations into scalable ones |
Partner selection becomes more strategic than many firms expect. Businesses building India-facing products often need implementation partners who understand not just code delivery, but interoperability with payment rails, identity workflows, and compliance-sensitive data handling. For teams evaluating technical capability in adjacent domains, this guide to choosing technical partners for Web3 and AI is useful as a due-diligence lens.
The underappreciated risk in India tech strategy
The standard story says India is digital-first. That's directionally right, but incomplete. The sharper reality is that digital adoption is deep and uneven. Customers may be digitally active yet still require trust-building, assisted onboarding, hybrid service models, or regional channel support.
The strategic effect of India's Digital Public Infrastructure is often understated. As discussed in the provided DPI analysis reference, digital payments, identity, and service delivery are becoming baseline assumptions. Success is less about “being online” and more about integrating these rails into pricing, onboarding, and distribution.
For leaders thinking through operating design, this piece on how infrastructure shapes modern digital business models is a practical extension of the same idea.
Strategic Synthesis for Business Models
The ultimate value of an India PESTEL analysis appears when it changes business design. India doesn't reward generic ambition. It rewards companies that convert macro understanding into operating choices about pricing, channel structure, compliance sequencing, and platform integration.
The central strategic conclusion is this: India's DPI compresses friction, but it does not erase complexity. That means good business models scale faster than before, and bad business models fail faster than before.
What leaders should do with this analysis
Most firms entering India face one of three strategic questions. Where do we start. How much do we localize. What must be built into the model on day one rather than patched later. The right answer depends on business type.
Here is a practical decision view.
For D2C and consumer brands
D2C brands should assume that checkout, trust, and localized communication will determine early performance more than broad awareness alone. India offers a large addressable audience, but consumers split quickly by affordability, region, and expectations of convenience.
Focus areas:
- Offer architecture: Create a product ladder. One brand can still require multiple value tiers.
- Payment integration: Make digital payment flows smooth from the start.
- Regionalization: Localize service language, creative, and fulfillment promises where demand is concentrated first.
- Returns and support: Treat service recovery as a growth lever, not a cost center.
The risk for D2C isn't lack of demand. It's overextending into too many customer segments with one proposition.
For B2B SaaS and digital services
Software and digital service firms often assume India is easiest because distribution is lighter than physical goods. That's only partly true. Sales can move quickly when value is clear, but pricing sensitivity, procurement variability, and implementation support matter more than many foreign entrants expect.
Winning moves usually include:
- Flexible pricing logic that fits different customer sizes without cheapening the core offer.
- Fast onboarding aligned with local compliance and verification expectations.
- Channel-assisted growth where direct sales alone would be too slow or expensive.
- Payments and collections design that matches how Indian customers transact.
DPI helps here because digital rails can simplify onboarding and payments. But the key edge comes from redesigning the customer journey around those rails, not merely connecting to them.
For manufacturers and supply-chain businesses
Manufacturers should read India through both the economic and political-legal lenses. The headline opportunity is large domestic demand plus stronger logic for localization. The practical challenge is that plant location, state administration, supplier quality, and compliance execution will affect returns more than broad macro optimism.
The strongest manufacturing entrants usually make three disciplined choices:
- They choose states with execution quality in mind, not only incentive narratives.
- They localize supply in phases rather than forcing abrupt substitution.
- They build legal, environmental, and logistics diligence before committing capital.
A KPI view by PESTEL factor
A strategic framework becomes more useful when leadership teams can monitor it. Instead of treating PESTEL as a static pre-entry memo, teams should convert it into a review dashboard.
| PESTEL factor | What to monitor qualitatively | Why it matters |
|---|---|---|
| Political | Policy direction, state-level implementation quality, approval timelines | Helps avoid expansion into attractive but operationally difficult jurisdictions |
| Economic | Pricing pressure, borrowing conditions, import sensitivity, working-capital strain | Protects margin and cash discipline |
| Social | Regional conversion differences, support issues, channel trust patterns | Reveals where localization is paying off or failing |
| Technological | Payment completion, onboarding friction, partner integration quality | Indicates whether DPI is being used as an advantage |
| Environmental | Packaging compliance, site sustainability exposure, local scrutiny | Reduces redesign and reputation risk |
| Legal | Contracting bottlenecks, data-handling readiness, audit issues | Prevents scale from outrunning compliance |
The companies that win in India don't separate market entry from operating model design. They treat them as the same decision.
One practical tool option for teams formalizing this work is to document assumptions and risks through a repeatable framework library. The Business Model Analyst publishes strategy resources built around models such as PESTLE, SWOT, and the business model canvas, which can help teams standardize how they compare markets and business designs.
The hidden strategic shift created by DPI
Many firms still treat DPI as a technology enabler. That is too narrow. DPI changes the economics of trust. It shortens payment cycles, reduces transaction friction, improves traceability, and raises expectations that service delivery should be fast and digitally supported.
That changes all six PESTEL categories at once:
- Political: government capacity looks different when more interactions move onto digital rails.
- Economic: revenue collection and customer conversion can improve, but only for firms integrated into those rails.
- Social: customers learn to expect convenience as a baseline.
- Technological: integration becomes strategy, not IT hygiene.
- Environmental: digitization can reduce some frictions, but field operations still face physical compliance realities.
- Legal: digital records, identity-linked processes, and data handling become more important to compliance quality.
That's why the most valuable takeaway from this India PESTEL analysis is not that India is attractive. It's that India is structurally changing the way attractive markets operate.
Conclusion Navigating the Indian Century
India in 2026 presents a rare combination. It has the scale of a major global economy, the growth profile of a high-momentum market, and the digital infrastructure of a system that is rewriting commercial norms. But none of that makes India simple.
The political and legal environment requires state-level realism, not just national optimism. The economic picture supports expansion, but inflation, interest rates, and currency movement can still reshape profitability quickly. Social forces make localization a strategic necessity. Technological conditions, especially DPI, have moved from advantage to baseline expectation. Environmental pressures increasingly affect operating design. Legal readiness determines whether a company can scale without accumulating hidden friction.
The deepest insight is that DPI is not just one factor inside the technology box. It is the cross-cutting force that changes how the entire PESTEL framework behaves in India. It accelerates payments, compresses onboarding friction, raises customer expectations, and increases the premium on operational integration. Companies that still approach India with a conventional emerging-market playbook will miss that shift.
A strong India strategy isn't built once and filed away. It has to be refreshed continuously as regulations evolve, state conditions diverge, and digital infrastructure reshapes customer behavior. Leaders who treat India PESTEL analysis as a living management tool will make better choices about market entry, product design, partnerships, and capital allocation.
If you want more strategy breakdowns like this, The Business Model Analyst publishes practical analysis of business models, competitive frameworks, and market tools that entrepreneurs, consultants, executives, and teachers can use in real decision-making.