
In-N-Out sells one protein. It arrives fresh, never frozen, from company patty plants, and it goes onto a menu that has barely moved since the 1950s. Every strength in this analysis traces back to that decision, and so does every threat.
The timing makes the trade sharper than usual. The US cattle herd sits at 86.2 million head, the smallest count since 1951, and the beef cow herd that determines future supply has fallen to 27.6 million, the lowest since 1961. Ground beef hit $6.885 a pound in July 2026, roughly 83% above its 2017 level. Meanwhile the chicken category grew sales 5.3% in fiscal 2025 against 1.5% for burgers, and In-N-Out sells no chicken at all.
That is the tension a 2026 In-N-Out SWOT has to resolve. The company runs the most productive burger restaurants in America and buys the most expensive input in American food service, with no menu hedge and no franchisee to share the bill.
SWOT analysis A SWOT analysis sorts a company’s position into four boxes: strengths and weaknesses, which sit inside the business and management controls, and opportunities and threats, which sit outside it. The framework is only useful when the four boxes talk to each other. If you want the methodology first, start with our primer on what a SWOT analysis is and the walkthrough on how to do one.
In-N-Out at a glance
| Item | Detail |
|---|---|
| Founded | October 22, 1948, Baldwin Park, California, by Harry and Esther Snyder |
| Ownership | Lynsi Snyder-Ellingson, sole owner since 2017, granddaughter of the founders |
| Restaurants | 431 US units, all company owned, zero franchised |
| States | 10, plus New Mexico announced for 2027 |
| Systemwide sales | About $2.6 billion, fiscal 2025 (QSR estimate) |
| Average unit volume | $6.032 million, first in the US burger category |
| Rank | 29th in the QSR 50 by systemwide sales |
| Menu | Burgers, fries, shakes and drinks. No chicken, no breakfast, no delivery, no app |
| California starting wage | $22 to $23 an hour, against a $20 legal floor |
In-N-Out and Shake Shack figures in the QSR 50 are estimates rather than company submissions. No audited financials exist for a private company that has never issued public debt, so treat every dollar figure here as a well-sourced approximation and read the sensitivity ranges instead of the point estimates.
Strengths
The most valuable brand per restaurant in fast food
YouGov’s 2026 US restaurant rankings, drawn from more than 40,000 consumers, asked Americans which chain does burgers best. Five Guys led at 15.5%, Burger King followed at 15.0%, and In-N-Out took 12.1%.
Read as a ranking, In-N-Out lost. Divide by restaurant count and the picture inverts.
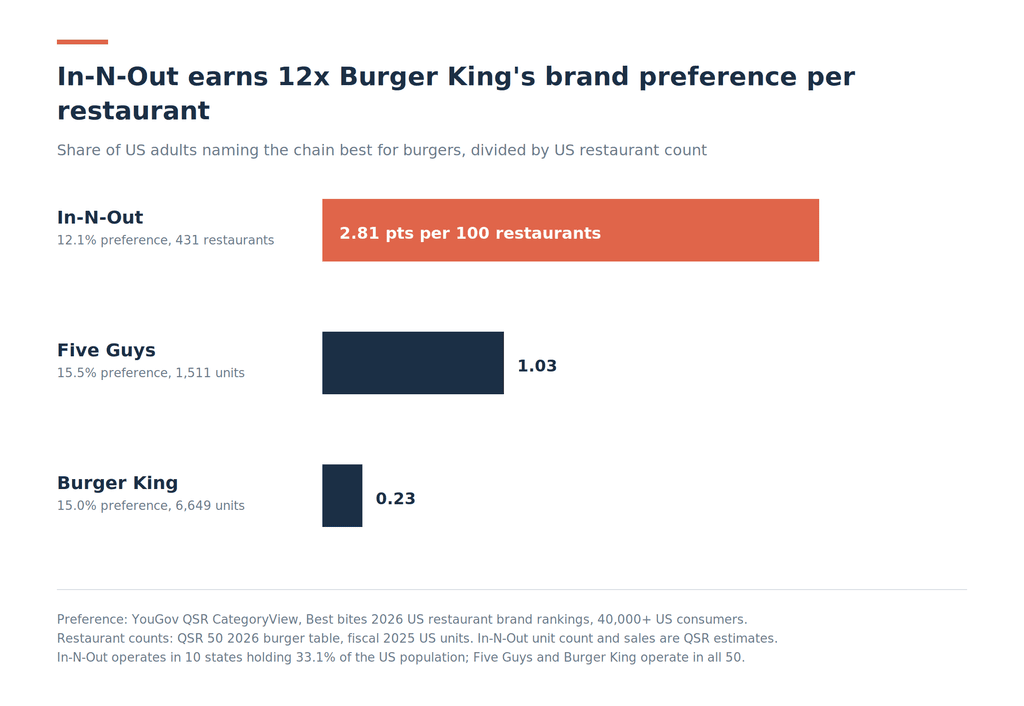
In-N-Out converts 2.81 preference points for every 100 restaurants it operates. Five Guys converts 1.03 and Burger King 0.23. The gap widens once you account for where the votes come from. In-N-Out operates in ten states holding 33.1% of the US population. Five Guys and Burger King operate in all fifty. If preference tracked footprint, In-N-Out’s 12.1% national score implies something near 36.5% inside the territory it actually serves, against rivals who earned their scores everywhere.
Scarcity does the marketing. In-N-Out runs no loyalty program, no app, no limited time offers and almost no national advertising, and it still generates the highest sales per building in the burger category. Compare that with the customer satisfaction moat described in our Chick-fil-A SWOT analysis, which Chick-fil-A pays for with 2,863 restaurants and a national media budget.
Volume that makes every fixed cost cheap
At $6.032 million a year, one In-N-Out restaurant does about $16,500 of business a day. A McDonald’s US restaurant does about $11,200. In-N-Out runs 48% more sales through a similar building, and it collects all of that revenue on its own income statement rather than a royalty slice of it.
That volume is the quiet answer to most of the cost questions people ask about the company. Wages, benefits, real estate and equipment all sit on a sales base three to four times the burger category median, so the same generosity costs In-N-Out a smaller share of revenue than it would cost anyone else. Our forthcoming In-N-Out business model teardown runs that decomposition on store manager pay in detail.
California’s wage law hurt the competition, not In-N-Out
AB 1228 set a $20 hourly floor for fast food chains with 60 or more US locations, effective April 1, 2024. Most coverage filed it as a cost shock. For In-N-Out it was a competitive event, and not a good one.
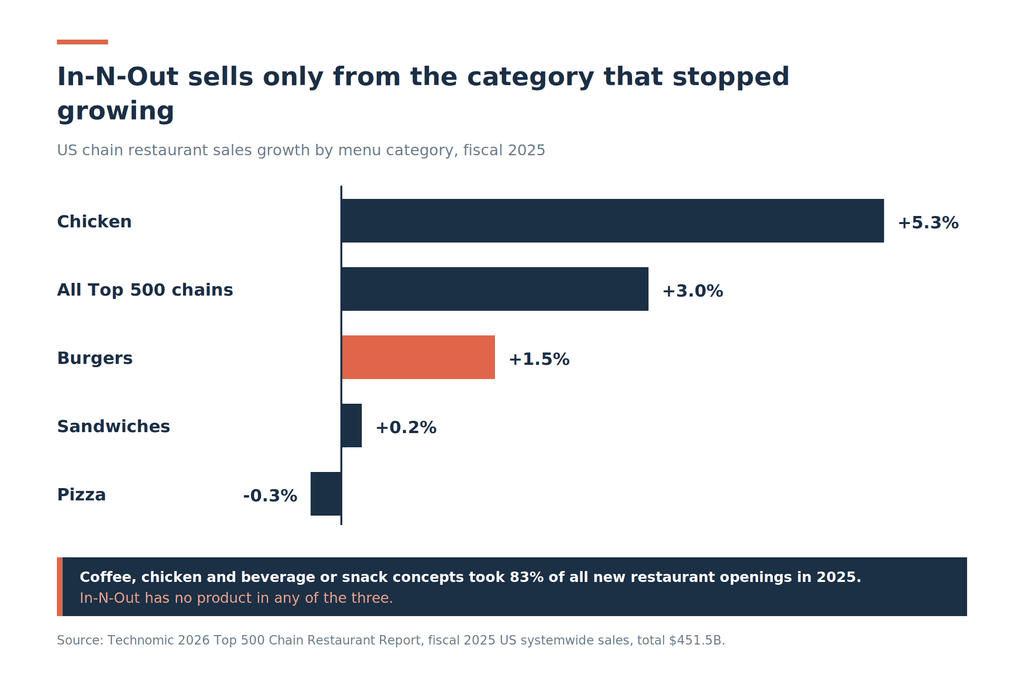
COO Denny Warnick put In-N-Out’s California starting wage at $22 to $23. The mandate required the company to raise nobody. An operator starting crew at $16.00 had to find $4.00 an hour, a 25% increase on its entry wage. In dollar terms, In-N-Out’s advantage over the applicable floor fell from $6.50 to $2.50, so the state erased 62% of a recruiting edge the company had spent decades building and charged it nothing for the privilege.
The pricing response tells the same story from the other side. Warnick said a Double-Double, fries and a drink went up 25 to 50 cents. Chick-fil-A raised California prices 10.6% and Chipotle went up 6% to 7% in the same window. In-N-Out had the room to hold and used it.
No franchisee conflict to manage
Every restaurant is company operated, which removes the entire class of problems that dominates the McDonald’s SWOT analysis and the Burger King and Wendy’s turnaround stories: franchisee cash flow, remodel funding fights, closure negotiations and the gap between what corporate wants on the menu and what an operator can afford to execute. When In-N-Out changes a specification, it changes. Nobody votes.
Weaknesses
One protein, no hedge
The menu carries beef and nothing else with meaningful protein content. A chain with chicken, breakfast eggs or a plant option can shift promotional weight toward whatever input is cheap this quarter. In-N-Out cannot. When beef runs, the whole menu runs with it.
The freshness rule removes the second hedge. No freezers means no forward buying of patties at last quarter’s price, which is exactly what a frozen-supply competitor does when the cattle market turns. In-N-Out buys close to spot, all the time, by design.
Geography is capped by patty plants, not by demand
In-N-Out will only open where it can supply a restaurant from a patty facility within about 300 miles. Waiting lines at every new market opening say demand is not the binding constraint. Factory capacity is.
The company has spent heavily to move that constraint east, including a distribution facility in Lebanon, Tennessee and an eastern territory office in Franklin. Three Tennessee restaurants opened in December 2025, ahead of schedule, with up to 35 planned and New Mexico announced for 2027. That is still 431 restaurants covering a territory McDonald’s serves with more than 13,000. In-N-Out has one restaurant per 264,000 people inside its own footprint. McDonald’s has one per 25,000 nationally, a 10.5x difference in density.
Every operating failure lands on the owner
Company ownership cuts both ways. When In-N-Out closed its Oakland restaurant in 2024 citing crime at the site, no franchisee absorbed the write-off. The same applies to a bad real estate pick, a slow new market, or a shift in the cost of doing business in California, where the majority of the estate sits. The franchise business model transfers unit-level risk to third parties. In-N-Out kept all of it.
Throughput is the price of freshness
Burgers cooked to order, potatoes cut in store and no heat lamps produce the quality scores. They also produce the lines. In-N-Out is pushing 48% more daily volume than a McDonald’s through a kitchen with fewer shortcuts available, which is why its restaurants show up in customer complaints about wait times more often than the brand’s reputation would suggest. Adding a drive-thru lane does not fix a kitchen that refuses to hold product.
Nobody can check the numbers
Revenue estimates for In-N-Out run from $1.8 billion to $2.6 billion depending on the source. Unit counts run from 424 to 442. Associate counts run from 42,000 to more than 44,000. For any investor, supplier or landlord trying to price a relationship with the company, that spread is the operating reality.
Opportunities
Price headroom the company has chosen not to use
In-N-Out holds a burger price well below fast casual comparables and near quick service ones, while running the highest unit volumes in its category. Lynsi Snyder has said on the record that she argued against price increases in internal meetings out of obligation to customers. That is a stored option. A chain with 36% preference inside its footprint and a queue outside the building has room to move price and has repeatedly declined to take it.
The option has a cost. Every year the company holds price against a rising beef curve, it funds the difference out of its own margin, and margin is the only source of expansion capital it has.
The eastern build-out changes the cost base
Middle Tennessee starting pay is $17.50 an hour against $22 to $23 in California. New restaurants in Tennessee, Texas, Idaho and Washington carry lower labor and occupancy costs than the California core, so the mix shift itself improves system economics before a single new customer is counted.
The federal beef import window
On August 21, 2026, the White House said it would allow up to 300,000 metric tons of ground beef product to enter over three months without out-of-quota tariffs, with a stated commitment that the beef sells 25% below current market prices. Above-quota imports normally face a 26.4% tariff. Any large grinding buyer benefits from that supply, and In-N-Out is one of the largest single-brand grinding buyers on the West Coast.
Treat it as relief rather than a solution. The window is three months, the National Cattlemen’s Beef Association opposed it, and USDA does not expect herd rebuilding to shift prices before 2028.
Adjacent categories it has never touched
No breakfast, no chicken, no delivery, no loyalty program. Each is a revenue line competitors run and In-N-Out does not. The company has said no to all of them for reasons of consistency, which is defensible while beef is cheap and expensive to keep saying while beef is not.
Threats
The category stopped growing
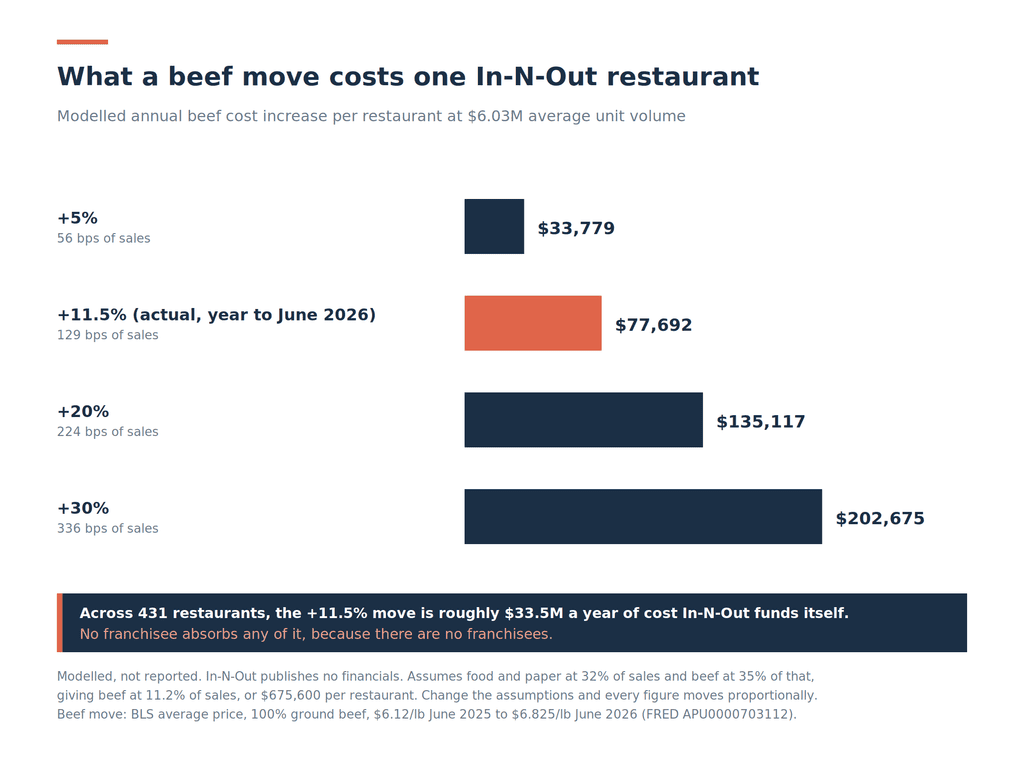
Technomic’s 2026 Top 500 report put total US chain restaurant sales at $451.5 billion in fiscal 2025, up 3.0%, below the 3.8% of menu price inflation that year. Burgers grew 1.5%. Chicken grew 5.3% and now takes more than 12% of chain restaurant sales against 7% in 2015. Coffee, chicken and beverage or snack concepts accounted for 83% of all new restaurant openings.
In-N-Out added 16 net restaurants in 2025, which is 3.86% unit growth and comfortably ahead of its own category. The threat is not that In-N-Out is losing the burger war. The threat is that consumers keep moving toward a protein it has never sold, at the moment the protein it does sell is the most expensive in decades.
Beef costs it cannot pass through fast enough
In-N-Out publishes nothing, so the exposure has to be modeled. At industry-typical assumptions of food and paper at 32% of sales and beef at 35% of that, beef runs about 11.2% of sales, or $675,600 a year for one restaurant.
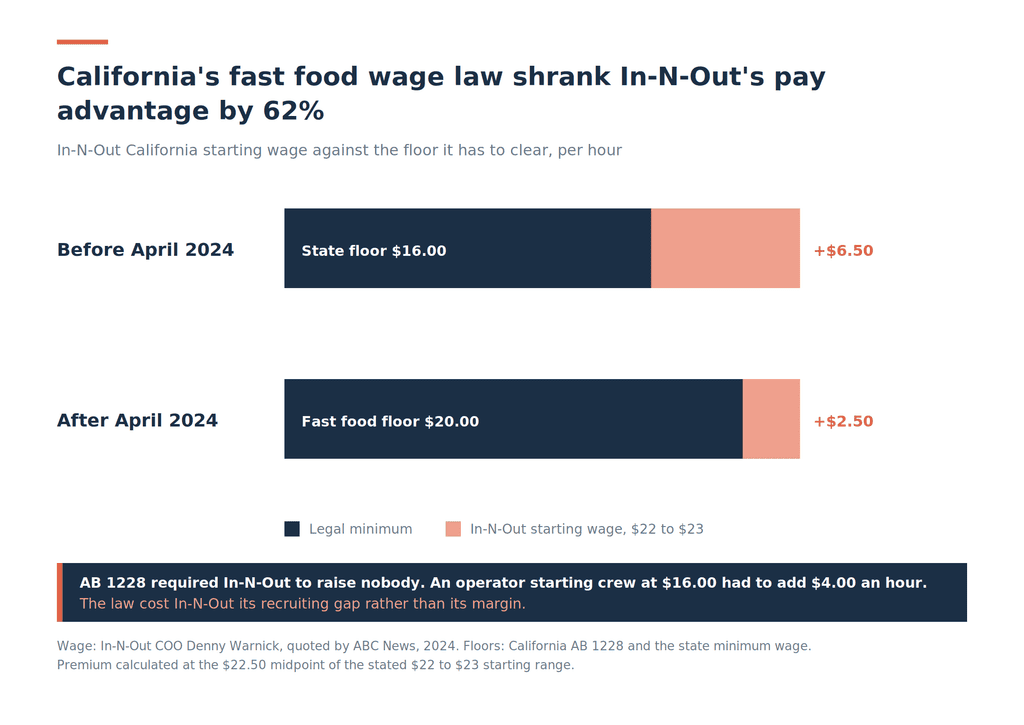
The 11.5% move in ground beef over the twelve months to June 2026 is worth about $77,700 per restaurant per year on that model, roughly 129 basis points of sales, or about $33.5 million across 431 restaurants. Change the assumptions and every number moves with them. What does not change is who pays. A franchised system spreads that cost across hundreds of independent balance sheets. In-N-Out funds it from one.
The wage floor has not finished moving
California’s Fast Food Council can raise the $20 floor once a year by the lesser of 3.5% or the change in CPI-W, and it has not yet done so. The chair resigned in June 2025 before a scheduled discussion, and the Economic Policy Institute calculates that inflation cut the real value of the $20 wage by 4.2% between April 2024 and January 2026. The council’s authority runs to January 1, 2029. Each future increase compresses In-N-Out’s remaining $2.50 premium further, and the company cannot respond by cutting pay without surrendering the labor advantage that supports its service scores.
Rivals closed the fresh beef gap
Fresh, never frozen beef was a differentiator when McDonald’s, Wendy’s and Whataburger all cooked frozen patties. That is no longer the industry standard it once was, and the brands In-N-Out competes with in Texas and the Southwest have their own quality reputations and much larger footprints. Whataburger added 76 restaurants in fiscal 2025 on a $3.914 million average unit volume. Culver’s added 44 at $4.040 million. Both play the fresh, regional, high-AUV game In-N-Out invented, in states In-N-Out is entering.
Owner concentration and the move east
Lynsi Snyder-Ellingson owns the company outright and plans to base herself in Tennessee, having said publicly that raising a family and doing business in California is not easy. Those comments drew boycott calls. A single-owner structure with no board of outside directors, no public filings and no succession disclosure concentrates strategy, brand voice and political exposure in one person. That has worked well for sixteen years. It is still a single point of failure that no governance mechanism sits behind.
The In-N-Out SWOT matrix
| Strengths | Weaknesses |
|---|---|
| 2.81 preference points per 100 restaurants, 2.7x Five Guys and 12.4x Burger King | Beef-only menu with no protein hedge and no frozen inventory buffer |
| $6.032M average unit volume, first in the US burger category | Expansion capped by patty plant range, not by demand |
| $22 to $23 California starting wage, above the legal floor | Every unit-level loss lands on the owner, with no franchisee to absorb it |
| Zero franchisees, so specification changes need no operator consent | 48% higher daily volume than McDonald’s through a slower kitchen |
| Pricing restraint that competitors could not match through AB 1228 | No audited figures; outside estimates disagree by up to 44% |
| Opportunities | Threats |
|---|---|
| Unused price headroom on a queue-limited product | Burger category grew 1.5% while chicken grew 5.3% |
| Lower-cost labor markets in Tennessee, Texas and the Southwest | Ground beef at $6.885/lb, herd smallest since 1951, no relief before 2028 |
| 300,000 tonne duty-free ground beef import window announced August 2026 | Fast Food Council can raise the $20 floor annually through 2029 |
| Breakfast, chicken, delivery and loyalty all untouched | Whataburger and Culver’s expanding on the same fresh, high-AUV playbook |
| New Mexico in 2027 and a built-out eastern supply spine | Sole owner with no board, no filings and no stated succession plan |
What the matrix says
Read across the quadrants and one strategy falls out. In-N-Out’s strengths are all denominated per restaurant, and its threats are all denominated per pound. The company wins on productivity and loses on inputs, so the answer is either more restaurants or more price.
More restaurants is slow by construction. The 300-mile rule ties unit growth to factory capacity, and factory capacity gets paid for out of retained earnings. At 3.86% unit growth the company adds roughly sixteen restaurants a year, which is real progress against a burger category that grew 1.5% and a Top 500 in which 48% of chains added nothing or shrank.
More price is fast, available and unused. In-N-Out sits on the largest untaken pricing option in American fast food: the highest per-restaurant brand preference in its category, priced near the value end of the menu board, in front of customers who queue. Every quarter the company declines to take it, it is buying loyalty with margin that would otherwise buy patty plants.
Both moves are available. Neither solves the chicken problem, and that is the item most competing analyses of In-N-Out miss while listing “limited menu” as a strength.
Frequently asked questions
Is In-N-Out’s limited menu a strength or a weakness? Both, and the beef cycle decides which one dominates. A short menu produces speed, low inventory complexity and the quality consistency the brand trades on. It also concentrates 100% of protein cost in the single most inflated commodity in US food service, with no cheaper item to promote.
Why does In-N-Out score lower than Burger King in national brand surveys? Coverage. YouGov surveys US adults nationally, and In-N-Out operates in ten states holding about a third of the population. Burger King and Five Guys compete for preference in all fifty. Per restaurant, In-N-Out converts about twelve times the preference Burger King does.
Did California’s $20 fast food wage hurt In-N-Out? Not on cost. In-N-Out already paid $22 to $23 to start, so AB 1228 required no raise. The damage was competitive: the law lifted rival wages toward In-N-Out’s level and cut the company’s pay premium over the applicable floor from $6.50 to $2.50 an hour.
How exposed is In-N-Out to beef prices? More than any large burger chain, because it buys fresh and cannot forward-buy frozen patties. On industry-typical cost assumptions, beef is around 11% of sales, so the 11.5% move in ground beef through June 2026 is worth roughly $77,700 per restaurant per year, or about $33.5 million across the system.
Will In-N-Out reach the East Coast? Not soon. Snyder-Ellingson said at a Pepperdine forum in April 2026 that she does not expect In-N-Out on the East Coast in her lifetime and will not compromise quality to expand. Tennessee is the eastern edge, with New Mexico added in 2027.
Why doesn’t In-N-Out franchise? Control of specification and control of capital. Franchising would fund faster growth and transfer unit-level risk, and it would also put menu, sourcing and remodel decisions into a negotiation with operators. The trade-off is the same one Chick-fil-A manages differently, as our Chick-fil-A business model breakdown shows.
What is the biggest single risk to In-N-Out in 2026? Input concentration meeting category migration. Beef is at record prices with no herd recovery expected before 2028, and the growth in chain restaurants has moved to chicken and beverages. In-N-Out has no product in either.
The Business Model Analyst Take
Most SWOT write-ups of In-N-Out list the same strengths the company lists about itself: quality, loyalty, employee pay, no franchising. All true, all downstream of one decision that also produces every threat on the list.
The interesting number in this analysis is not the average unit volume. It is 2.81 preference points per 100 restaurants against Burger King’s 0.23. In-N-Out has built the most efficient brand in American fast food and then chosen, deliberately and repeatedly, not to convert it. It converts it into neither price nor units at the rate the brand would support, because the supply rule caps units and the founder’s promise caps price.
That is a coherent position while beef behaves. With the national herd at a 1951 low and ground beef at $6.885 a pound, the company is now absorbing a cost shock through the one channel it has left, which is its own margin, and margin is what pays for the next patty plant. Watch for a price move. If In-N-Out starts using its pricing power in 2027, the constraint stopped being philosophical.