
In-N-Out never franchised, never borrowed against its brand, and never opened a restaurant it did not pay for. That looks like stubbornness. Read the numbers and it is closer to a manufacturing strategy with a burger stand attached.
The In-N-Out business model is a fully vertically integrated, entirely company-owned quick-service restaurant model. In-N-Out buys and grinds its own beef, runs its own patty plants and distribution centres, owns and operates every one of its restaurants, and sells no franchises. Every dollar of systemwide sales lands on its own revenue line, and every dollar of expansion capital comes out of its own retained earnings. Its addressable market is capped by a self-imposed rule that no restaurant may sit more than 300 miles from one of its patty-making facilities.
In-N-Out at a glance
| Metric | Figure |
|---|---|
| Founded | 1948, Baldwin Park, California |
| Owner | Lynsi Snyder-Ellingson, sole owner since 2017 |
| US restaurants (year-end 2025) | 431 |
| Franchised restaurants | 0 |
| Net new restaurants, 2025 | 16 |
| US systemwide sales, 2025 | approximately $2.6 billion (QSR estimate) |
| Average sales per restaurant, 2025 | $6.03 million |
| Rank in US burger category by sales | 9th |
| Rank in US burger category by sales per restaurant | 1st |
| Associates | more than 44,000 |
| States served | 10 |
| Supply chain rule | every restaurant within 300 miles of a patty plant |
What In-N-Out actually sells
Most quick-service brands are two businesses stapled together. There is a restaurant business, which buys food, hires people and sells meals at a thin margin. And there is a licensing business, which rents out a trademark and an operating manual to independent owners and collects a percentage of their sales. McDonald’s is overwhelmingly the second thing: 13,062 of its 13,706 US restaurants belong to somebody else. Burger King, Wendy’s, Sonic and Dairy Queen are all built the same way. The franchise business model exists precisely because it lets a brand grow on other people’s money.
In-N-Out has none of that. There is no licensing business, no royalty stream, no advertising fund, no franchisee balance sheet standing between the brand and the cost of a bad quarter. What there is instead is a food manufacturing and logistics operation: company butchers, company patty plants, company refrigerated trucks, company distribution centres, and 431 retail outlets at the end of the line that happen to be the only customers the factory has.
That is the frame worth holding onto. In-N-Out is not a restaurant chain that stubbornly refuses to franchise. It is a vertically integrated food business whose stores are the last step in its own supply chain, and almost every strange thing about the company follows from that.
The short menu is not minimalism as an aesthetic. It is what happens when you have to physically move every ingredient yourself. The refusal to enter Florida is not brand mystique. It is a warehouse problem. And the pace of growth, roughly a dozen and a half restaurants a year, is not caution. It is the maximum rate at which a self-financed factory can add distribution.
The 300-mile rule: geography as a business model
In-N-Out does not use frozen beef, and it does not use freezers, heat lamps or microwaves in its restaurants. Fries are cut from whole potatoes on site. Everything else arrives by company truck.
Sustaining that requires the restaurants to sit close to the plants. The company has stated the rule in public: it will consider opening stores further east only once it has a patty-making facility within 300 miles of any new restaurant. Earlier accounts of the policy cited a wider radius of 500 miles or “about a day’s drive,” and the practical limit has clearly flexed over the years, but the shape of the constraint has never changed. Product freshness is defended with a compass, not a marketing budget.
Run the geometry and the consequences are stark.
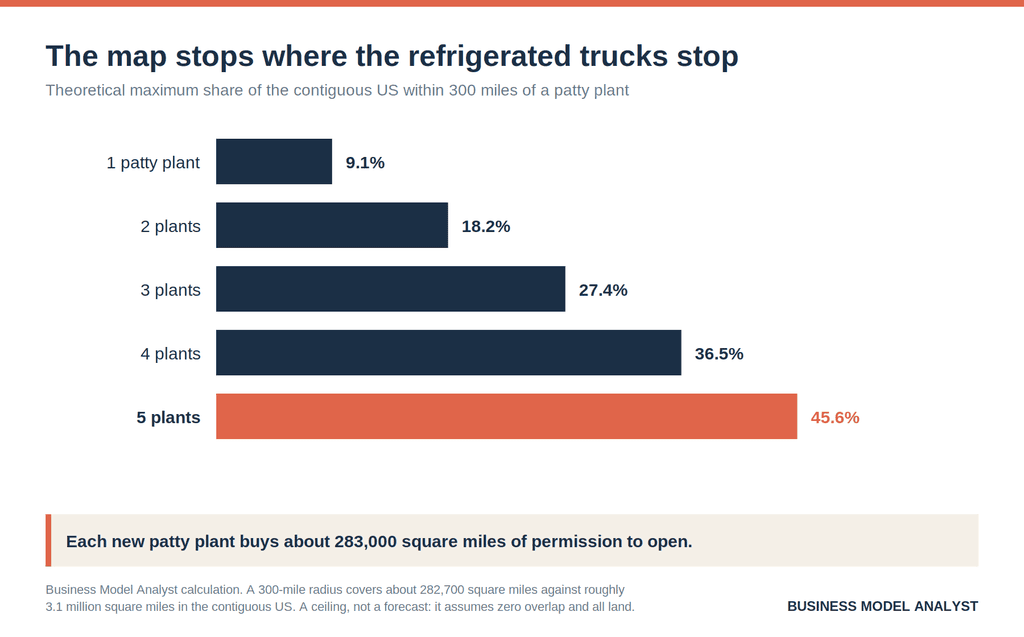
A circle with a 300-mile radius covers roughly 282,700 square miles. The contiguous United States runs to about 3.1 million. So a single patty plant licenses In-N-Out to operate across, at absolute best, 9.1% of the lower 48. Five plants get to 45.6%, and only in a fantasy version where the circles never overlap, never fall on water, and never sit over empty desert. In the real world In-N-Out’s plants cluster in California, with additional facilities in Texas and Colorado and now Middle Tennessee, and the overlap is substantial by design because density is what makes the truck routes economic.
This is the single most underrated fact about the company. In-N-Out’s total addressable market is not a function of how many Americans want its burgers. It is a function of how many warehouses it has built. Demand is effectively infinite and irrelevant. The binding constraint is refrigerated logistics, and the company has to buy that constraint away one facility at a time.
Snyder-Ellingson has been blunt about where that leaves the eastern seaboard. She told a Pepperdine audience in April 2026 that she does not see In-N-Out on the East Coast in her lifetime, and has said repeatedly that Florida has asked and the answer is still no. Those are not brand-management decisions dressed up as logistics. They are logistics decisions that read, from the outside, like brand management, which is a very pleasant accident.
Why $6.03 million per restaurant is the load-bearing number
Every part of this model is expensive. Owning the plants is expensive. Owning the trucks is expensive. Owning every restaurant means carrying every restaurant’s rent, labour and food cost on your own income statement with nobody to share the risk. A company structured this way needs its individual restaurants to work extraordinarily hard, and In-N-Out’s do.
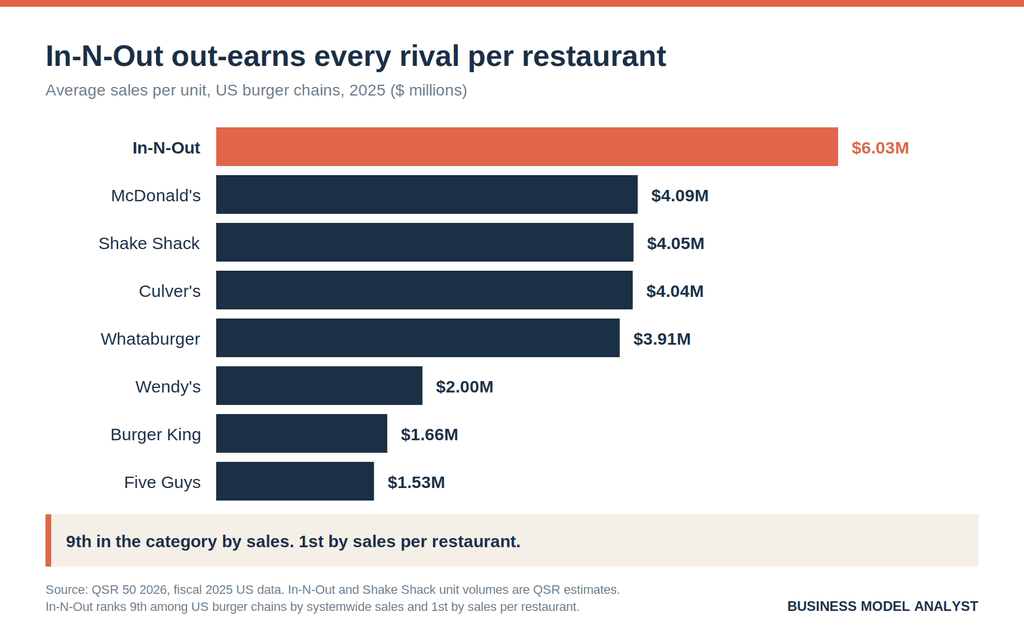
In-N-Out finished 2025 at $6.03 million of sales per restaurant. McDonald’s, the largest restaurant business on earth, managed $4.09 million. Burger King managed $1.66 million. In-N-Out is ninth in the US burger category by total sales and first, by a wide margin, by sales per building. Across the whole QSR 50 only Chick-fil-A and Raising Cane’s run higher unit volumes.
Here is the arithmetic nobody seems to run. In-N-Out’s roughly $2.6 billion of systemwide sales, produced at McDonald’s average unit volume, would require 636 restaurants. In-N-Out does it with 431. The productivity advantage saves it 205 buildings, or 32% of the real estate a McDonald’s-efficiency operator would need to reach the same revenue. For a company that pays for every building itself, that is not a vanity statistic. It is the reason the model is solvent at all.
Volume also explains one of the most-repeated facts about the company, which is how well it pays. In-N-Out has said its store managers earn around $160,000, and the number gets quoted as evidence of unusual generosity. Some of it is. But $160,000 is 2.65% of a $6.03 million restaurant. Apply that same share of sales to a restaurant running McDonald’s average volume and the manager earns $108,400. The volume advantage alone funds a $51,600 pay gap without moving a single line of the cost structure as a percentage of sales. Paying well and running high volumes are not two separate virtues here. They are the same fact seen from two ends.
No franchisees means no franchise capital
The trade In-N-Out makes is visible the moment you compare revenue capture.
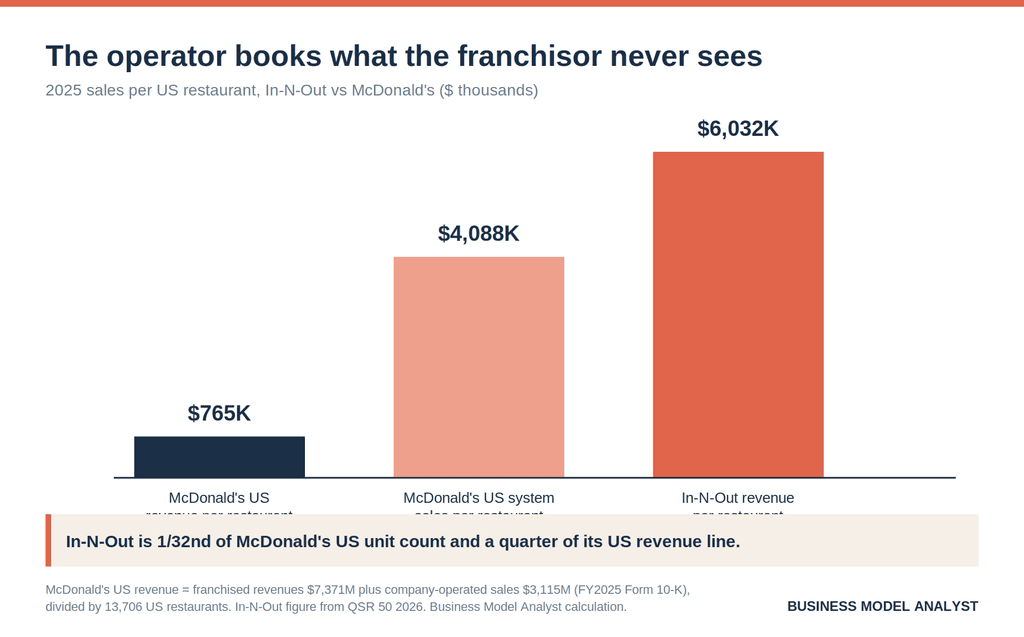
McDonald’s US system generated $55.1 billion of sales in 2025. McDonald’s the company booked $10.5 billion of that as revenue, being $7.4 billion of franchised revenues plus $3.1 billion of company-operated sales. The other 81% belongs to franchisees. Divide the company’s own figure by 13,706 US restaurants and McDonald’s collects $765,000 per US restaurant per year.
In-N-Out collects $6.03 million per restaurant, because the systemwide number and the revenue number are the same number. On a unit base one thirty-second the size, In-N-Out’s US revenue line is roughly a quarter of McDonald’s US revenue line, and it books 7.9 times as much revenue per restaurant.
Now the honest half. Revenue is not profit, and McDonald’s converts its smaller revenue at a margin no operator can touch: its US franchised business runs an 82.5% margin against 11.6% for the restaurants it operates itself, a gap we broke down in our analysis of McDonald’s Q2 2026 guest counts and landlord margin. McDonald’s chose to be a landlord and a royalty collector. In-N-Out chose to be an operator, which means it keeps all of the revenue and all of the cost.
What it gives up is somebody else’s chequebook. Franchising is, before anything else, a financing structure. A franchisor enters a new state on franchisee capital, books a franchise fee on day one, and never puts a dollar of its own into the dirt. In-N-Out funds every building, every fryer, every truck and every warehouse out of its own cash flow, and Lynsi Snyder-Ellingson owns 100% of the equity, so there is no outside investor to call for more.
That is what sets the growth rate. In-N-Out added 16 net restaurants in 2025, or 3.9% unit growth, which is actually more than triple McDonald’s 1.1% US unit growth that year. But 3.9% of a small number is a small number. Since Snyder-Ellingson took over as president in 2010 the chain has gone from roughly 230 restaurants to 431, a compound rate of about 4.3% a year. That figure is not a target the company chose. It is roughly what a $2.6 billion self-funded business can afford while also building factories.
The Tennessee test: what a market costs when nobody else pays
Middle Tennessee is the cleanest look anyone has ever had at the true cost of an In-N-Out market entry, because the state published the numbers.
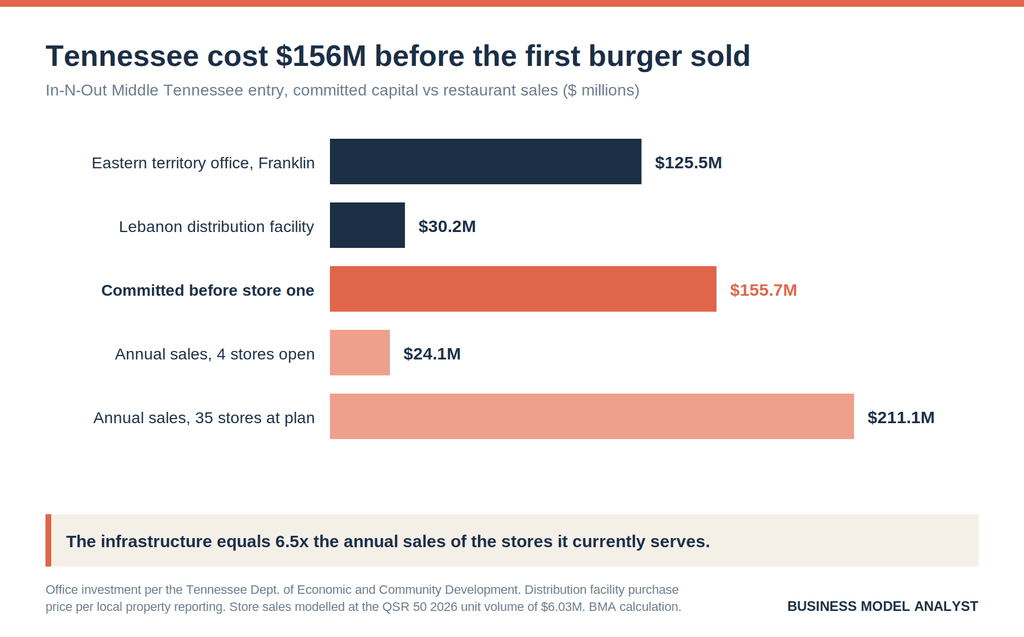
The eastern territory office under construction in Franklin, south of Nashville, is a $125.5 million, 100,000-square-foot investment tied to 277 jobs, per the Tennessee Department of Economic and Community Development. To satisfy the 300-mile rule the company also acquired a distribution facility in Lebanon, reported locally at $30.15 million. Call it $155.7 million of fixed infrastructure committed before a single Tennessee burger was sold.
In-N-Out opened its first three Tennessee restaurants at the end of 2025, with Franklin following. At the chain’s own average unit volume, four restaurants generate about $24.1 million a year. The infrastructure is therefore running at roughly 6.5 times the annual sales of the stores it currently serves. Snyder-Ellingson has floated as many as 35 Tennessee restaurants; at full build that is around $211 million of annual sales, meaning the entry cost still equals about three quarters of one year of the completed market’s revenue.
No franchisor on earth spends like that to enter a state. A franchisor signs a development agreement, collects fees and lets an operator carry the risk, which is the logic we traced in Burger King’s refranchising economics. In-N-Out builds the factory first and hopes the customers show up second. So far they always have, but the sequencing is the point: this company pays for demand in advance.
The same restructuring is reshaping the corporate side. In-N-Out is closing its Irvine office by the end of 2029 and consolidating its western headquarters back into Baldwin Park, less than a mile from the original 1948 stand, while roughly 500 Irvine corporate staff choose between California and Tennessee. Snyder-Ellingson has said she and her family will be based in Franklin. A company with one owner can relocate its own centre of gravity without asking anybody, and it has.
How the model makes money
| Layer | What it does | Who captures it |
|---|---|---|
| Beef procurement and butchery | Buys whole chuck, inspects, grinds in-house | In-N-Out |
| Patty manufacturing | Company plants, no frozen product | In-N-Out |
| Distribution | Company refrigerated fleet, near-daily delivery | In-N-Out |
| Restaurant operations | 431 company-operated stores, zero franchised | In-N-Out |
| Real estate | Predominantly company-controlled sites | In-N-Out |
| Royalties and franchise fees | None. No franchisees exist | Not applicable |
| Growth capital | Retained earnings only, no outside equity | In-N-Out |
The revenue model is the simplest in large-scale quick service: sell burgers, keep everything. The margin model is the hard part, and it rests on four levers. A menu narrow enough that the supply chain stays cheap to run. Unit volumes high enough to absorb full operating cost without a royalty cushion. Marketing spend low enough to be almost invisible, because scarcity and word of mouth do the work advertising does elsewhere. And a real estate footprint small enough that self-funding it remains possible.
Remove any one of the four and the model stops working. That is not fragility exactly, but it is tight coupling, and tightly coupled systems fail in correlated ways.
What could break it
Beef. In-N-Out has no supplier diversification to fall back on and no frozen inventory to buffer a price spike. Every burger chain has felt beef inflation, and Burger King’s franchisee profitability fell in 2025 largely because of it. A chain that buys fresh, daily, at scale, with a single-protein menu and a reputation for not raising prices aggressively, carries that exposure with less cover than most.
The 300-mile rule is a ratchet. Each new region requires a plant before it requires customers. The Tennessee numbers show the bill. If a new market underperforms, In-N-Out cannot refranchise its way out, cannot sell the units to an operator, and cannot stop owning the warehouse.
Culture does not travel by truck. The company’s own answer to how it maintains standards is tenure: managers who have been inside the system for a decade or two. A 35-restaurant Tennessee build, plus Washington, Idaho, New Mexico and whatever follows, requires manufacturing that tenure faster than the model historically has. The Franklin office is an attempt to solve exactly this, and it is unproven.
Single-owner concentration. One person owns the entire company and has no obligation to any outside capital. That is the source of the model’s discipline and also its largest key-person risk. There is no public succession framework, no board answerable to shareholders, and no market price for the equity.
The competition finally caught up on quality. In-N-Out’s original edge was fresh beef in a frozen-beef industry. McDonald’s moved its quarter-pound patties to fresh years ago. Whataburger, Culver’s and Shake Shack all run unit volumes near $4 million with better-quality positioning than the 1990s burger category offered. The scarcity premium is real but it is not permanent.
What the model adds up to
In-N-Out is often described as a company that sacrifices growth for quality. That framing is too flattering and too vague. What it actually did was choose a cost structure in which quality is cheap and growth is expensive, and then optimise ruthlessly inside that choice.
Quality is cheap for In-N-Out because the menu is short, the supply chain is owned, the inventory turns almost daily and the volume per store is so high that fixed costs disappear into it. Growth is expensive because every restaurant, every truck and every plant is bought with money the company already earned. The result is a business that is far more profitable per unit than its scale suggests and permanently smaller than its brand equity would allow.
Ask whether In-N-Out could be everywhere and the answer is yes, in the sense that the demand exists. Ask whether the In-N-Out that got everywhere would still be In-N-Out and the answer is no, because getting everywhere means franchising, and franchising means selling the operating model to people who did not build it. Two of the most valuable brands in American quick service, In-N-Out and Chick-fil-A, both refuse to sell equity in their restaurants. That is not a coincidence.
FAQ
Does In-N-Out franchise? No. In-N-Out has never sold a franchise and has said publicly it has no plans to franchise or go public. All 431 restaurants are company-operated, making it the only chain in the top 14 US burger brands with zero franchised units.
How much does an In-N-Out restaurant make? About $6.03 million a year, per QSR’s 2026 ranking of fiscal 2025 data. That is the highest average unit volume of any US burger chain and roughly 47% above McDonald’s.
Who owns In-N-Out? Lynsi Snyder-Ellingson, granddaughter of founders Harry and Esther Snyder. She became president in 2010 and gained full ownership in 2017, at age 35, after the deaths of her uncle Rich, her father Guy, and her grandmother Esther.
Why won’t In-N-Out expand to the East Coast? Because it will not open a restaurant more than 300 miles from one of its own patty-making facilities, and it has not built one on the East Coast. Snyder-Ellingson said in 2026 she does not expect East Coast locations in her lifetime.
How much revenue does In-N-Out generate? No audited figure exists, since the company is private and files nothing. QSR estimated $2.6 billion of US systemwide sales for 2025. Technomic estimated roughly $2.1 billion for 2024. Commercial databases still list figures near $1.8 billion. Treat any single number as an estimate.
Why is In-N-Out’s menu so small? Because it has to move every ingredient itself. A narrow menu keeps the SKU count low enough that company-owned manufacturing and daily refrigerated distribution stay economically viable. The menu is a downstream consequence of the supply chain, not a separate branding decision.
Is In-N-Out more profitable than McDonald’s? Per restaurant, In-N-Out generates almost eight times the revenue McDonald’s books per US restaurant, but McDonald’s converts its revenue at a far higher margin because it is mostly a franchisor and landlord. As a total business McDonald’s is vastly larger and more profitable. In-N-Out is the more productive operator; McDonald’s is the better-designed financial machine.
The Business Model Analyst Take
The interesting question about In-N-Out is not why it stayed small. It is why staying small turned out to be so profitable.
The conventional wisdom in quick service since the 1950s has been that unit growth is the only growth worth having, and that franchising is the cheapest way to buy it. That wisdom is correct for almost everybody. It is why McDonald’s has 13,706 US restaurants and why its business model is really a real estate and licensing model in a burger costume. In-N-Out ran the opposite experiment for 78 years and produced the most productive burger restaurants in the country.
What makes it work is not the burgers. It is that the company solved the same problem franchising solves, the problem of who pays for the next restaurant, with a different answer: it made each restaurant so productive that it could afford to pay for the next one itself. That answer generates far fewer restaurants and far more control per restaurant. It is a legitimate strategy, not a moral one, and it only works at very high unit volumes.
The thing to watch now is Tennessee. Every previous In-N-Out expansion moved into territory adjacent to the existing supply base, into markets that already knew the brand from a neighbouring state. Middle Tennessee is the first genuine leap, backed by $156 million of infrastructure spent ahead of revenue, and it is the test of whether the model travels or whether it was always partly a California phenomenon that happened to be portable as far as Texas. If the Tennessee restaurants hit the chain’s normal volumes, the 300-mile rule stops being a ceiling and starts being a franchise-free playbook for national expansion, one warehouse at a time. If they do not, In-N-Out has just discovered the boundary of its own model, and it paid $156 million to find it.