
Investors spent Wednesday asking why Ted Decker stepped back. The filing that explains how Home Depot runs without him went out on July 30, and the market read it as an HR memo.
Home Depot never had to say why its CEO is on leave, and it had strong legal reasons not to. What it did have to disclose, it disclosed inside 24 hours: Ann-Marie Campbell takes day-to-day operations, CFO Richard McPhail takes finance plus the Pro subsidiaries and becomes the company’s principal executive officer for SEC purposes, and lead director Greg Brenneman chairs the board. That split is not an emergency arrangement. It is the org chart Home Depot published on July 30 with one name removed.
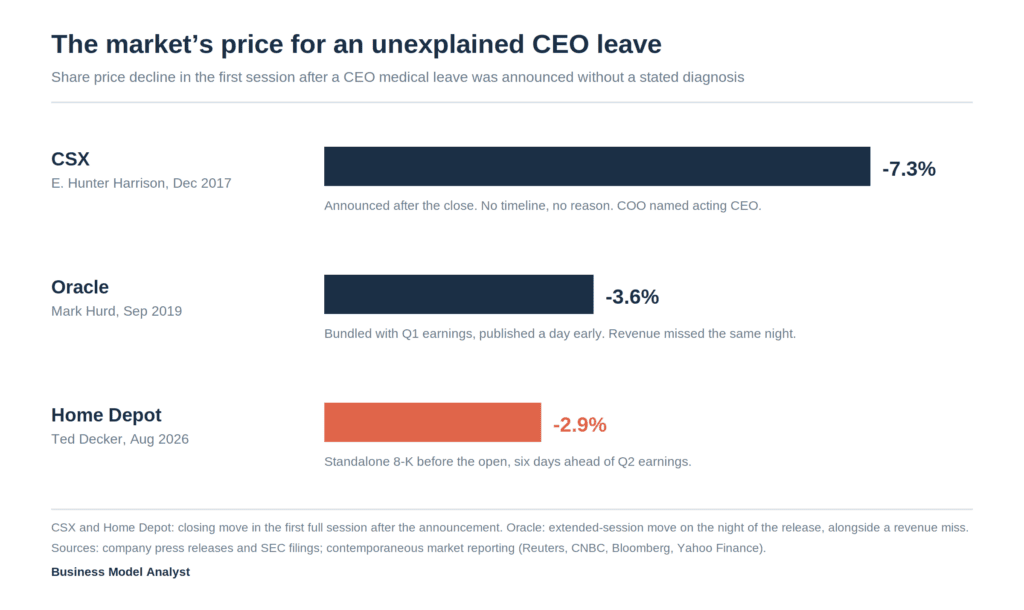
Ted Decker is 63, has worked at Home Depot since 2000, and has run it since 2022. On Tuesday, August 11, the board agreed he would step away for a temporary medical leave. At 9:06 the next morning, before the opening bell, the company’s general counsel signed and filed the 8-K. Shares closed at $344.19, down about 2.9%, which on roughly 996 million shares takes about $10 billion off the company in a single session.
Nothing in that filing said anything about the business. No guidance change, no comp revision, no write-down. The market repriced $10 billion on the absence of a sentence.
Corporate governance expert Charles Elson, quoted in the WSJ’s CEO Brief on Thursday, argued that a large-cap CEO surrenders the expectation of privacy and that silence hands the story to the rumor mill. He is describing a real cost. He is also describing the cheaper of the two options available to Home Depot’s board.
What Happened
The 8-K carried three items: 5.02 for the officer change, 7.01 for the Reg FD release, 9.01 for the exhibit. Item 5.02 gives a company four business days to file. Home Depot used less than one.
The substance sits in four decisions.
Campbell, 61, oversees day-to-day operations. She joined Home Depot in 1985 as a cashier, ran the Southern Division, then US Stores, then US Stores and International, and has been senior executive vice president since November 2023.
McPhail, 56, oversees financial management and the Pro subsidiaries. He joined in 2005 and has been CFO since September 2019. The filing also names him, in language nobody picked up, as “designated as interim principal executive officer” for purposes of SEC rules. He now signs as both PEO and principal financial officer.
Brenneman chairs the board in his capacity as independent lead director.
Neither Campbell nor McPhail received a raise. The 8-K states that no compensation changes were made in connection with the added responsibilities. For context, Decker’s fiscal 2025 total compensation came to $16.19 million on a $1.4 million salary. The board handed his job to two people and paid nothing for it.
One more line matters. The board acted in alignment with Decker’s own recommendation. He picked his caretakers.
The Backstory
On July 30, Home Depot issued a release most of the trade press filed under “reorg.” Read it again with Wednesday in mind.
Billy Bastek absorbed private brands into core merchandising. Jordan Broggi took a combined interconnected group covering customer experience, online, financial services and loyalty. Fran Bell, who joined as chief technology officer in March, picked up the store, supply chain and Pro product technology teams. And the Office of Integration was renamed the Office of Pro Acceleration and handed to McPhail, with a mandate covering Home Depot Pro, HD Supply, SRS and Construction Resources, plus a shared CRM, a shared catalog and shared fulfillment.
Thirteen days later, McPhail’s interim mandate reads: financial management and the Pro subsidiaries. That is the July 30 portfolio, word for word. Campbell’s interim mandate reads: day-to-day operations. That is the job she has held since 2023.
Home Depot did not invent a continuity structure on August 11. It executed one it had already announced, in public, under Decker’s own byline. Anyone who read the July 30 release as a strategy document rather than a personnel notice already knew who would run each half of the company.
The Plan
US securities law contains no rule requiring a company to disclose a CEO’s diagnosis. The trigger is incapacity, not illness. Absent that, the board runs a materiality judgment under the standard framework, and courts have never held that a CEO’s health was so material it should have been disclosed. Fenwick’s practitioners describe an unwritten gloss on materiality that pushes health information out of the category, partly because prognoses are unknowable and partly because judges dislike ruling that a person’s medical file belongs to shareholders.
The asymmetry that decides these cases sits in the half-truth doctrine, codified in SEC Rules 408 and 12b-20 and read into Rule 10b-5. A company that stays silent owes nothing. A company that speaks owes completeness, and if it promises updates, it owes those too.
Price the two paths. Silence costs one bad session, and Home Depot just paid it: about 2.9%, roughly $10 billion, recoverable on any decent Q2 print. Disclosure costs an open-ended duty running the length of an illness whose course the treating physicians cannot forecast, plus litigation exposure on every subsequent statement, plus the near-certainty that a serious diagnosis produces a larger drop than the vague one did.
Home Depot took the cheap side and moved fast on everything that was actually the company’s to give. Look at how the release hedges the one optimistic line. The company classified the duration of the leave and the timing of Decker’s return as forward-looking statements, subject to substantial risk, cross-referenced to the management transition risk factors in its 10-K. The most quoted sentence in the announcement is the one Home Depot’s lawyers disclaimed.
Compare Oracle in September 2019. It pulled its Q1 earnings release forward by a day so Mark Hurd’s leave and the numbers landed together, and got a 3.6% after-hours drop nobody could attribute cleanly to either. Home Depot separated them by six days. Q2 prints on Tuesday, August 18, against consensus of $4.73 in EPS on $47.35 billion. Those numbers now trade on their own merits.
The Business Model Angle
The interesting thing about the interim split is where the seam runs.
Campbell got 2,361 stores and more than 470,000 associates. That business turned in comparable sales of 0.6% last quarter, with transactions down 1.3% and average ticket up 2.3% to $92.76. It is a mature retail operating system that runs on process, and it throws off cash.
McPhail got the other company. Home Depot paid $18.25 billion for SRS Distribution in 2024, the largest acquisition in its history, then bought GMS through SRS for an enterprise value of about $5.5 billion, closing in September 2025. Add HD Supply, Construction Resources and the 1,280-plus SRS branches, and roughly $24 billion of acquired distribution now sits under the CFO alongside the balance sheet that financed it.
Between those two halves sits the job the board gave to nobody: deciding how much of the store business’s cash flow goes into the distribution roll-up, and at what pace. That is capital allocation, and it is the part of the CEO role that cannot be handed to an operator or an accountant without changing the answer.
Two readings follow. The generous one says the board expects Decker back soon enough that no capital decisions of consequence come due, so parking the allocator’s chair costs nothing. The harder one says Home Depot’s chief executive function has already been split by the acquisitions themselves, and the company has been running as a retailer bolted to a distributor for two years without admitting the org chart implication. July 30 admitted it. August 12 tested it.
The zero-dollar compensation decision points to the first reading. Boards that expect a long absence pay interim stipends, because unpriced authority creates ambiguity about who is in charge. Paying nothing declares the arrangement temporary and, usefully, avoids signaling that a job opening exists.
The Risk
Start with the base rate, because it is grim and short. CSX announced Hunter Harrison’s medical leave after the close on December 14, 2017, naming an acting CEO and giving no reason and no timeline. Shares fell 7.3% the next session, wiping out roughly $4 billion. Harrison died on December 16. Oracle said Hurd needed time for health reasons on September 11, 2019. He died on October 18. Two of the three most-cited comparable disclosures ended within weeks in the CEO’s death. The market’s discount on Wednesday was not superstition.
That is the strongest version of Elson’s argument, and it deserves stating plainly: the reason boards choose silence is the same reason investors distrust it. Nothing here is a claim about Decker’s condition, which is unknown and none of the public’s business.
Second, governance. The board ratified a continuity structure the CEO recommended, built on an org map the same CEO published two weeks earlier. If the leave extends or becomes permanent, the directors inherit a succession architecture designed by the outgoing executive rather than one they stress-tested independently. Brenneman’s statement praises Campbell and McPhail and says nothing about a search.
Third, the print. McPhail runs Tuesday’s call as CFO and as interim principal executive officer, with two open questions on the table. Decker told analysts in May that second-half improvement would come from storm activity normalizing rather than any consumer recovery, which set a specific bar. And McPhail flagged filed tariff refunds the company expects to offset input costs, saying at the time that Home Depot had “received an immaterial amount to date.” Whether that cash lands in Q2 swings margin optics, and the person answering for it is now also the person the SEC treats as chief executive.
Fourth, tempo. Dual leadership works for continuity and drags on decisions. Home Depot is mid-integration on two large acquisitions, and integration is where somebody has to break ties between merchandising and distribution. Campbell and McPhail have worked together for over 20 years, which helps. Neither outranks the other, which does not.
Quick Questions
Was Home Depot required to say why Decker is on leave? No. Disclosure obligations attach to the leadership change and to incapacity, not to a diagnosis. The company met the first and made no representation about the second.
Who is legally in charge? McPhail, as interim principal executive officer for SEC purposes. Operationally, Campbell runs the stores. Brenneman chairs the board.
Did anyone get promoted or paid more? Neither. The 8-K says compensation is unchanged. No interim CEO title was created either; Home Depot used the phrase “office of the CEO,” which keeps the seat notional.
Is Campbell the heir apparent? The company has said nothing to that effect. She has 41 years at Home Depot and now holds the operating half. Read the earnings call for whether she or McPhail leads it.
Why did the stock fall if operations did not change? Investors priced a widened distribution of outcomes: a short leave, a long one, or a permanent one. Home Depot gave them the first as an expectation and disclaimed it as forward-looking in the same document.
What should I watch on August 18? Whether the interim pair reaffirms the fiscal 2026 guide of flat to 2% comps and flat to 4% EPS growth, whether the tariff refund shows up, and whether either of them offers a new detail on Decker’s return.
The Business Model Analyst Take
The WSJ framed this as an ethics question about what investors deserve. The better question is what a chief executive’s job consists of, because that determines what a company can meaningfully disclose when the chief executive stops doing it.
A diagnosis tells you almost nothing operational. It gives you a probability distribution over a return date, filtered through a board that is not qualified to read a chart and lawyers who will not let it try. A decision-rights map tells you who signs what, who breaks ties, and which strategic bets keep moving. Home Depot published the second on July 30 and has been treated all week as though it published nothing.
For any founder with a business large enough that someone else could run it: the disclosure that protects your company during your absence is the one you write while you are healthy. Not the letter you release from the hospital. The org chart, with names against decisions, published in advance and boring enough that nobody reads it as a crisis document. Home Depot did that by accident or by design, and either way it is the reason Wednesday cost 2.9% instead of 7.3%.
The part that should bother shareholders is not the missing sentence about Decker’s health. It is the missing name against capital allocation. Two executives are minding the halves. Nobody was assigned the job of deciding how much of the retailer funds the distributor, which is the only decision at Home Depot right now that compounds.