
Hilton Worldwide Holdings closed 2025 as one of the most profitable operators in global hospitality, but the headline “record year” hides a more useful story for founders and operators. Unit growth was exceptional. Same-store demand was flat. This SWOT analysis separates the two so you can see where Hilton’s asset-light model is genuinely compounding and where it is exposed.
What is Hilton? Hilton (NYSE: HLT) is a leading global hospitality company that franchises, manages, and licenses hotels rather than owning most of them. As of year-end 2025 its portfolio spanned 28 brands, more than 9,200 properties, and over 1.3 million rooms across 144 countries and territories, ranging from midscale (Hampton, Spark) to ultra-luxury (Waldorf Astoria, Conrad, LXR). The company generates the bulk of its profit from management and franchise fees, making it a capital-light fee engine rather than a real-estate owner.
Hilton Company Overview
Hilton runs an asset-light model: it collects fees from owners and franchisees who carry the property risk, while Hilton supplies the brands, the reservation system, and the Hilton Honors loyalty program. That design produces high-margin, resilient cash flow that funds aggressive shareholder returns.
| Metric (FY2025) | Figure | Note |
|---|---|---|
| Revenue | $12.04 billion | Up roughly 7.7% year over year |
| Net income | $1.46 billion | Marginally below 2024 despite record revenue |
| Adjusted EBITDA | $3.73 billion | Company record |
| Diluted EPS (adjusted) | $8.11 | Versus $7.12 in 2024 |
| Net unit growth | 6.7% | Roughly 100,000 rooms added |
| Development pipeline | 520,500 rooms | Record; up about 4% year over year |
| Capital returned | $3.3 billion | Dividends plus buybacks |
| System-wide RevPAR | +0.4% | Versus original guidance of 2% to 3% |
The 2026 outlook is stronger on the bottom line: management guides to net income of roughly $1.98 billion to $2.01 billion, Adjusted EBITDA of $4.0 billion to $4.04 billion, capital return near $3.5 billion, and net unit growth of 6% to 7%, with RevPAR expected up 1% to 2%.
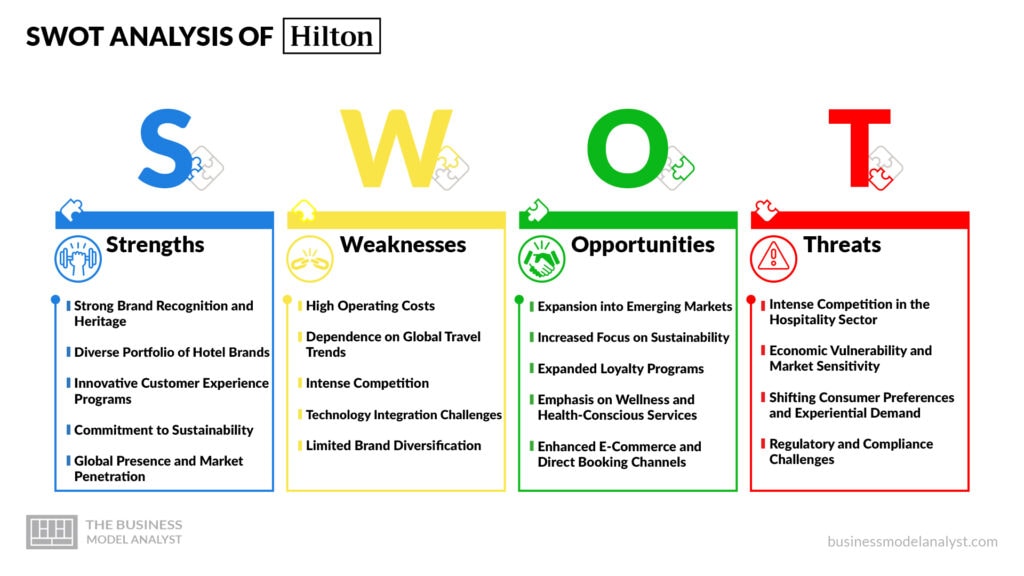
Hilton SWOT Analysis
| Strengths | Weaknesses |
|---|---|
| Asset-light, high-margin fee model | RevPAR growth stalled at 0.4% in 2025 |
| Record 520,500-room pipeline and 6.7% net unit growth | Net income slipped despite record revenue |
| 28-brand portfolio spanning every price tier | Limited direct control over guest experience |
| Hilton Honors: 235 million members, fastest-growing major program | Loyalty currency valued below Marriott’s |
| Powerful commercial and reservation engine | Heavy reliance on US demand and a leveraged balance sheet |
| Opportunities | Threats |
|---|---|
| Doubling lifestyle to about 700 hotels by 2028 | Marriott’s larger scale and brand breadth |
| Midscale and extended-stay whitespace | Short-term rentals (Airbnb) eroding leisure and long stays |
| Luxury expansion at three openings per week | Soft US government and international inbound demand |
| Branded residences and experiential loyalty | China slowdown and FX headwinds |
| Asia-Pacific, Middle East, and all-inclusive growth | OTA intermediation and franchisee cost pressure |
Strengths of Hilton
1. An asset-light fee engine that prints cash. Hilton does not tie up capital owning buildings. It earns management and franchise fees while owners absorb construction and operating risk. Management and franchise fee revenue grew 6.4% in 2025 even as same-store demand went flat, which is the whole point of the model: fee income scales with room count, not just with nightly demand.
2. Industry-leading unit growth and pipeline. Hilton posted 6.7% net unit growth and ended 2025 with a record 520,500 rooms in its development pipeline. It started construction on roughly 100,000 rooms in a single year, and by the company’s own account, about one in five hotel rooms under construction worldwide is slated to fly a Hilton flag. That is a multi-year, contractually locked growth runway that competitors cannot quickly replicate.
3. A 28-brand portfolio covering every price point. From Spark and Hampton at the value end to Waldorf Astoria, Conrad, and LXR at the top, Hilton can place a relevant brand in almost any market. In 2025 its luxury and lifestyle portfolio crossed 1,000 hotels, and the company added two new brands, Apartment Collection by Hilton and Outset Collection by Hilton, to attack extended-stay and collection whitespace.
4. Hilton Honors as a demand flywheel. Hilton Honors reached roughly 235 million members and has been the fastest-growing major hotel loyalty program, expanding its base by about 247% since 2018. On current trajectory it is positioned to overtake Marriott Bonvoy in late 2026. Loyalty members book direct, which lowers customer-acquisition cost and reduces dependence on online travel agencies.
5. A commercial and reservation engine that owners pay to access. The reason an independent hotel converts to Graduate by Hilton or joins Curio is Hilton’s distribution, pricing, and loyalty machine. That engine is the durable moat: it makes Hilton’s brands worth more inside the system than outside it.
Weaknesses of Hilton
1. Same-store demand stalled in 2025. System-wide RevPAR rose just 0.4% for the full year, far below the original 2% to 3% guidance. Management pointed to softer US government demand, weaker international inbound travel to the US, and calendar shifts. Unit growth carried the year; underlying property-level demand did not.
2. Record revenue, but net income slipped. Revenue and Adjusted EBITDA both hit records, yet net income came in marginally below 2024. Aggressive buybacks flattered per-share metrics, but the absolute profit line did not grow, a nuance that “record year” headlines gloss over.
3. Limited control over the guest experience. The asset-light model’s flip side is that franchisees run most properties. Inconsistent service or quality at a single franchised hotel still damages the brand, and Hilton’s levers to fix it are contractual rather than direct.
4. A loyalty currency that appraises lower than the competition. Independent valuations peg Hilton Honors points at roughly 0.5 to 0.6 cents each, against about 0.8 cents for Marriott Bonvoy. Hilton offsets this with easier earning and generous elite bonuses, but on a like-for-like redemption basis its points are worth less, and elite suite upgrades are space-available rather than confirmable.
5. US concentration and a leveraged balance sheet. Hilton leans heavily on US demand and runs a deliberately leveraged balance sheet to fund large buybacks. That amplifies returns in good times and raises sensitivity to US macro shocks, interest rates, and any prolonged travel downturn.
Opportunities for Hilton
1. Doubling the lifestyle category. Hilton aims to roughly double its lifestyle portfolio to about 700 hotels by 2028, powered by Graduate by Hilton, NoMad, Canopy, Curio, and Tapestry. Lifestyle carries higher fees and stronger owner demand than commodity midscale.
2. Midscale and extended-stay whitespace. Leadership has hinted at a potential midscale “Undergraduate” brand to sit below the upper-upscale Graduate, plus continued push behind Spark, LivSmart Studios, and the new Apartment Collection. There are, in the CEO’s framing, hundreds of US markets too small for existing brands, a large addressable gap.
3. Luxury at scale. Hilton has been opening luxury and lifestyle hotels at roughly three per week, crossed its 1,000th luxury and lifestyle hotel, and holds nearly 500 more in the pipeline. Luxury commands premium fees and reinforces the brand ladder that pulls guests upmarket.
4. Branded residences and experiential loyalty. Hilton signed 17 branded residences in 2025 and operates 39 with 40-plus in the pipeline, a high-margin, low-capital revenue vein. Meanwhile Hilton Honors Adventures and partnerships with Explora Journeys and AutoCamp extend loyalty beyond hotel nights into experiences.
5. International and all-inclusive expansion. Asia-Pacific (new Conrad and NoMad openings), the Middle East, and a growing all-inclusive and resorts segment give Hilton room to diversify away from US-dependent demand.
Threats to Hilton
1. Marriott’s scale. Marriott still runs a larger footprint (roughly 9,700 properties and 30-plus brands) and a comparably sized loyalty base. Its breadth in luxury and its higher per-point valuation give it an edge with certain high-value travelers.
2. Short-term rentals. Airbnb and peers keep pressuring both leisure and the extended-stay segment Hilton is trying to grow, offering space and price points traditional hotels struggle to match.
3. Demand softness from policy and geopolitics. Reduced US government travel and weaker international inbound demand into the US both dragged on 2025 and could persist. Hilton’s US concentration makes it directly exposed to this.
4. China slowdown and FX. A soft Chinese macro backdrop and currency headwinds weigh on international RevPAR and reported results.
5. OTA intermediation and owner economics. Online travel agencies keep taking a cut of bookings and pressuring direct-booking economics, while labor-cost inflation and financing costs squeeze the franchisee margins Hilton’s growth depends on. If owning a Hilton stops penciling out for developers, the pipeline is the first thing to soften.
The Business Model Analyst Take
Hilton is a fee machine bolted to a growth engine, and in 2025 the engine did the heavy lifting while the machine idled. The bull case is structural: an asset-light model, a contractually locked pipeline of more than half a million rooms, and a loyalty program about to become the largest in the industry. The bear case is cyclical and specific: same-store RevPAR barely moved, net income slipped, and the balance sheet is built for a demand environment that softened in the back half of the year.
For operators studying Hilton, the lesson is the model’s core trade-off. Asset-light growth lets you compound room count regardless of the demand cycle, which is why fees kept rising while RevPAR flatlined. But it also means you win on volume and distribution, not on controlling the product, and it leaves you leveraged to macro demand you cannot steer. Hilton’s 2026 will test whether unit growth can keep outrunning a sluggish top line. If RevPAR reaccelerates toward the guided 1% to 2%, the record narrative holds. If it stalls again, the market will start asking harder questions about a leveraged balance sheet funding buybacks on flat organic demand.