
Most write-ups of the Hermès target market stop at “wealthy people aged 35 to 65 who value craftsmanship.” That is true, lazy, and describes every luxury house from Chanel to Brunello Cucinelli. It explains nothing about why a €16 billion company runs a waiting list on its best product, why it deliberately refuses to sell that product to most people who can afford it, or why the entry point to the brand is a $150 bottle of perfume.
The interesting question is not who the Hermès customer is. It is what Hermès makes her do before it sells her the thing she came for.
Who is the Hermès target market?
Hermès’s target market is split into two tiers that most analyses collapse into one. The visible tier is a broad base of aspirational buyers, mostly women, top 1 to 5% of earners, aged roughly 35 to 65, who enter through fragrance, silk, ties, and small leather goods. The invisible tier is a narrow core of high and ultra-high-net-worth clients, including “VIC” (Very Important Client) buyers often holding more than $30 million in assets, who are the only people offered the Birkin and Kelly bags on any reliable basis.
The brand sells accessible luxury to the base to fund, and manufacture demand for, the gated luxury it reserves for the apex. That structure, not the demographics, is the actual target market strategy.
Definition Box: Hermès Target Market The Hermès target market is the specific set of consumers the brand designs its products, pricing, and boutique experience to serve: affluent and ultra-affluent buyers who treat purchases as heirlooms and status signals rather than fashion. Hermès segments this market by wealth tier (aspirational vs. HNWI vs. UHNWI), product ladder (entry accessories vs. allocated flagship bags), and geography (a mature Asian base plus faster-growing Western and Middle Eastern markets). The defining feature is scarcity: demand is engineered to exceed supply, so buying is gated by loyalty, not just money.
The two-tier structure most analysts miss
Picture the target market as a pyramid, not a demographic profile.
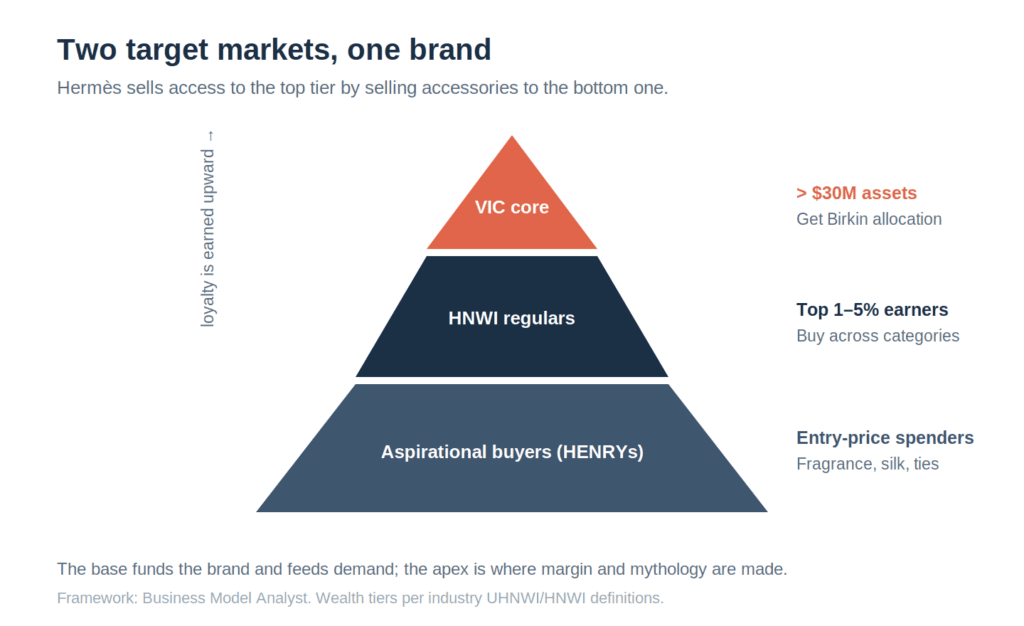
The base is the aspirational buyer, often labeled a HENRY (High Earner, Not Rich Yet). She buys a Twilly, a scarf, a bottle of Barénia. She may never own a quota bag, and Hermès does not need her to. Her spending is real revenue, and her aspiration is the cultural fuel that makes the apex desirable in the first place.
The middle tier is the established HNWI client who buys consistently across categories: shoes, ready-to-wear, homeware, jewelry, watches. This is the buyer Hermès actually wants to deepen, because breadth of purchase is the currency that earns bag allocation.
The apex is the VIC. This client has a relationship with a specific sales associate, a documented purchase history, and a place on the informal list that determines who gets offered a Birkin when one appears. Money is table stakes here. Relationship is the differentiator.
Demographics and psychographics
The surface-level profile is real, it is just not the whole story. Here is the standard segmentation, sharpened.
| Segment dimension | Hermès target profile |
|---|---|
| Age | Core 35 to 65; growing share of younger UHNWIs and collectors under 35 |
| Gender | Skews female (bags, scarves, accessories); men’s categories grew toward ~25% of sales |
| Income / wealth | Top 1 to 5% of global earners; VIC tier often $30M+ in assets |
| Occupation | C-suite, entrepreneurs, heirs, senior professionals, celebrities |
| Geography | Mature Asian base plus fast-growing Americas, Japan, Middle East |
| Psychographic | Values heritage and understatement over logos; buys for permanence |
| Buying behavior | Full-price, in-store, repeat, collection-minded, investment-framed |
The psychographic line is the one that matters commercially. Hermès targets the buyer who wants luxury without a visible logo. That “quiet luxury” positioning is what lets the brand skip the discount-and-advertise cycle its rivals depend on, and it is why the same customer will queue for years rather than defect to a label that will simply sell her a bag today.
The spending ladder is the funnel
The genius of the Hermès target market is that entry is cheap and the top is gated. A newcomer can buy in for the price of a nice dinner. The flagship, by contrast, is not reliably for sale at any price without a relationship behind it.
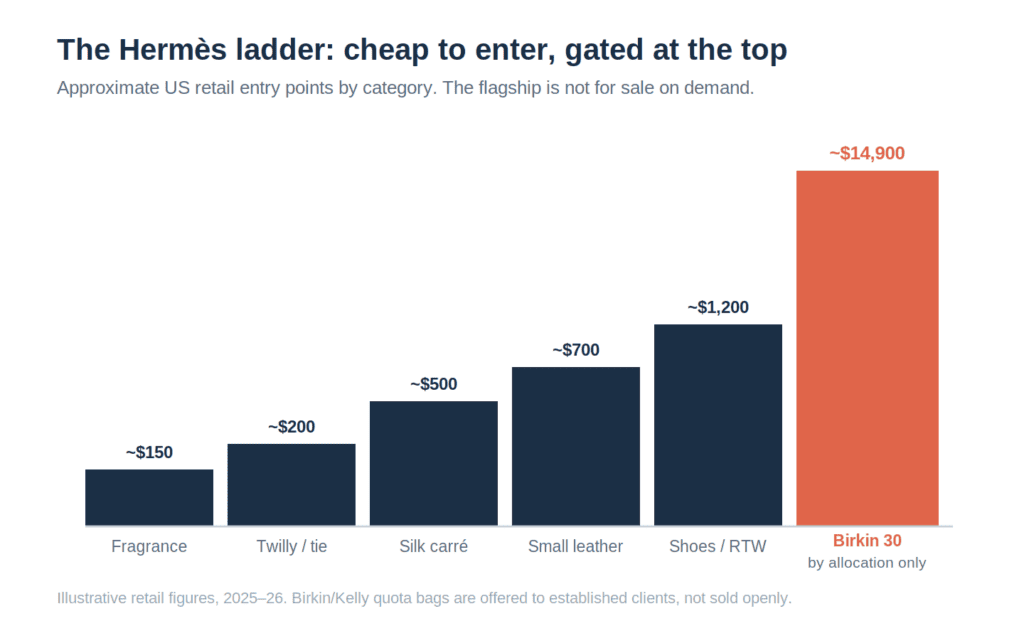
That gap between the $150 rung and the ~$14,900 rung is not an accident of the product mix. It is the mechanism. The accessible rungs recruit and qualify buyers. The gated top rung retains them, because the only way to earn a shot at it is to keep climbing. A buyer chasing a Birkin does not comparison-shop. She builds a purchase history, which is exactly the behavior Hermès wants to reward.
This is the same architecture, at a far higher price point, that powers the Charlotte Tilbury target market: a cheap hero product recruits the customer, and a laddered range monetizes her over time.
Geography: the base and the growth engine are diverging
Where the target market lives is shifting in a way that shapes strategy. Asia excluding Japan is still by far the largest region, but it has become the slowest-growing one as Greater China traffic softens. The momentum has moved to Japan, the Americas, and the Middle East.
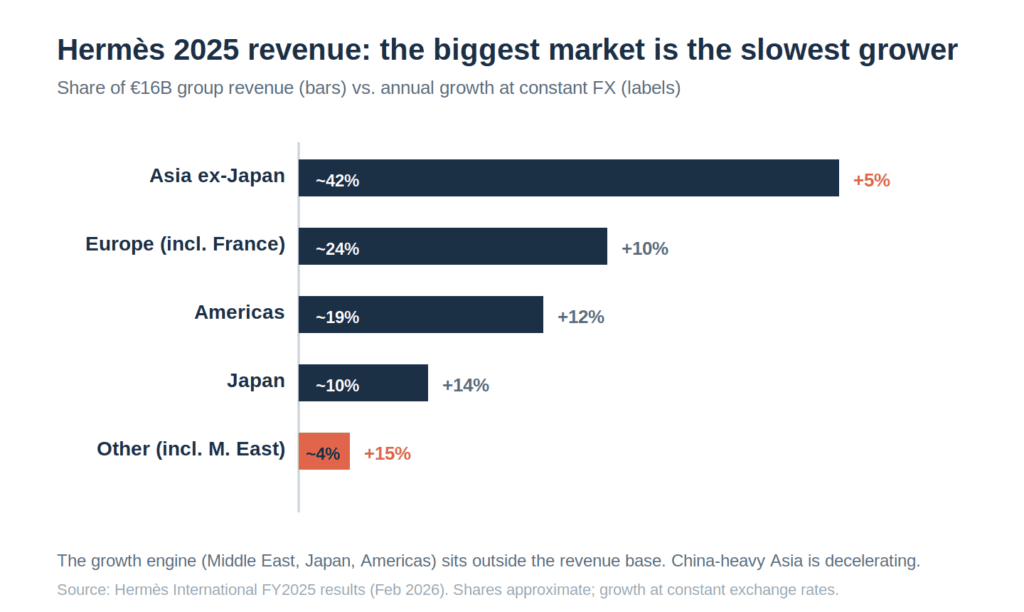
For 2025, Hermès reported roughly €16 billion in revenue, up 9% at constant exchange rates, with a 41% recurring operating margin. Growth by region ran the Middle East at +15%, Japan at +14%, the Americas at +12%, Europe at +10%, and Asia excluding Japan at +5%. The read for target-market strategy is clear: the future customer is more geographically balanced than the past one, and Hermès is opening and renovating stores in Scottsdale, Nashville, Seoul, and the UAE to meet that buyer where wealth is forming now.
Why the aspirational trap is a feature
Skeptics raise a fair objection: if most aspirational buyers never get the bag, is that not a recipe for resentment and churn? For most brands, yes. For Hermès, the frustration is load-bearing. The waiting list is the product. Scarcity is what turns a leather bag into an asset that trades on the secondary market at multiples of retail, which in turn validates every buyer already inside the system and pulls new aspirants toward the base of the pyramid.
The risk is real but bounded. It is concentrated in one place: an over-reliance on high-end consumers means an economic downturn hits Hermès harder than a diversified retailer, a vulnerability the Hermès SWOT analysis treats as the brand’s central structural exposure. So far, full-price demand and vertical integration have absorbed the luxury slowdown that has bruised rivals. That resilience is a direct product of targeting the least price-sensitive buyers on earth.
What builders can take from it
You do not need Birkin economics to use the Hermès playbook. Three moves transfer to almost any premium business.
First, separate your recruiting product from your retention product. The cheap thing exists to acquire and qualify; the gated thing exists to keep. Second, make loyalty legible. Hermès rewards documented purchase history, which gives the customer a reason to consolidate spend with one brand instead of spreading it. Third, let demand exceed supply on purpose where you credibly can. Selling everything to everyone on demand is how you become interchangeable. For the full picture of how these choices connect, the Hermès marketing strategy breakdown maps the distribution and storytelling layer that sits on top of this target-market logic.
The contrast with a mass-luxury approach is instructive. A house like Gucci chases breadth and trend velocity, which grows fast but exposes it to the accessibility-versus-exclusivity tension detailed in the Gucci SWOT analysis. Hermès chose the opposite trade, and the margin gap is the receipt. For a very different segmentation logic aimed at scale rather than scarcity, compare the Amazon target market.
FAQ
Who is the typical Hermès customer? An affluent buyer, usually aged 35 to 65 and skewing female, in the top 1 to 5% of earners, who values heritage and understated quality over visible logos and treats purchases as long-term assets.
What age group does Hermès target? The core is 35 to 65, but the brand is actively capturing younger UHNWIs and collectors under 35 who buy iconic bags as investment pieces.
Why can’t you just walk in and buy a Birkin? Hermès offers quota bags like the Birkin and Kelly to established clients with a purchase history and a boutique relationship. Supply is deliberately kept below demand, so the bag is allocated rather than sold on request.
Is Hermès only for the ultra-rich? No. The entry tier (fragrance, silk, ties, small leather goods) starts around $150 to $500 and targets aspirational buyers. The ultra-wealthy VIC tier is a separate, gated segment for flagship products.
What is Hermès’s biggest market? Asia excluding Japan is the largest region by revenue, though it is now the slowest-growing as Japan, the Americas, and the Middle East accelerate.
The Business Model Analyst Take
The lazy version of the Hermès target market is a demographic. The real version is a machine. Hermès does not sell to rich people so much as it sorts them, using a cheap and welcoming base to recruit aspiration and a gated apex to convert loyalty into margin and mythology. The waiting list everyone complains about is not friction in the model. It is the model.
The strategic lesson is uncomfortable for most founders, because it runs against the instinct to sell more to more people. Hermès grows by being harder to buy from, not easier. That only works if your product genuinely earns permanence and your least price-sensitive customers genuinely believe it. Get those two things right, and scarcity stops being a constraint and starts being the most durable moat in retail.