The state’s own board deck names the most expensive electricity in America, the fifth most expensive land and 90% import dependence. Then it proposes to fix all three with 9,500 square feet of rented warehouse.
Hawaii is trying to replace a stalled tourism economy with advanced manufacturing. The instrument is a $1.2 million, three-year lease on four industrial units in Kailua, which the Hawaii Technology Development Corporation will sublet to ocean-technology startups. The last time the state bought a technology industry it spent up to $1.7 billion in forgone taxes, and the largest category of qualifying investment was performing arts. Both programs subsidize an input. Neither buys a customer.
Drive up Kapaa Quarry Road past the chocolate makers and the boat repair shops and you reach a privately owned light-manufacturing park of roughly 35 buildings. In May, HTDC asked its board for authority to spend up to $1.2 million taking four units there. Four leasable units. About 7,200 square feet of floor space, another 2,200 of mezzanine office, and 12 reserved parking stalls. That is the state of Hawaii’s answer to a tourism economy that peaked in real terms around the turn of the century.
What Happened
The Wall Street Journal published a feature on August 20 following a small band of engineers building hardware companies on Oahu: heat pumps in Kailua, lunar equipment at the University of Hawaii, wastewater parts printed in a yurt above the North Shore. The framing is familiar. A tired resort economy, a young workforce leaving for the mainland, and a handful of founders who might change the trajectory. Ashten Akemoto, who left the heat-pump company last week to start a robotics venture, gave the piece its thesis: “Hawaii needs one unicorn. We need one crazy success.”
The underlying numbers are worse than a growth problem. Hawaii’s June 2026 visitor count came in at 858,577, up 0.2% against June 2025, with total spending of $1.98 billion, up 0.6% in nominal dollars. Average length of stay fell from 8.86 nights to 7.86, an 11.3% drop, while average daily spending per visitor rose 13.2% to $293. Hawaii is holding revenue flat by charging more per day to people who leave sooner. That is a yield-management business, not a growth business, and in real terms it shrank.
Residents keep leaving. Census Vintage 2025 estimates put the state at 1,432,820 people on July 1, 2025, down 2,132 on the year and 22,447 below the 2020 base. Net domestic out-migration ran 8,876. Births and international arrivals covered the rest of the hole. Only California, New Mexico, Vermont and West Virginia also shrank.
The Backstory
Hawaii has run this play before, and the results are documented in painful detail.
In 2001, the legislature passed Act 221. The state’s existing high-technology business investment tax credit went from 10% of an investment, capped at $500,000 a year, to 100% of the investment, claimable over five years, capped at $2 million per investment per qualified business. There was no cumulative ceiling, which meant the state’s exposure had no upper bound. A separate refundable research credit paid 20% of a qualified firm’s research spending.
The Office of the Auditor examined the program in 2012 and again in September 2015. Report 12-05 found that the law and its amendments “did not contain any goals and performance measures” capable of measuring anything. By the 2015 follow-up, the Department of Taxation had identified $1.7 billion in qualifying investment the state remained obligated to honor, roughly double the earlier estimate.
The composition is the part nobody quotes.
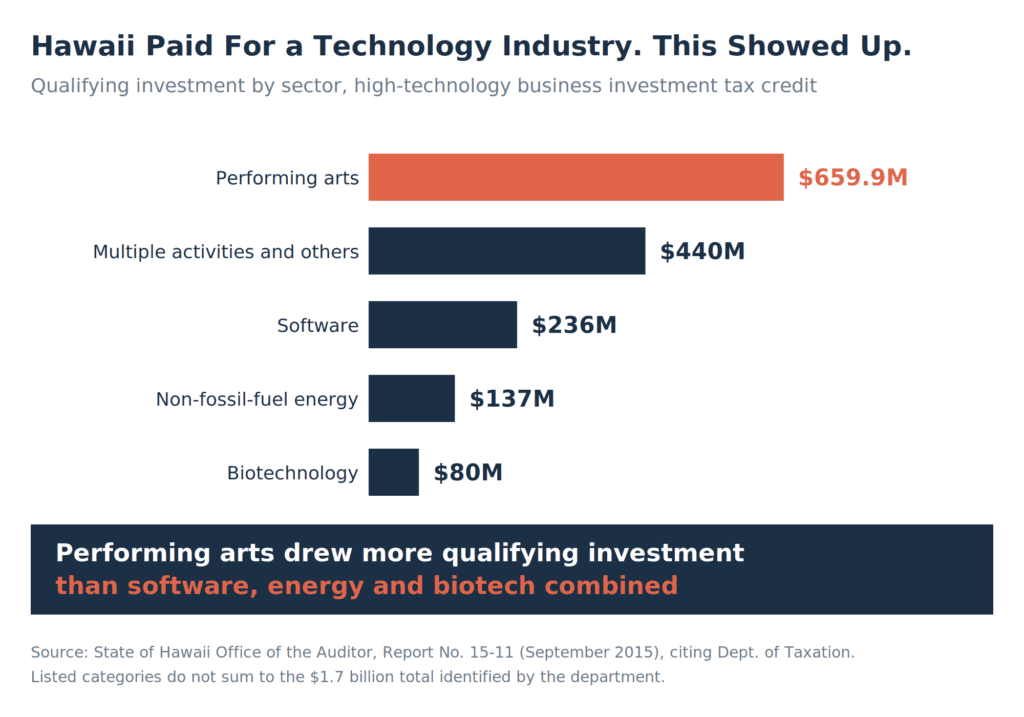
Performing arts companies accounted for $659.9 million of qualifying investment. Software drew $236 million, non-fossil-fuel energy $137 million, biotechnology roughly $80 million. Performing arts beat all three combined by more than two to one. In the program’s first two years, film investors collected enough that a single movie absorbed close to 40% of the credits granted, according to a UHERO working paper, before the tax department began denying one-shot production deals in 2003.
Hawaii did not fail to build a technology industry. It built precisely what it paid for. The credit rewarded qualifying investment, so the activity that showed up was the one best equipped to manufacture qualifying investment against a deadline: film and stage production, with a five-year credit schedule and a 100% match. The legislature killed the investment credit in 2009 and let the research credit lapse in 2010. Taxpayers were still paying out $16.3 million a year on it in 2016.
The Plan
The HTDC board deck from May 14, 2026 deserves more attention than the one line it earned in the Journal, because the agency has already written down the reason its own project will struggle.
Page seven states that Hawaii’s manufacturing sector is 2% of state GDP against 10.3% nationally, the lowest share in the country. It lists the causes: the fifth most expensive land in the United States, the most expensive energy, and import dependence exceeding 90% for consumer goods, building materials and petroleum. It notes Hawaii ranks 48th for ease of doing business. The internal SWOT files the state’s operating and living costs under weaknesses, and puts climbing infrastructure, energy and supply chain costs under threats to competitiveness.
The energy number is not a rounding error. EIA’s 2024 State Electricity Profiles put Hawaii’s average retail electricity price at 38.00 cents per kilowatt-hour, ranked first in the nation, against a US average of 12.94 cents on the same basis. A Hawaii manufacturer pays about 2.9 times what a mainland competitor pays for the same kilowatt-hour, then ships the output back across the Pacific. German chemical plants learned the same lesson on the Rhine, where geography turned into a permanent line in the cost structure rather than a bad season.
Having diagnosed a cost problem, the deck proposes a rent solution. HTDC negotiated a three-year lease at $26,000 a month plus general excise tax, with a 4% annual escalator and one month free. Total lease expense across the term: $992,606. It will sublet on one-year terms at $3 per square foot, with tenants able to pay in a mix of cash rent and equity or revenue share.
Run the arithmetic on the spread. $26,000 across roughly 9,500 square feet works out to about $2.74 per square foot. HTDC sublets at $3.00. The gross markup is under 10%, and the base case pays a property manager 10% of rental income. Across three years the base case collects $836,228 in rent, parking and office income against $992,606 of lease payments. Add utilities, management fees and $77,500 of buildout, and the property operation loses $323,501.
The base case still shows a $176,500 profit. The difference is $500,000 in grants: $300,000 federal, $100,000 from NIST’s Manufacturing Extension Partnership, $100,000 private. Grant money is 37% of base-case revenue. In the optimistic scenario, where the deck projects $1.42 million of profit, grants and matched funding reach $1.6 million of $2.54 million in revenue, or 63%. The state’s best case for a manufacturing facility is one where most of the money comes from grants.
The conservative case loses $518,707. The deck also prices the exit: walking away at month 12 costs $509,442 in buildout, penalty and accumulated losses. Quitting after a year saves $9,265 against riding out all 36 months. Two footnote-level cautions for anyone citing the deck: its conservative scenario is labelled 51% average occupancy in the narrative and 67% in the assumptions table, and the year-by-year figures given (81%, 60%, 60%) support the higher number.
The Business Model Angle
Look at who is moving in. Makai Ocean Engineering sells to the US Navy, DARPA and the Department of Energy. Pacific Impact Zone lists more than 300 customers inside INDOPACOM. The Hawaii Natural Energy Institute works for the Department of Energy and NAVFAC. Hawaii Ocean Power Solutions counts DOE, the Navy and NOAA. Hohonu sells flood data to NOAA, the Florida Department of Transportation and municipal governments. WaiHome sells cesspool replacements into a state law requiring every cesspool in Hawaii to be converted by 2050.
Six anchor candidates, and every one of them sells into a government budget or a regulatory mandate.
Now look at who got deprioritized. The deck’s backup list includes the Airform heat-pump company, 20 employees and 100 pre-purchases, rated medium risk, and Dakine Robotics, three employees and no customers, rated high. Those are the two with private, mainland-facing markets. HTDC’s own risk model says that in Hawaii, selling hardware to private mainland buyers is the risky business and selling to the Pentagon is the safe one.
That model is correct, and it points somewhere other than a warehouse.
Defense already accounts for 10.3% of Hawaii’s GDP, the highest share of any state in FY2024 according to DBEDT, with defense spending per resident third highest nationally and third fastest growing. The MACRO factbook released in February puts direct defense activity near 9% of GDP, $17.4 billion including indirect and induced effects, and roughly 17% of all jobs tied to it. The deck itself quotes INDOPACOM saying it does “not want to be wholly reliant upon things from” the continental United States.
Hawaii’s only large non-tourism industry was not built by a tax credit or an incubator. A customer with a mainland budget and a strategic reason to buy locally built it. That is the same engine behind the Anduril business model, where a defense buyer, not a subsidy, funds the industrial base. That is the asset the state owns and is not selling.
The siting rule this implies is value density. A business survives 38-cent electricity and Pacific freight only if it earns enough revenue per kilowatt-hour and per pound shipped to absorb them, or if its customer is standing on the same expensive rock. Satellite components, sensors, subsea software and defense sustainment pass. Heat pumps built in Kailua and sold in Phoenix do not, and no amount of subsidized floor space changes that.
The land market compounds it. DBEDT’s May 2026 study of Japanese investment found that 98.8% of commercial real estate transactions with a Japanese buyer went to tourism tax classes, hotel, resort or vacation rental. In November 2025 Daisho paid $510 million for the land under the Royal Hawaiian. Outside capital arriving in Hawaii bids for hotel dirt, and a hotel room monetizes a square foot at a multiple no machine shop can match, which is the whole point of the hotel value chain. Short-term rentals push the same bid down into residential blocks, since the Airbnb business model turns any house into inventory priced against nightly demand. The industry the state wants to escape is the one setting the price of the land it needs.
The Risk
The strongest case against this reading is that $1.2 million is a call option, not a bet. HTDC is buying information about whether co-located ocean-tech manufacturing works in Hawaii, and $400,000 a year is a cheap price for an answer. Judging a pilot by its three-year P&L misreads the instrument. That defense holds, and it is the one the board should press.
The deck is also better governance than anything Act 221 produced. It models three scenarios, prices its own exit, names its risks and lists Hawaii’s cost disadvantages on page seven rather than burying them. The 2012 audit found a program with no goals and no performance measures at all. This one has a decision point at month 12.
Physical clustering has precedent. AltaSea in Los Angeles, Washington Maritime Blue and New Zealand’s Blue House all exist, and hardware companies do benefit from shared prototyping space. Hawaii’s blue economy runs at about 8% of the state economy with marine businesses up 23% over the decade, which is real agglomeration rather than wishful thinking.
The defense argument cuts both ways. Swapping a tourism monoculture for a procurement monoculture concentrates the state’s fortunes in one buyer whose budget moves on political timing. A “True Cost” report published in May, co-authored by David Vine, argues the military’s economic contribution to Hawaii has been overstated, and federal cuts already weighed on the state’s 2026 outlook. Retired state economist Eugene Tian noted the competing studies use different bases, so the 9% and 10.3% figures are not interchangeable.
One more constraint deserves naming. Hawaii’s unemployment rate in June 2026 was 2.6%. The state does not have a job shortage. It has a wage and cost problem, and the deck’s promised salaries of $50,000 for a high school graduate and $90,000 for a bachelor’s degree read differently in a state where incomes adjusted for cost of living rank among the lowest in the country.
Quick Questions
Did Act 221 cost $1 billion or $1.7 billion? Both figures circulate. The 2012 audit produced the roughly $1 billion estimate. The 2015 follow-up raised it to as much as $1.7 billion after the tax department identified that much in qualifying investment the state was still obligated to honor.
Is the Kapaa project approved? The board deck asked for authorization to spend up to $1.2 million over three years. The Journal reports the corporation is signing the lease, and board members had questioned the state acting as a landlord.
Why ocean tech rather than space or defense? HTDC identified ocean technology as its focus sector last summer and wrote SB2907 to designate Hawaii an ocean cluster. The deck argues the blue economy shows the clearest agglomeration and the strongest local pipeline.
Is the state taking equity in tenants? The negotiated sublease terms give tenants the option to pay in a mix of rent and equity or revenue share. That makes a state landlord into a de facto seed investor without an investment mandate.
What happens if tenants leave after year one? The conservative case drops to two tenants and loses $518,707. HTDC’s stated mitigation is a waitlist and, failing that, filling the space with companies outside its sector focus.
The Business Model Analyst Take
Subsidize an input and you get more of the input. Hawaii paid for qualifying investment and received $659.9 million of performing arts. It is now paying for floor space, and it will receive floor space, occupied by six organizations that already had customers before the lease existed. Neither program produced demand, because neither program was buying any.
Founders repeat this at smaller scale constantly. Cheap office space, a grant, a subsidized hire, an accelerator seat. Each one lowers a cost line. None of them puts a buyer in the room, and a company with lower costs and no buyer dies at a slower rate rather than a different one.
The second lesson is about cost bases you do not control. When the incumbent industry in your market sets the price of your land, your power and your labor, you take prices on inputs while competing on outputs against people who do not. Hawaii’s hotels can absorb 38-cent electricity because they sell the island itself. A heat-pump manufacturer shipping to Phoenix cannot. The winning businesses on that rock are the ones where the expensive thing is the product, not the overhead.
HTDC already knows this. Its deck says so on page seven, and its risk ratings say so again on page 41, where the government-facing tenants are low risk and the mainland-facing ones are not. The document contains the answer the lease is being bought to find.
Hawaii does not need one unicorn. It needs one buyer it can name.