
The company that called the record owns one of the five auction houses, publishes the price guide everyone quotes, and writes the insurance afterward. Only one of those three pays the bills, and it grew this year without any help from rising car values.
Hagerty told CNBC that Monterey Car Week could clear half a billion dollars in auction sales for the first time. It might. But Hagerty’s own first-half numbers show written premium and policy count both growing 19%, which means the average premium per policy did not move. The record everyone is watching this week sits in a division that produces about one dollar of revenue for every ten the insurance side writes.
Five auction houses set up within a few miles of each other on the Monterey Peninsula every August, and for nine days the collector car world prices itself in public. This year McKeel Hagerty, CEO of the insurance, auction and events company that supplies the market’s benchmark data, went on the record with a number: $470 million to $500 million, enough to beat the $471.2 million record set in 2022. Reporters ran with the generational story attached to it, where millennials and Gen Z buyers replace boomers and bid bedroom-poster supercars into the eight figures. That story is real. It is also not where Hagerty earns anything.
What Happened
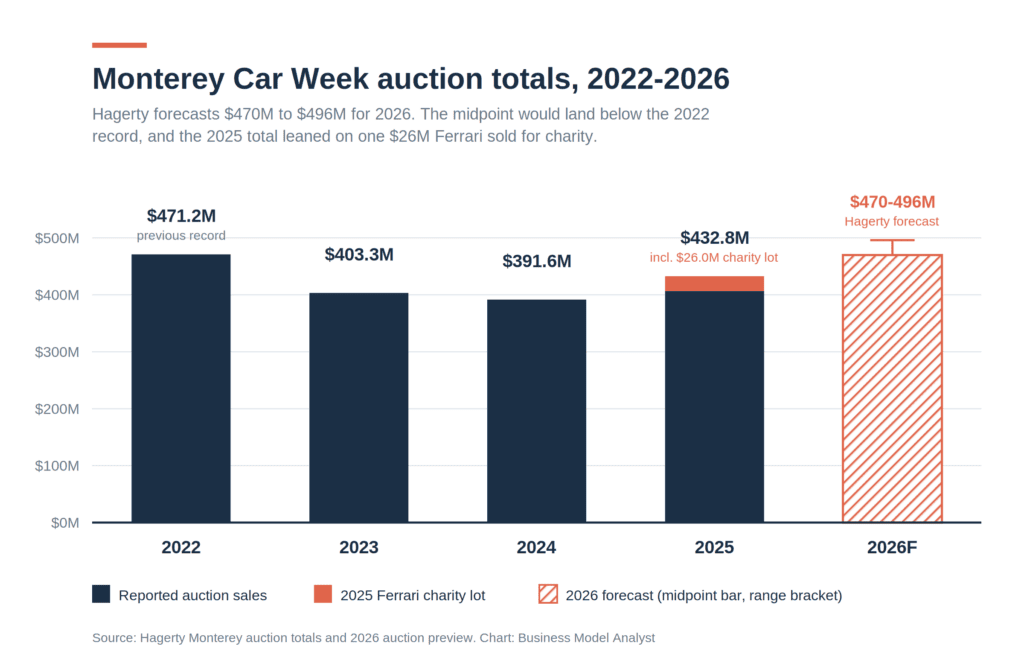
Hagerty forecast total sales of $470 million to $500 million for the 2026 Monterey auctions, held from August 7 to 16 and running through the Pebble Beach Concours d’Elegance. The midpoint of its published forecast is $470 million, with an optimistic case at $496 million. Beating 2022 requires the strong end of that range.
McKeel Hagerty framed it as a potential first: half a billion dollars in a single collector week. He also gave reporters the quotable summary of where the money is going, noting that all roads lead to Maranello. Nine of the ten most expensive cars sold at auction anywhere so far in 2026 have been Ferraris, and five of Monterey’s top lots this year carry the same badge.
The headline consignment is a 1996 McLaren F1 GTR at RM Sotheby’s, estimated at $35 million. A 2023 Ferrari Daytona SP3 carries an estimate above $10 million. A Chevrolet Corvette Grand Sport and a Shelby Cobra Daytona Coupe are both crossing the block for the first time since 2009. Hagerty expects modern supercars, which it defines as 1984 and newer, to take 60% of total sales.
The Backstory
The four years before this one tell a flatter story than the forecast suggests. Monterey hit $471.2 million in 2022, fell to $403.3 million in 2023, dropped again to $391.6 million in 2024, then recovered to $432.8 million in 2025.
That 2025 recovery deserves an asterisk, and Hagerty put it there itself. The top lot was a one-of-one 2025 Ferrari Daytona SP3, built as an extra unit beyond the model’s 599-car run and sold at $26 million with proceeds going to the Ferrari Foundation. Strip it out and the week produced $406.8 million, up 4% on 2024. A philanthropic transaction carried a third of the year-over-year gain.
Underneath the auction headlines, Hagerty’s own valuation data has been sliding for years. Its Collector Car Market Rating fell to 58.28 in January 2026, the lowest reading in almost 15 years, after declining in 37 of the previous 43 months. By June it sat at 58.59, still in flat territory. The Price Guide overall metric hit 56.15 in May, the weakest since the winter of 2012, and the median value for a good-condition car set an all-time low.
The split inside that data is the part worth holding on to. Hagerty’s Blue Chip Index of 25 seven-figure cars stood at 75.54 in June. The Hagerty Hundred, which weights the 100 most commonly insured vehicles in the price guide, had fallen to 48.32. Four years ago those two indexes sat 2.78 points apart. The gap is now 27.22 points. One number describes the cars crossing the block at Pebble Beach. The other describes the cars in Hagerty’s customers’ garages.
The Plan
Hagerty built a business that touches the collector car at every point in its life, and Monterey is where the whole stack goes on display.
The insurance sits at the centre. Hagerty runs managing general agent subsidiaries plus Hagerty Re, its own reinsurance vehicle, and on January 1, 2026 it moved to a fronting arrangement with Markel that lifted Hagerty Re’s US quota share from 80% to 100%. The company now owns the underwriting result on its US book rather than collecting a commission on someone else’s.
Around that sit the other pieces. Hagerty bought roughly 40% of Broad Arrow Group in early 2022 and the remaining 60% for $64.8 million in stock that August, which made one of the five Monterey auction houses a subsidiary. Broad Arrow Capital lends against collector cars. Hagerty Marketplace runs digital auctions and classifieds at a 7% bidder premium. Hagerty Valuation Tools publishes the Price Guide, the Market Rating and the eleven indexes that dealers, insurers and reporters treat as the market’s scoreboard. Hagerty Media covers the auctions. Hagerty Drivers Club sells the membership. Motorlux runs the party.
The company spent the first half of 2026 buying more distribution rather than more cars. It converted State Farm classic policies, acquired UK motorcycle insurer Bennetts for £34 million, crossed three million insured vehicles, and raised full-year guidance to 16% to 17% written premium growth with adjusted EBITDA of $270 million to $280 million.
The Business Model Angle
Run the arithmetic on Hagerty’s first half and the auction story falls out of the P&L.
Written premium grew 19% to $713 million. Policies in force grew 19% to 1.9 million. Those two numbers are the same, which means average written premium per policy landed at roughly $375 for the half, unchanged from a year earlier. Every dollar of premium growth came from selling more policies. None of it came from the cars getting more valuable.
| Hagerty, first half 2026 | Figure | Change |
|---|---|---|
| Written premium | $713M | +19% |
| Policies in force | 1.9M | +19% |
| Written premium per policy | ~$375 | flat |
| Earned premium | $492M | +42% |
| Marketplace revenue | $65M | +17% |
| Adjusted EBITDA | $160M | +32% |
That matters because Hagerty sells agreed-value coverage. A member declares what the car is worth, the premium scales with that number, and a rising market should push premium up across the existing book at zero acquisition cost. It is the cleanest same-customer growth engine in specialty insurance. This year it delivered nothing, and Hagerty’s own data explains why: in January, only 35.2% of privately sold cars traded above their insured values, the lowest share in nearly four years, and requests to raise coverage on cars under $250,000 hit their weakest ratio in more than four years. Members stopped marking their cars up because the Hagerty Hundred stopped going up.
Now size the auction side against it. Marketplace revenue came in at $119 million for full-year 2025 against $1,194 million of written premium, almost exactly one tenth. The first-half 2026 ratio is the same, $65 million against $713 million. Broad Arrow charges a buyer’s premium of 12% on the first $250,000 of hammer price and 10% above that, and its entire 2025 across auctions, private sales and financing came to $624 million of transactions. A $500 million Monterey week spread across five houses, only one of which Hagerty owns, moves a rounding error through a business writing $425 million of premium every quarter.
There is a demographic wrinkle here too. The auction block says millennials and Gen Z are taking over. Hagerty’s insurance quote data said something else: boomer quote activity grew faster than any other demographic in 2025, and the agreed values attached to those quotes grew the most. Hagerty’s own price guide editors went into 2026 predicting appreciation for boomer favourites like the 1963-67 Corvette and limited appreciation for millennial favourites like the R34 Skyline. Auctions are where the rotation shows up first because auctions are where speculation is cheapest to express. Policy applications are slower, larger and more honest.
Hagerty is running a subscription business with an asset market bolted on as the top of the funnel. The auction generates coverage, the coverage generates members, the members renew. Ferrari plays the same trick from the manufacturing side, where deliberate scarcity does the work that volume cannot and the secondary market prices the brand for free. Sports franchise buyers reach for the same logic when they pay up for assets they believe technology cannot replicate.
The Risk
Owning the underwriting result changes Hagerty’s exposure in both directions. Hagerty Re posted a 40.6% loss ratio and an 88.1% combined ratio year to date, which is excellent, but agreed value is a two-sided instrument. Higher declared values raise severity on every total loss. A book that inflated through the 2021-22 boom and now sits above a softening market is carrying settlement obligations set at yesterday’s prices. The company also absorbed $153 million of Markel transition costs and posted a $5 million first-half net loss to get here.
The case against my own reading deserves a hearing. Flat premium per policy could be a mix effect rather than a value effect. State Farm conversions and a UK motorcycle book are cheaper policies by construction, and adding hundreds of thousands of them would drag the average down even if the core collector book appreciated. Hagerty does not disclose premium per policy by segment, so nobody outside the company can separate the two. What we can say is that the disclosed growth rates are identical and the disclosed insured-value request data points the same direction.
The bigger structural risk is what happens if the Hagerty Hundred keeps sliding. Three million insured vehicles overwhelmingly live in the broad market, not in the Blue Chip Index. If declared values start falling rather than stalling, premium per policy turns negative and unit growth has to carry the entire business forever. Buying distribution works until the distribution runs out.
Then there is the governance question nobody in the coverage asked. The company forecasting the record owns one of the five auction houses, lends against the assets, publishes the index the market uses as an independent benchmark, and runs the media outlet reporting the results. Hagerty discloses all of it and none of it is improper. It does mean that anyone treating the Hagerty Price Guide as a neutral third-party valuation is treating a vertically integrated participant as a referee.
Hagerty’s own market desk put the honest version of the risk on its site this week: if the top of the market pauses, Monterey is where it shows first.
Quick Questions
Will Monterey 2026 actually break the record? The midpoint forecast of $470 million lands below the 2022 record of $471.2 million. Beating it needs bidding at the optimistic end of Hagerty’s range. Final totals land after August 16.
Why is the record coming from consignments rather than demand? Hagerty says the lot count and the reserve ratio are roughly flat on 2025. More seven- and eight-figure cars were consigned this year than in any previous Monterey, which lifts the total without requiring a broader market to improve.
Does a record auction week help Hagerty’s earnings? Barely, in direct terms. Marketplace produces about a tenth of the revenue that written premium does, and Hagerty owns one of the five houses. The auction matters as a demand-generation event for the insurance funnel.
How does Hagerty make money on collector cars? Specialty insurance is the engine, sold through MGA subsidiaries and reinsured through Hagerty Re, which took 100% of the US quota share in January 2026. Auctions, financing, classifieds, media and the Drivers Club membership feed it.
Is the collector car market rising or falling? Both, in different places. Hagerty’s Supercar Index rose 19% between January and April 2026 while the Blue Chip Index and the Hagerty Hundred sit 27 points apart, with the broad market at a multi-year low.
The Business Model Analyst Take
Two metrics can describe the same business and point in opposite directions, and the loud one is rarely the one you manage. Hagerty’s loud metric is a half-billion-dollar auction week that produces press coverage in every business outlet in America. Its quiet metric is written premium per policy, which sat flat while the loud number set records.
The company appears to know which is which. It spent the first half of 2026 buying policy count through a State Farm conversion and a £34 million motorcycle insurer rather than waiting for the collector market to reflate its existing book. That is the correct read of its own data. Boomers are still the ones filling out applications, the broad price guide is at a multi-year low, and members have stopped marking their cars up.
For anyone building a business where a public price is part of the brand, the lesson is separable from cars. Decide early which number is your marketing and which is your revenue, then make sure your capital allocation follows the second one. Plenty of operators get this backwards and end up managing the headline. Hagerty appears to be managing the renewal, and telling everyone about the headline. That is the right order.
The honest caveat: this reading depends on flat premium per policy being a value story rather than a mix story, and Hagerty does not give outsiders enough disclosure to settle it. Watch the Q3 print for whether policy growth and premium growth stay locked together. If premium growth pulls ahead of policy growth, the collector market is genuinely reflating the existing book and the auction headline is doing real work. If premium growth falls behind, the flywheel has a problem that no record week at Pebble Beach can fix.