
The Wall Street Journal found collectors trading Corvettes for Luminas and Tauruses. Hagerty’s own filings show a 29-point loss-ratio advantage built on customers who barely drive, and a growth plan that recruits people who do.
Hagerty earns a 39% average loss ratio against an industry average of 68%, and its investor materials credit that gap to owners who drive less, garage their cars, and have decades of clean records. The everyday-classic boom brings in a different buyer: cheaper cars, younger owners, one vehicle per policy instead of two. Management has told investors it wants to double policies in force to 3 million by 2030, and the channel it is using to get there is State Farm’s agent force. The growth is real. The 29 points were never a property of the cars.
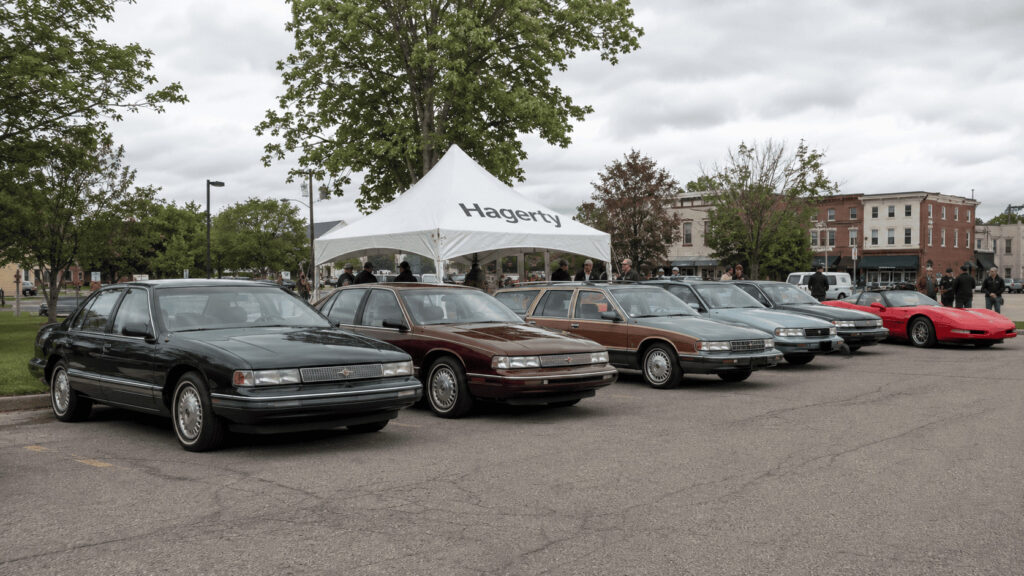
David Cascino parked a 1990 Chevrolet Lumina at a Western New York car show next to a Corvette, and the Corvette’s owner told him to Cascino now keeps 17 cars in a barn he built with his father. Somewhere in that story is a cultural shift worth writing about. Somewhere else in it is a specialty insurer with a stated plan to add more than a million policies in four years, and a pricing model that assumes the cars sit still.
What Happened
Ellie Davis reported in the Journal on August 16 that collectors are showing up at car shows with Chevrolet Luminas, Ford Tauruses, Buick Roadmasters and 2000s Honda Civics. The print edition ran it under a headline calling everyday classics a boon to insurers.
The reporting carries three numbers from the carriers themselves. Hagerty has more than doubled the count of 2000s Civics and Corollas it insures in three years. At OpenRoad Insurance, 40.3% of covered vehicles were built in 1980 or later, per chief marketing officer Bryan Ballatore. Hagerty’s average customer was 53 last year, and Gen-Z policies grew 48% year over year.
The people in the article bought at prices that fit the pattern. Adam Scipione, 19, paid $2,000 for a 1996 Buick Roadmaster Wagon in 2023. Dominic DiLettera, also 19, spent $3,000 at age 15 on a 1989 Cavalier Z24. Richard Owens, 38, assembled eight Tauruses at $2,000 to $5,000 apiece. Chad Corcoran picked up his 1991 Taurus SHO Plus for $1,800.
Brian Rabold, who runs automotive intelligence at Hagerty, told the Journal he steers away from the words classic and collector, and put the typical buyer at around $25,000 for a car with nostalgic value. That is the vocabulary of an underwriter widening a box, not a curator defending one.
The Backstory
Frank and Louise Hagerty started the company in Traverse City in 1984 because nobody would write a decent policy on their wooden boats. Classic cars followed in 1991. McKeel Hagerty took over in 2000 and spent the next quarter century turning a niche agency into a public company with a price guide, an auction house, a lending arm and a media operation.
The financial engine underneath all of it is one number. In the Q2 2026 investor materials, Hagerty told the market it compounded US auto premium at 13% a year from 2010 to 2025 against 5% for the industry’s top 100 carriers, and did it at an average loss ratio of 39% versus 68% for the industry. Management attributes the 29-point gap to three properties of collector vehicles: they get driven less, they get stored better, and their owners have more experience behind the wheel.
Read that list again. None of the three describes a car. All three describe a person, and a garage.
The customer sorts himself into the book. A man with a $250,000 Porsche and a $40,000 daily driver puts the Porsche on the specialty policy because he has somewhere else to put the commute. That self-selection, not any feature of a 1967 911, produces the loss ratio. Hagerty prices the discount off it: the agent-facing material advertises premiums up to 21% below standard auto insurance, and the Farmers-branded version justifies the number by telling shoppers these cars get driven less and get driven carefully.
The same page also promises no mileage limits.
The Plan
Hagerty’s 2026 priority list, laid out for investors alongside the Q4 2025 results, starts with doubling policies in force to 3.0 million by 2030. The book stood at 1.86 million at the end of June. Getting to 3.0 million inside four and a half years means roughly 250,000 net adds a year, on top of replacing the 11.8% of policies that lapse annually. Gross new business has to run somewhere near half a million a year to clear that hurdle.
The distribution answer is already visible in the numbers. State Farm agents now sell Hagerty policies in 37 states, with book conversions on pace to finish in 2028. Nationwide and Farmers carry the product too. State Farm alone wrote 18.64% of US private passenger auto premium in 2025 per NAIC data, and its agents spend their days around Camrys and F-150s.
Plug a specialty product into the biggest mass-market agent networks in America and the marginal policy stops looking like a Porsche. It looks like a Taurus. The Journal wrote a taste story. The mix shift arrived by design.
Second-quarter results show the machine running. New insurance business count jumped 90.0% to 166,951. Written premium rose 19% in the half to $713 million. Hagerty added a record 279,000 members in six months and crossed 3 million insured vehicles.
The Business Model Angle
Divide FY2025 written premium of $1,194 million by 2.8 million insured vehicles and you get about $426 per vehicle per year. Insurify puts the average US full-coverage policy at $2,237. Hagerty collects roughly a fifth of what an ordinary carrier collects on an ordinary car, and it does that against an obligation to pay an agreed value in full, without depreciation, on a covered total loss.
That entire price gap is one assumption wearing a policy jacket: the car barely moves.
Two things about the marginal customer strain the assumption. The vehicle count is the first. Insured vehicles grew 13.8% in the year to June while policies grew 19.0%, so vehicles per policy slipped from about 1.70 to 1.63. New members are arriving with fewer cars each, and a household with one old car has fewer places to put its miles than a household with three.
The second is repair arithmetic. CCC Intelligent Solutions found total-loss frequency hit 23.1% of claims in 2025, a record, while repairable appraisals under $2,000 collapsed from 41.5% of the total in 2019 to 25.5% by mid-2025. Sensor calibrations now appear on 28.3% of repairable estimates. The floor under a body-shop invoice has risen above the entire agreed value of a $2,000 Roadmaster. On a $250,000 car, a crumpled fender is a repair. On Scipione’s wagon, the same impact is a total loss by arithmetic, and Hagerty writes a check for the whole insured amount.
Then the customer leaves. CCC’s claims research found 40.4% of collision claimants whose car was totaled switched carriers afterward, about 33% higher than the defection rate on repairable claims. Hagerty’s model compounds on renewals, and retention has ticked down through five consecutive reports: 89.0% at the end of 2024, 89.0% in March 2025, 88.7% in June, 88.7% in December, 88.2% this June.
The headline loss ratio deserves a second look on the same grounds. FY2025 printed at 39.3%, the number that lets the 15-year average hold. Hagerty’s own release attributes 2.8 points of that to a $21 million reserve release on favorable 2024 development. Strip it and the year comes in at 42.1%. The first half of 2026 landed at 40.6%.

The Risk
The bear case here is a rate-of-change argument, and the current P&L argues against it. Hagerty Re’s combined ratio improved to 88.1% in the first half from 89.1%. Operating cash flow nearly doubled to $186 million. Management raised full-year guidance to 16% to 17% written premium growth and $270 million to $280 million of adjusted EBITDA. Nothing has broken.
Three counterarguments deserve weight. Agreed value caps absolute severity at a trivial number on a cheap car, so a book full of $3,000 Cavaliers carries less catastrophe exposure than a book full of Bugattis, and Hagerty can charge a minimum premium that makes the rate on exposed value far richer at the bottom than at the top. The vehicles-per-policy decline also has confounders: the State Farm conversions import existing single-car policies wholesale, and Hagerty announced a deal for UK motorcycle insurer Bennetts at GBP 34 million, which adds one-vehicle policies by construction.
The generational framing is shakier than either the Journal or the CNBC coverage of Monterey suggested. Hagerty’s own quote data shows baby boomers retaking the largest-cohort position in 2025, and Gen-Z sits near 8% of the book. A 48% increase on a small base moves the growth chart more than the loss triangle.
What would settle it is a single disclosure Hagerty does not give: loss ratio by insured value band. Until then, the Q3 print offers the cheapest read available. Watch whether the loss ratio holds near 40% while new business keeps running at double the prior-year pace, and watch whether retention stops at 88.2% or keeps sliding.
Quick Questions
Is Hagerty losing money on cheap cars? Nothing in the disclosures shows that. The first-half combined ratio improved year over year. The argument is about the direction of the mix and the claim type it imports, not about today’s results.
Why would an insurer want a $2,000 car on its books? Because the premium is set by a minimum, not by a percentage of value, and because the customer is 19 and might renew for 50 years. Hagerty sells memberships, valuation data, auction access and financing to the same person.
Does agreed value cost the insurer more? On an expensive car, yes, since it pays above depreciated market value. On a $2,000 car, agreed value functions as a ceiling that sits below what a body shop would charge to fix it.
Is the everyday classic trend real or manufactured? Both are visible. Hagerty’s RADwood-era index rose 42% to 73% over five years while its Blue Chip index sat flat. OpenRoad also hired a public-relations agency of record on August 10 with an explicit brief to place its executives as media sources on classic-car insurance and vehicle valuations, and the Journal quoted its CMO six days later.
What is the number to watch? Written premium per insured vehicle. FY2025 came in around $426 against roughly $408 the year before. If that figure stalls while policy count accelerates, the down-market mix is real and Hagerty is funding growth with price.
The Business Model Analyst Take
Insurance sells a promise priced before anyone knows the cost, and the whole craft sits in deciding who gets to buy it. Hagerty spent 40 years building the best selection filter in personal auto: a product so specific that only the right customer wants it. The 39% loss ratio is what that filter pays out.
Widening the filter is the growth plan, and the filter is the margin. Both statements are true at once, which is the interesting part. Rabold’s discomfort with the word classic is not brand positioning. He is describing the moment an underwriting box stops being a moat and starts being a market.
Cascino is right that a car with a story can be a collectible. He proved it with a Lumina and $1,000. The open question is whether an insurer that says yes to 500,000 of him a year still owns a specialty book, or has quietly become a cheap auto carrier with a magazine.