

Gymshark just posted its thirteenth consecutive year of sales growth. It also posted the smallest pre-tax profit in its modern history. Those two sentences describe the same company in the same set of accounts, and reconciling them is the entire job of a Gymshark SWOT analysis in 2026.
Most SWOT write-ups on this company are still running a 2020 script: disruptive direct-to-consumer brand, influencer marketing genius, huge opportunity in physical retail. Every one of those claims is either out of date or actively backwards now. Gymshark has spent the last four years converting a capital-light online business into a lease-encumbered omnichannel one, and it has done that during a category slowdown and a tariff shock. The strengths are real. So is the bill.
This analysis works from the numbers Gymshark Ltd actually filed at Companies House for the financial year ended 31 July 2025, plus everything the company has announced since. Where a figure is calculated rather than reported, it is labelled as such.
What Is a Gymshark SWOT Analysis?
SWOT analysis is a strategic planning framework that sorts a company’s position into four buckets: Strengths (internal advantages), Weaknesses (internal constraints), Opportunities (external openings), and Threats (external risks). The first two are things a company controls. The second two are things it responds to.
A Gymshark SWOT analysis applies that frame to Gymshark Ltd, the Solihull-based fitness apparel brand founded in 2012 by Ben Francis and Lewis Morgan. As of the FY25 accounts, Gymshark reported revenue of £646 million, pre-tax profit of £7 million, a gross margin of 62.3%, and around 900 staff. Founder Ben Francis holds more than 70% of the equity. General Atlantic holds 21%, bought in August 2020 in a deal that valued the company above £1 billion.
The headline finding of this analysis: Gymshark’s strengths are financial and cultural, its weaknesses are structural and getting worse, and its opportunities and threats point at the same thing, which is the shift from selling online to selling everywhere.
New to the framework? Start with what a SWOT analysis is and how to do one, or browse more SWOT analysis examples.
Gymshark at a Glance (FY25)
| Metric | FY25 (year ended 31 July 2025) | FY24 | Direction |
|---|---|---|---|
| Revenue | £646.0m | £607.3m | Up 6.4% |
| Pre-tax profit | £7.0m | £11.8m | Down 41% |
| Adjusted EBITDA | £53.3m | £51.7m | Up 3.1% |
| Gross margin | 62.3% | Not disclosed | Down from 70.2% in FY21 |
| Pre-tax margin (calculated) | 1.1% | 1.9% | Fourth consecutive decline |
| Cash | £37m | Not disclosed | Positive, no debt drama |
| Inventory | £117m | Not disclosed | Roughly 18% of revenue |
| Dividends | None declared | None | Everything reinvested |
| Consecutive growth years | 13 | 12 | Unbroken |
The Financial Picture Nobody Puts in a SWOT
Before the four buckets, look at the shape of the last five years. This is the context every strength and weakness below sits inside.
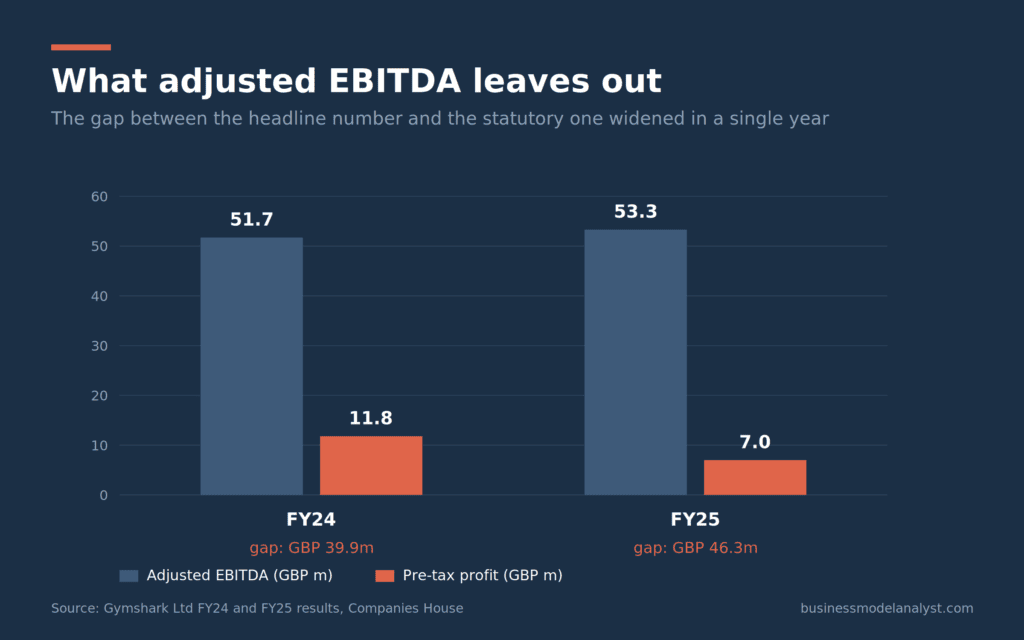
Revenue is up 61% over four years. Pre-tax profit is down 85%. That is not a wobble, it is a trend with four consecutive data points, and it is the single most important fact about Gymshark’s competitive position right now.
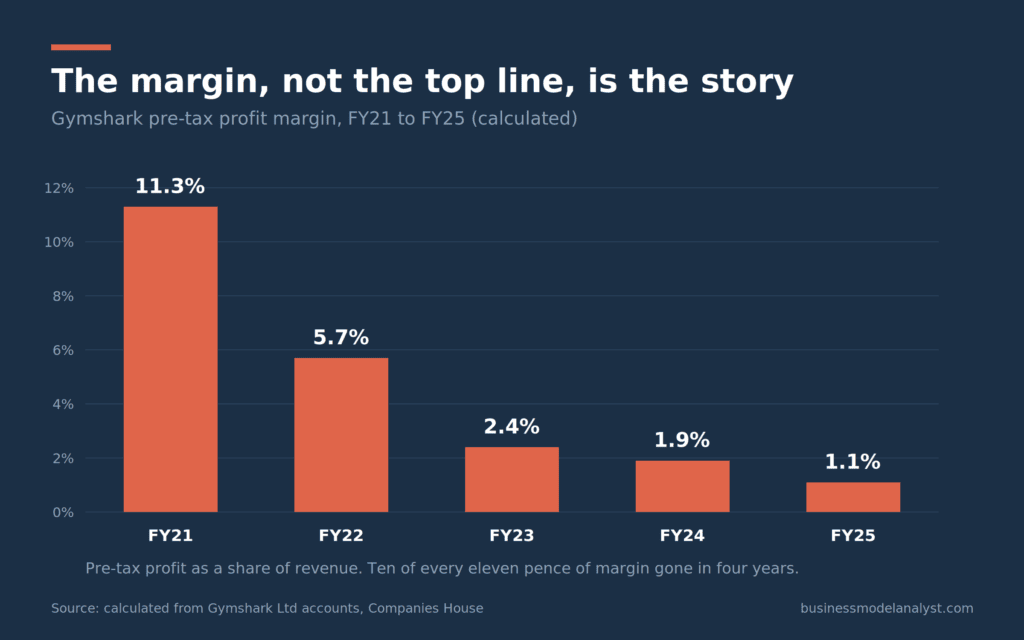
Information gain: the pre-tax margin figures above do not appear in the company’s announcements or in any of the trade coverage. They are calculated from the filed revenue and pre-tax profit lines. Ten of every eleven pence of pre-tax margin has gone in four years. In FY21 Gymshark kept 11.3 pence of every pound of revenue before tax. In FY25 it kept 1.1 pence.
Ben Francis has been direct about why, and it is worth quoting him rather than paraphrasing: “Our profits are lower than they have been in previous years, but this is intentional. We are really investing in the long-term of our brand.”
That is a defensible answer. It is also a claim that gets harder to make in year four than in year one, because at some point deliberate investment and structural margin compression look identical in the accounts.
The gap between the headline number and the statutory one
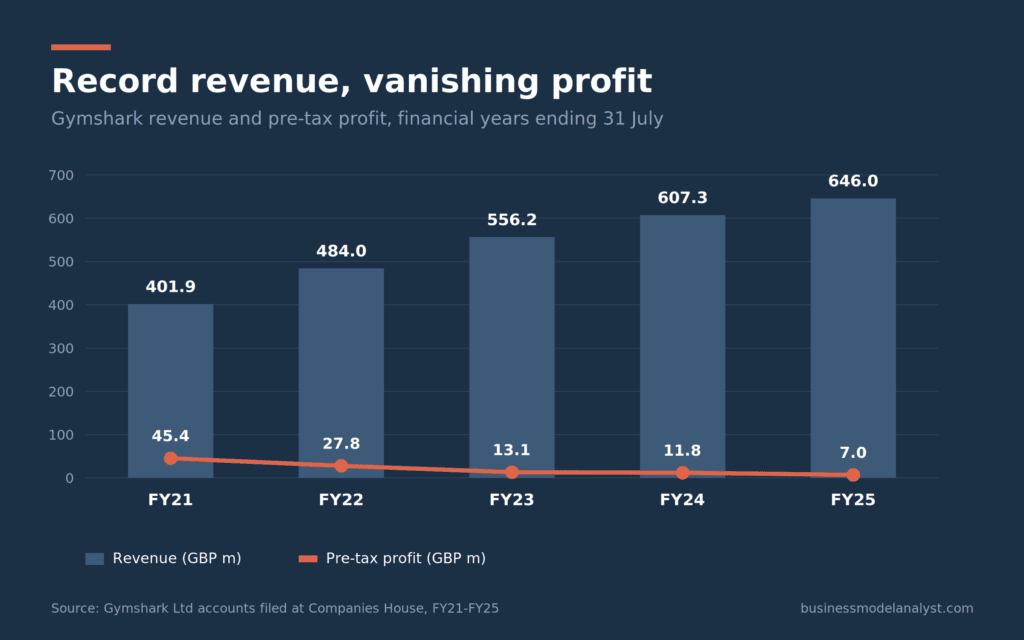
Gymshark leads its results with adjusted EBITDA, which grew to £53.3 million in FY25 from £51.7 million in FY24. Both numbers sound fine. The distance between them and pre-tax profit does not.
| Financial year | Adjusted EBITDA | Pre-tax profit | Gap |
|---|---|---|---|
| FY24 | £51.7m | £11.8m | £39.9m |
| FY25 | £53.3m | £7.0m | £46.3m |
Information gain: that gap widened by £6.4 million in a single year, on revenue growth of £38.7 million. Depreciation, amortisation, interest, and whatever sits inside “adjusted” absorbed a growing share of the business faster than the business grew. When a company opens flagship stores, it books lease liabilities and depreciates fit-outs, and both of those land below the EBITDA line. The widening gap is what the omnichannel pivot looks like in accounting terms.
Gymshark Strengths
1. A gross margin most apparel brands would take
At 62.3%, Gymshark’s gross margin remains high for the category. The brand still commands price without the wholesale discount structure that erodes most apparel economics. That margin is what funds everything else, and it is the reason the profit decline is a cost-side story rather than a pricing-power story.
Worth noting: gross margin has come down, from 70.2% in FY21 to 65.1% in FY22 to 62.3% in FY25. Still strong. No longer exceptional.
2. Thirteen straight years of revenue growth
Very few consumer brands compound for thirteen years without a down year. Gymshark has grown through a pandemic boom, a post-pandemic hangover, an inflation spike, and a category slowdown that has bruised much larger competitors. Whatever else is true, demand has never been the problem.
3. Ownership structure and the absence of a public market
Ben Francis holds more than 70% of the company. There is no quarterly earnings call, no analyst consensus to miss, and no share price to defend. A listed company with a pre-tax margin falling from 11.3% to 1.1% over four years would be under enormous pressure to stop investing. Gymshark is not. This is a genuine strategic asset and it is routinely left out of SWOT analyses because it does not look like a “strength” in the usual sense.
4. A community and creator engine competitors cannot buy
Gymshark’s athlete and creator model built the brand before paid media was a meaningful line item, and it remains the cheapest customer acquisition asset in the business. This is covered in depth in our Gymshark marketing strategy analysis, which is the better place to go for how the machine actually works. For SWOT purposes, the point is narrower: it is a durable, hard-to-copy strength that shows up in the gross margin rather than in a marketing line.
5. A clean balance sheet
£37 million of cash, no dividends declared, and everything reinvested. Gymshark is funding its transformation out of operations rather than out of leverage. In a category where several DTC peers have raised at valuations they now need to grow into, that matters.
Gymshark Weaknesses
1. A pre-tax margin of 1.1%
This is the headline weakness and everything else follows from it. At 1.1%, a modest cost shock, a bad season, or a single tariff change wipes out the profit line entirely. The business has almost no absorptive capacity left at the pre-tax level, which constrains how aggressively it can respond to anything.
2. Profit has fallen four years running
One down year is investment. Four is a pattern. Each year the “this is intentional” framing has to carry more weight, and the FY26 accounts, covering the year to 31 July 2026, will be the first to include a full year of the New York flagship, the Roosevelt Field store, and the German concessions. Those are the costs. The revenue from them is unproven.
3. The FY25 restructure said something the results did not
On 30 April 2025, Gymshark put 296 roles at risk, close to a third of its workforce, while simultaneously creating 168 new ones. The company framed it as a response to “intense macro-economic volatility” and said it aimed to redeploy affected staff into the new roles.
The timing is the tell. That announcement came weeks after the company reported record FY24 revenue. A business genuinely comfortable with a deliberate investment phase does not restructure a third of its workforce in the middle of it. The restructure was a cost-base correction, and it happened because the cost base had outrun the margin.
4. Retail leases converted variable cost into fixed cost
A 13,000 square foot Bond Street flagship in NoHo, a permanent store at Roosevelt Field, plus Dubai, Manchester, Amsterdam and London. Every one of those is a multi-year lease obligation that does not flex when a season goes soft. Gymshark spent a decade building a business with almost no fixed physical cost and has spent the last three years adding it back on purpose.
5. Single-category concentration
Gymshark sells gym apparel. It does not sell footwear at scale, it does not sell equipment, and until summer 2026 it did not sell access to anything. Compared with Nike, Lululemon or even Alo, the revenue base is narrow, which means a category-level slowdown hits Gymshark with no offset.
Gymshark Opportunities
1. Wholesale, which was a weakness in every previous SWOT
On 28 October 2025, Gymshark named Dick’s Sporting Goods its first US wholesale partner, launching the Power and Vital collections at 12 House of Sport locations across New Jersey, Pennsylvania, Ohio, Florida, Arizona, Texas, Minnesota, Tennessee, Massachusetts and Georgia, priced from $16 to $70.
Mitch Healey, Gymshark’s director of retail and wholesale in North America, framed the partner selection this way: “When we started to look for our first wholesale partner in North America, there were two things we knew we had to have in common, that they were an iconic brand and that they would be able to bring the authentic Gymshark experience to their community.”
Twelve doors is a pilot, not a rollout. But it establishes a channel that costs Gymshark no leases and no staff, and it puts the product in front of shoppers who will never visit gymshark.com. In a business with a 1.1% pre-tax margin, a channel with someone else’s fixed costs is genuinely valuable.
Germany followed the same logic. Gymshark entered German physical retail through concessions rather than owned stores: 150 square metres at Engelhorn in Mannheim from 19 February 2026, and roughly 100 square metres inside Breuninger’s sports department in Stuttgart. Gymshark had sold in Germany online only since 2022. Chief Brand Officer Noel Mack tied it to category momentum: “More and more people are discovering sports for themselves, whether it’s strength training, running, or hybrid training.”
2. Gyms as an owned revenue line
Gymshark Lifting Club, the company’s first public gym, is opening in Miami’s Wynwood district. This is the most interesting strategic move in the file, because it is the first time Gymshark has attempted to monetise its community directly rather than through apparel.
It is also the highest-risk one. Gyms are a real estate business with terrible unit economics for anyone who is not very good at real estate, and Gymshark has no operating history in it. Treated as a brand asset it makes sense. Treated as a revenue line it needs evidence.
3. The founder buyback
The Financial Times reported on 3 July 2026 that Ben Francis is in talks to buy back part of General Atlantic’s 21% stake. Terms and valuation are reportedly still under discussion, and the report indicates Francis is pursuing part of the holding rather than all of it.
If it closes, it does two things. It concentrates control further with the founder, and it puts a fresh, negotiated valuation on the business, which is useful information in a company that does not otherwise mark itself to market.
4. Category adjacencies
Womenswear, hybrid training, and the price architecture above $70 are all underexploited. Gymshark’s Dick’s assortment tops out at $70, which is well below where Lululemon and Alo sell. There is room above.
Gymshark Threats
1. Tariffs, and specifically the wrong tariff line
This is the most concrete near-term threat and it is barely covered in Gymshark analysis anywhere.
From 25 July 2026, US tariffs on Vietnamese apparel are set at 12.5%, the same rate as China. Bangladesh, Cambodia, Indonesia and Malaysia face 10%. Vietnam is also excluded from a new textile mechanism that lets competing suppliers access reduced or zero tariffs on eligible apparel through a quota tied to US cotton and textile purchases. Vietnam overtook China as the largest apparel exporter to the US, so this is not a marginal sourcing lane.
Gymshark has confirmed that around 50% of its business comes from US customers. A 2.5 percentage point sourcing disadvantage against rivals producing in Bangladesh or Cambodia is not fatal to a brand with a 62.3% gross margin. It is potentially fatal to a 1.1% pre-tax margin.
2. A competitive set that got much better funded
Vuori was valued at $5.5 billion in an $825 million investment led by General Atlantic and Stripes. Alo Yoga has scaled into a genuine global competitor. Nike and Skims launched NikeSKIMS in 2025 and put institutional weight behind women’s activewear specifically.
There is a detail here worth sitting with. General Atlantic holds 21% of Gymshark and led the round that valued Vuori at $5.5 billion. The same investor sits on both sides of the trade. That does not imply anything improper, but it does frame the buyback story differently: a founder negotiating to buy back stock from an investor with a well-capitalised position in a direct competitor is not a purely financial negotiation.
For the wider field, see our breakdown of Lululemon competitors and alternatives.
3. Geographic concentration
Roughly half of revenue from one country, and that country is the one applying the tariffs and hosting the best-funded competitors. The German and wider European push is a partial hedge, but it is early.
4. Fixed costs meeting a soft category
The retail estate was committed during a period when Gymshark expected the category to keep expanding. Leases do not renegotiate on demand. If activewear demand stays soft through FY27, the fixed cost base built in FY25 and FY26 lands on a smaller revenue line than it was underwritten against.
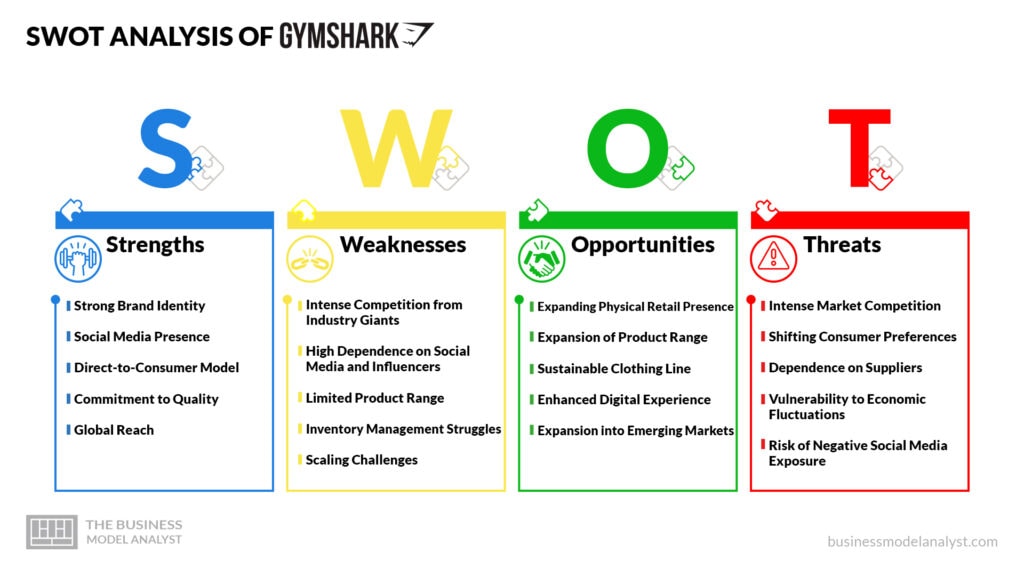
Gymshark SWOT Analysis Matrix
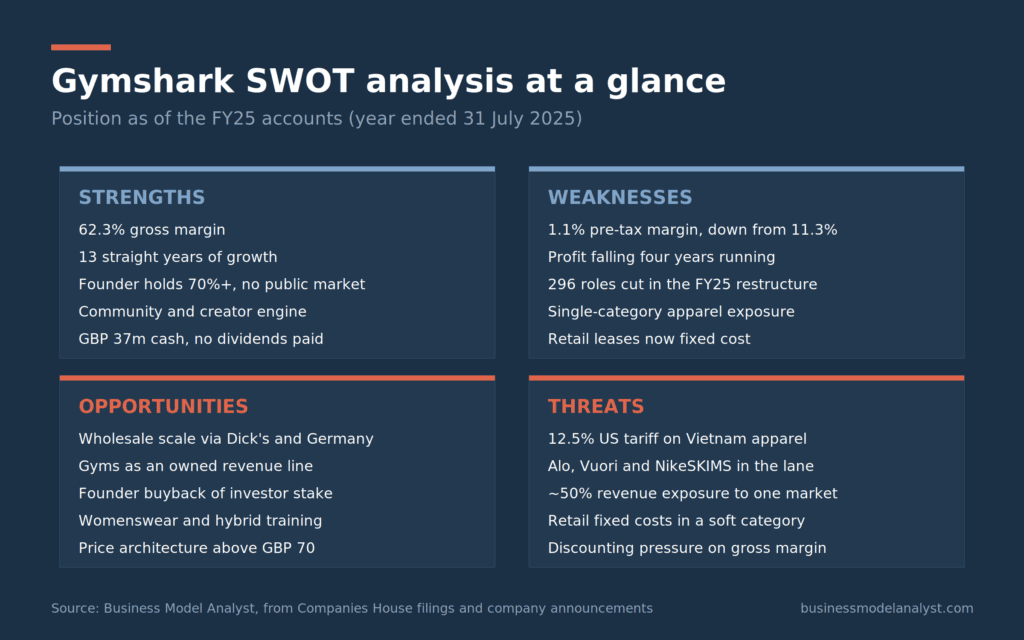
The Channel Shift, Year by Year
The SWOT above only makes sense against the timeline. Gymshark did not drift into omnichannel, it committed to it in a compressed window.
| Period | Channel move | What it changed |
|---|---|---|
| 2012 to 2019 | Online only, expo pop-ups | Pure DTC, near-zero fixed cost |
| 2022 | Regent Street London flagship, US distribution centre | First major fixed-cost commitments |
| 2024 to 2025 | Dubai, Manchester, Amsterdam stores | Retail estate becomes a real cost line |
| Oct 2025 | Roosevelt Field, Long Island | First permanent US store |
| Oct 2025 | Dick’s Sporting Goods, 12 doors | First US wholesale, first third-party channel |
| Dec 2025 | Bond Street NoHo flagship, 13,000 sq ft | Largest single US commitment |
| Feb 2026 | Engelhorn Mannheim, Breuninger Stuttgart | European wholesale concession model |
| Summer 2026 | Gymshark Lifting Club, Wynwood Miami | First non-apparel revenue line |
Any SWOT that still lists “expanding physical retail presence” as an untapped opportunity is describing a company that stopped existing around 2021. The expansion happened. The question now is whether it pays.
What This SWOT Actually Says
Strip away the framework and the position reduces to one sentence: Gymshark traded margin for reach, and the reach has not yet produced the margin back.
That is not automatically a bad trade. DTC-only was becoming a worse business for everyone as customer acquisition costs rose and the channel lost its novelty. Wholesale and physical retail put product in front of people who will never see an Instagram ad, and the Dick’s and German deals do it using someone else’s fixed costs, which is the smart version of the move. The Miami gym is a real attempt to build something competitors cannot copy quickly.
The risk is one of sequencing. Gymshark added the fixed costs first and is looking for the payoff second, in a category that softened and under a tariff regime that specifically disadvantages its manufacturing base. It is doing that with 1.1 pence of pre-tax margin per pound of revenue as the buffer.
Two things would change the read materially. First, the FY26 accounts, covering the year to 31 July 2026, which will be the first to carry a full year of the new retail estate. If the pre-tax margin stabilises there, the investment thesis holds. If it goes negative, the restructure of April 2025 was the first correction rather than the only one. Second, the buyback. Whatever valuation Francis and General Atlantic settle on is the most honest price signal this company will produce.
For how the money actually moves through the business, see the Gymshark business model breakdown. For the demand side, the Gymshark marketing strategy analysis covers the community machine in detail.
Frequently Asked Questions
What is Gymshark’s revenue? Gymshark reported revenue of £646 million for FY25, the financial year ended 31 July 2025, up 6.4% on FY24’s £607.3 million. It was the company’s thirteenth consecutive year of revenue growth.
Is Gymshark profitable? Yes, but barely at the pre-tax level. Gymshark reported pre-tax profit of £7 million in FY25, down from £11.8 million in FY24. That is a pre-tax margin of about 1.1%, calculated from the filed figures. Adjusted EBITDA was £53.3 million.
Why is Gymshark’s profit falling? Founder and CEO Ben Francis has described the decline as intentional, tied to long-term brand investment. Structurally, the drivers are the shift into physical retail and its associated lease and depreciation costs, international expansion, and a gross margin that has fallen from 70.2% in FY21 to 62.3% in FY25.
Who owns Gymshark? Ben Francis holds more than 70%. General Atlantic holds 21%, acquired in August 2020 in a deal valuing the company above £1 billion. The Financial Times reported in July 2026 that Francis is in talks to buy back part of General Atlantic’s holding.
What are Gymshark’s biggest strengths? A 62.3% gross margin, thirteen unbroken years of revenue growth, founder control with no public market pressure, a community and creator acquisition engine competitors cannot easily replicate, and £37 million of cash with no dividends drawn.
What are Gymshark’s biggest weaknesses? A pre-tax margin of 1.1%, four consecutive years of falling pre-tax profit, a restructure in April 2025 that put 296 roles at risk, single-category concentration in apparel, and a retail estate that converted variable costs into fixed lease obligations.
Who are Gymshark’s main competitors? Nike, Lululemon, Under Armour, Alo Yoga, Vuori, and since 2025 the NikeSKIMS joint venture. Vuori was valued at $5.5 billion in a round led by General Atlantic and Stripes, which is notable given General Atlantic’s 21% Gymshark stake.
Does Gymshark sell in physical stores? Yes. Gymshark operates owned stores including a 13,000 square foot Bond Street flagship in NoHo, New York, plus locations in London, Dubai, Manchester, Amsterdam and Roosevelt Field on Long Island. It also sells wholesale through 12 Dick’s Sporting Goods House of Sport locations in the US and through concessions at Engelhorn in Mannheim and Breuninger in Stuttgart.
What is the biggest threat to Gymshark? Tariffs are the most immediate. From 25 July 2026 US tariffs on Vietnamese apparel are set at 12.5%, against 10% for Bangladesh, Cambodia, Indonesia and Malaysia, and Vietnam is excluded from the textile mechanism offering reduced rates. With roughly half of Gymshark’s business coming from US customers and a 1.1% pre-tax margin, a sourcing cost disadvantage of that size is material.
The Business Model Analyst Take
Gymshark’s SWOT looks worse than Gymshark does, and that is worth saying plainly.
The company is growing, the brand is intact, the balance sheet is clean, and the founder controls it outright. Almost no consumer business gets thirteen straight growth years. Those are not the fundamentals of a company in trouble.
But a SWOT is about position, not health, and the position has narrowed considerably. Gymshark deliberately spent its margin buying a second and third channel, and it did so on a compressed timeline that put most of the cost into FY25 and FY26 while the payoff sits in FY27 and beyond. That would be a comfortable bet with 11% pre-tax margins. It is a tight one with 1.1%.
The most instructive detail in the whole file is not in the accounts. It is that General Atlantic owns a fifth of Gymshark and led the round valuing Vuori at $5.5 billion. Read alongside the reported buyback talks, that tells you something the SWOT framework will not: the capital that funded the DTC generation has already moved on to backing several horses in the same race, and founder control is only free while somebody else is happy to hold the other 21%.
Gymshark’s next two years are not about whether the brand works. They are about whether the version of the business that carries leases, wholesale terms and a gym can earn a margin the online-only version used to earn without trying.


