
Grady-White’s owner gave the boat maker away instead of banking the exit. The ownership structure he used is spreading fast, and a quirk in the tax code explains why he had to use it.
Eddie Smith Jr., 83, had multiple offers around $400 million for Grady-White Boats. He took none of them. Instead he moved the voting stock into a perpetual purpose trust and the economic stock into a 501(c)(4) nonprofit, which locks the company against any future sale and routes its profits to charity. He gets no sale proceeds and no charitable deduction, and he expects a multimillion-dollar tax bill for the privilege.
Most founders think they have two exits: sell to a buyer, or hand it to the kids. Smith had neither option left. His only son died in 2021, a year after his wife. So he called an investment banker, ran a process, got real offers, and walked away from every one of them because he did not trust a private equity buyer to keep the profit-sharing plan and the on-site clinic that 350 people in Greenville, North Carolina depend on.
What he did next is the part worth studying, because the legal machinery he used has a specific logic to it. Nothing about it is charity in the ordinary sense.
What Happened
Smith transferred Grady-White’s voting stock, a small slice of total shares, into a perpetual purpose trust. That trust holds those shares forever. It has no beneficiaries who can cash out, no shareholders to please, and no mechanism by which anyone can sell the company. Grady-White is now structurally unsellable.
The rest of the shares, the non-voting ones that carry the economics, went to a newly formed 501(c)(4) nonprofit. Independent boards run both entities. Smith sits on neither. He stays on as chief executive emeritus and draws a salary.
Grady-White will keep operating as a for-profit manufacturer and keep paying corporate tax. Profits not reinvested in the business, described as tens of millions a year, flow to the nonprofit, which grants them out to conservation, health care and education causes.
Smith was blunt about the economics for himself. <a href=”https://www.nytimes.com/2026/07/25/business/grady-white-boats-charity.html” rel=”nofollow”>Speaking to The New York Times</a>, he said he is getting no benefit, “tax or otherwise.”
The Backstory
Smith bought Grady-White in 1968 when he was 26. The company was building wooden boats in a run-down tobacco warehouse and losing money. Don White, a co-founder, was preparing to close it. Smith’s accountant advised against the purchase. His father lent him the money anyway.
He worked 100-hour weeks for several years. Sales turned by the mid-1970s, and the company has been profitable for 50 straight years since. Revenue now runs in the hundreds of millions. Smith never took an outside investor and never sold a share to the public, which is the detail that made this whole transfer possible. A founder with a cap table full of VCs or a PE minority stake cannot do what Smith did, because those investors have a contractual right to an exit.
The template came from Patagonia. Yvon Chouinard ran the same play in 2022, splitting voting stock into the Patagonia Purpose Trust and economic stock into the Holdfast Collective, a 501(c)(4). If you want the full mechanics of that structure, our breakdown of who owns Patagonia walks through the two-entity split in detail.
Smith hired Natalie Reitman-White of Purpose Owned, the consultancy that helped structure the Grady-White deal, after learning what Chouinard had done. Reitman-White says Grady-White is the largest transaction of its kind since Patagonia.
The Plan
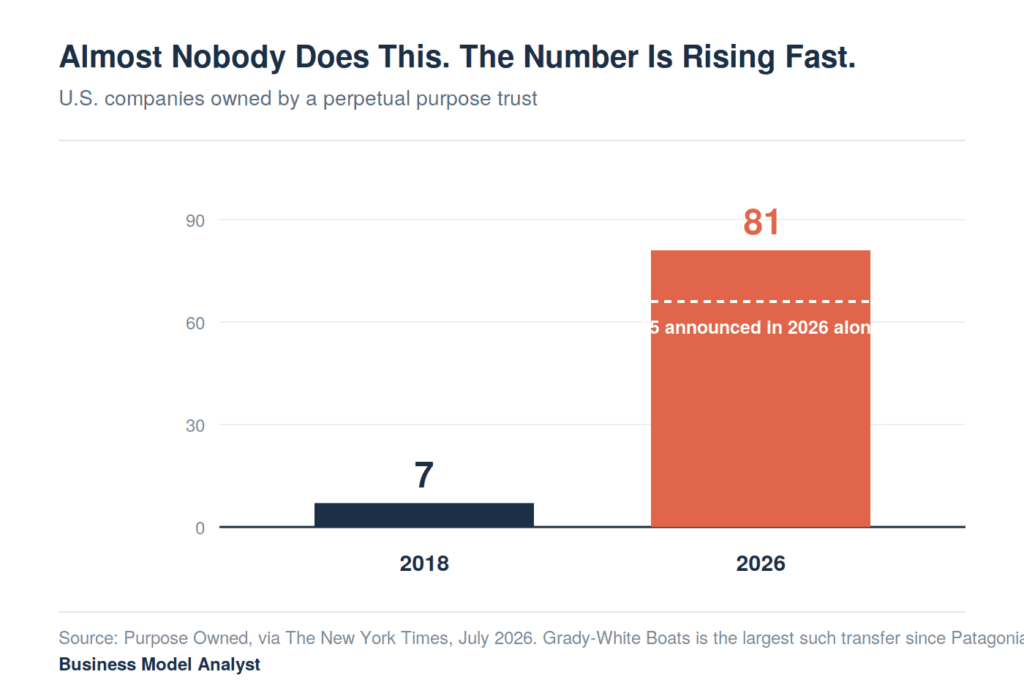
The count of U.S. companies owned by a perpetual purpose trust sat at seven in 2018. It stands at 81 today, with 15 of those announced this year.
That is a rounding error against the roughly 6,411 U.S. companies with an employee stock ownership plan, and a speck against the six million boomer-owned businesses McKinsey expects to change hands by 2035. But the growth curve is what the succession advisory industry is watching, because the standard exit menu fails a specific and common owner profile: profitable company, culture that depends on benefits a buyer would cut, no heir who wants the job, and an owner who cares more about year 50 than about the check.
For that owner, a sale converts a durable institution into cash and a new capital structure. An ESOP keeps the company independent but loads it with acquisition debt and gives employees a claim they can eventually monetize. The purpose trust removes the sale option permanently and hands governance to a board bound by a written charter.
The Business Model Angle
The interesting question is not why Smith gave the company away. It is why he used a 501(c)(4), which is a legal vehicle better known for funding political advertising than for owning boat factories.
The answer sits in the tax code, and no mainstream coverage of either Patagonia or Grady-White has said it plainly.
A 501(c)(3) private foundation cannot hold a whole operating company. The excess business holdings rule caps what a foundation and its insiders can own in a single business, generally at 20%, and forces divestiture beyond that. Donate Grady-White to your family foundation and the foundation has to sell most of it, which produces the exact outcome Smith paid millions to avoid.
A 501(c)(4) has no such cap. It can own 100% of an operating business indefinitely. Congress also removed gift tax on transfers to 501(c)(4) organizations in 2015, so the economic shares move across for free. The catch is that donors to a (c)(4) get no charitable income-tax deduction at all. Chouinard got zero deduction on 98% of Patagonia and still owed roughly $17.5 million in gift tax on the voting shares he put into the purpose trust, because that trust is not a tax-exempt entity.
Smith’s structure produces the same math, which is why his “no benefit, tax or otherwise” line checks out. He is not describing modesty. He is describing the only legal path that keeps a company intact, independent and giving.
Three design principles fall out of this for any founder looking at the same problem:
Separate control from economics before you separate yourself from either. The voting stock and the profit stock go to different entities with different jobs. The trust protects the charter. The nonprofit spends the money. Neither can override the other.
A charter beats a promise. Smith’s benefits package survives him because a legal document requires it, not because a successor CEO admires him. IKEA runs the same logic through two foundations with no beneficial owners, which is why nobody can buy it. Our IKEA organizational structure analysis shows how that ownership split works across a $50 billion retail system.
The structure only works if the company throws off cash. No investor is ever coming. Retained earnings and debt are the entire capital stack, forever.
The Risk
That last point is where this gets uncomfortable, and it is a harder test for Grady-White than it was for Patagonia.
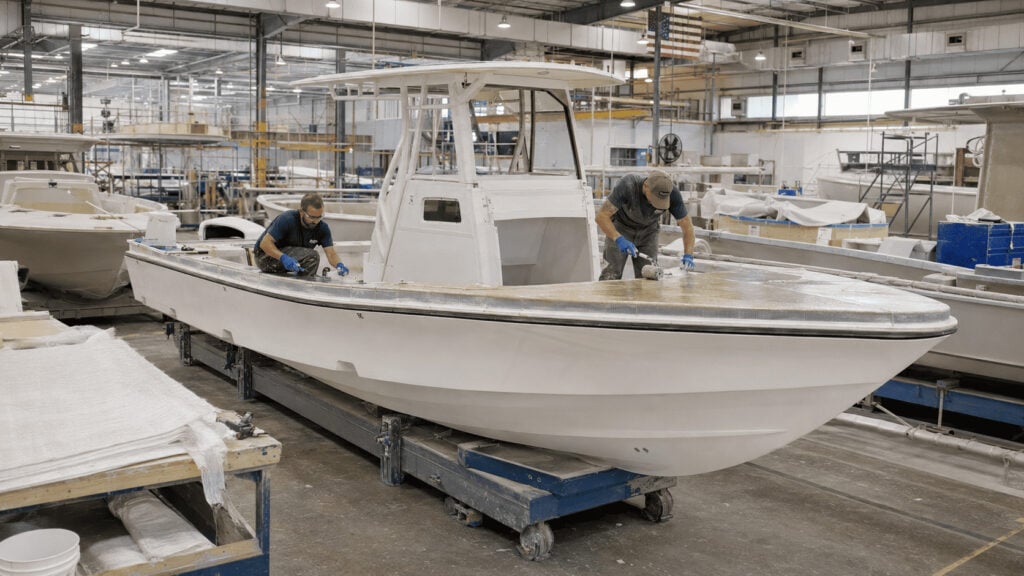
Patagonia sells high-margin apparel with a repair-and-resale flywheel and a brand that carries pricing power through downturns. Grady-White builds fiberglass offshore fishing boats, a big-ticket discretionary purchase financed at retail. When rates rise and confidence drops, that demand does not soften. It stops.
It is stopping right now. U.S. new powerboat retail unit sales fell 8.8% in 2025 to about 215,000 units, down from 236,000 the year before, according to the National Marine Manufacturers Association. Saltwater fishing boats, Grady-White’s segment, fell 8.6% on a rolling 12-month basis through January 2026. Smith locked a permanently unsellable ownership structure onto a cyclical manufacturer in the third year of a segment downturn.
A public company facing that raises equity. A PE-backed company gets a sponsor check. Grady-White has neither door. If a multi-year slump eats the profit distribution, the nonprofit’s grants shrink and the profit-sharing plan comes under pressure, and the only remaining lever is cutting the benefits the whole structure exists to protect.
There is a governance question too. The 501(c)(4) form permits unlimited political spending, which is a large part of why founders pick it. Smith donates to Republican candidates personally and said he does not want Grady-White’s profits going to political causes. Nothing in the legal form enforces that. The only thing standing between the charitable mandate and a different use of the money is the composition of an independent board that Smith will not sit on and will not outlive. Patagonia’s Holdfast Collective already grants to advocacy work alongside conservation, which shows how wide the lane is.
Quick Questions
How much was Grady-White worth? Several offers came in around $400 million during the sale process Smith ran before changing course.
Does Grady-White still pay taxes? Yes. It remains a for-profit corporation paying corporate income tax. The nonprofit that receives its distributed profits is the tax-exempt piece.
Can the trust ever sell the company? No. The perpetual purpose trust holds the voting stock forever with no beneficiaries who can force a liquidity event. That permanence is the point of the structure.
Did Smith avoid a tax bill? He avoided capital gains he would have owed on a $400 million sale, because he never sold. He also gets no charitable deduction and expects to owe millions in gift tax on the shares going into the trust.
Who runs Grady-White now? Independent boards govern the trust and the nonprofit. Smith holds the title of chief executive emeritus and takes a salary.
How many companies use this structure? 81 in the United States as of 2026, up from seven in 2018.
The Business Model Analyst Take
Coverage of this keeps reaching for the word sacrifice. That framing misses what Smith bought.
He spent $400 million of theoretical proceeds and a real tax bill to purchase one thing the open market does not sell: a guarantee that the company he spent 58 years building will still be Grady-White in 2075. No buyer offers that. No LOI includes it. Every acquirer says the culture matters right up until the first bad quarter.
The reason this deserves attention has nothing to do with generosity. Six million American business owners are heading for the exit over the next decade, most of them with no succession plan and no heir who wants the company. The default outcomes are a PE roll-up, a strategic buyer who moves production, or a quiet shutdown. Fewer than a third of those owners have any plan at all.
The purpose trust is a third door, and 81 companies is a small enough number that it still counts as an experiment rather than a trend. What makes it worth watching is that the constraint driving it is legal rather than moral. Founders are not choosing (c)(4) structures because they love social welfare organizations. They are choosing them because the foundation rules make the obvious option impossible.
The stress test arrives on the next downturn, not this one. A steward-owned company that cannot raise equity has to earn its independence every single year. Patagonia has not yet had to prove that. Grady-White, staring at a soft boat market with no outside capital available, might get there first. Watch whether the profit-sharing plan survives 2027 intact. That number will tell you more about whether this model works than any amount of coverage about a man who said no to $400 million.
For a look at how the same ownership structure holds up under commercial pressure, our Patagonia SWOT analysis examines whether the 2022 giveaway became a model others follow or a one-time act of conscience.