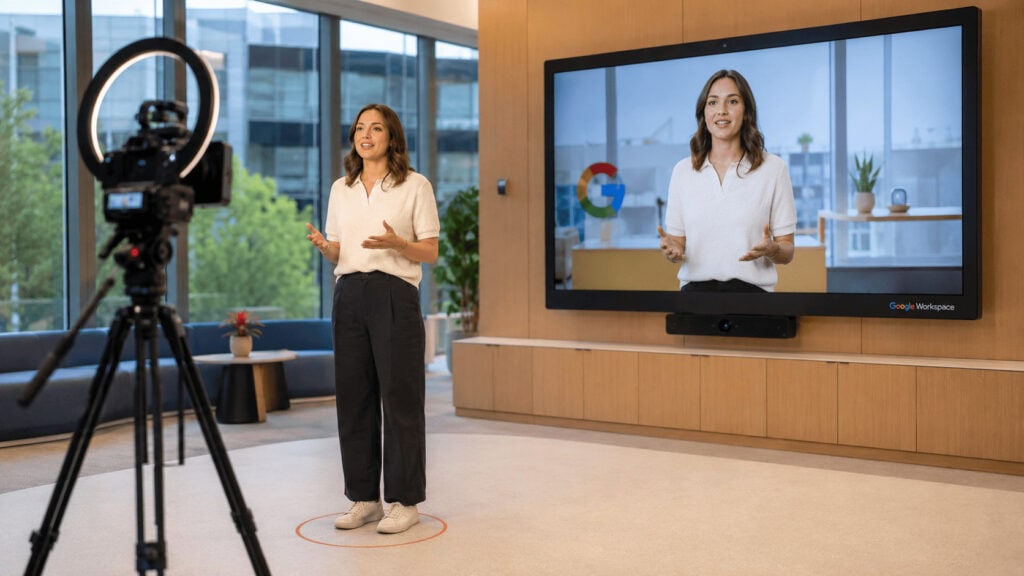

Google Vids can now turn a selfie into a talking digital you. That puts Google head-to-head with Synthesia, a startup its own venture arm valued at $4 billion six months ago.
On July 16, Google added personal AI avatars to Google Vids, letting anyone build a talking digital clone from a selfie and a voice clip. The feature drops Google straight into the enterprise AI video market led by Synthesia and HeyGen. The twist: Google Ventures led Synthesia’s $4 billion round in January.
There is a specific kind of awkward that happens when your landlord opens a shop next door selling exactly what you sell. That is roughly where Synthesia sits this week.
What Happened
Google announced that Google Vids, its AI video tool inside Google Workspace, now lets users create a custom digital avatar that looks and sounds like them, generated from an uploaded selfie and a voice recording. Google is also bringing Gemini Omni, its multi-modal model, into Vids, so users can build videos from a written prompt plus reference images, swap backgrounds, fix lighting, and make step-by-step edits without starting over.
Google is putting guardrails on the avatar feature. Each avatar is tied to the account holder’s likeness and Google account, watermarked invisibly with SynthID, and restricted to users aged 18 and up in select regions. That is a deliberate contrast to OpenAI’s Sora, the deepfake-friendly video app that shut down in March 2026.
The strategic read is simple. Vids started as an AI presentation helper bolted onto Workspace. With avatars and conversational editing, it becomes an all-in-one video platform, and it lands in the same market as HeyGen, Synthesia, Captions, and D-ID.
The Backstory
The AI avatar video category grew up fast and got expensive to compete in. Synthesia, founded in London in 2017, raised a $200 million Series E in January 2026 at a $4 billion valuation, nearly double its $2.1 billion mark a year earlier. It reports roughly $150 million in annual recurring revenue and says more than 90% of the Fortune 100 use its platform for training and internal communications.
HeyGen took the opposite path. The Los Angeles company hit around $200 million in ARR while raising only about $74 million total, staying cash-flow break-even and carrying a modest $500 million valuation. Between them, the two independents built a category worth hundreds of millions in recurring revenue by charging businesses $29 to $299 a month for synthetic presenters.
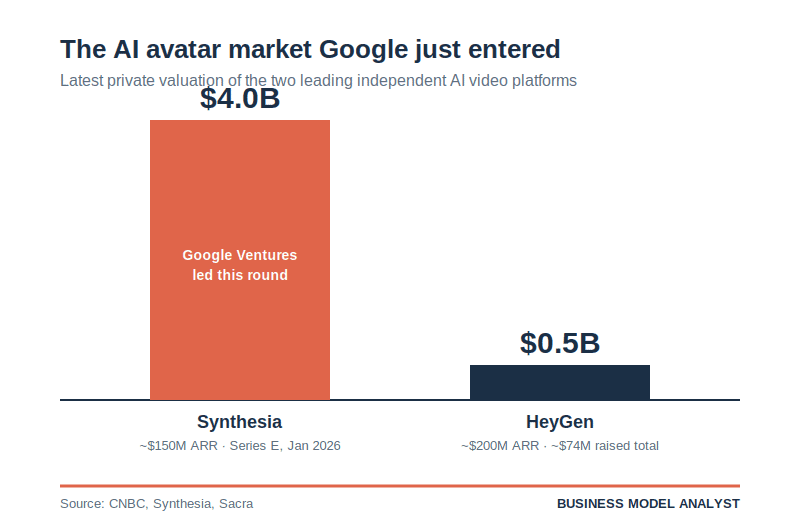
Here is the detail that makes this a business model story and not a product update. Google Ventures, Alphabet’s venture arm, led Synthesia’s $4 billion round. Google is now simultaneously an investor in the category leader and a direct competitor to it.
The Plan
Google is not trying to win this market by being the best avatar tool. It is trying to win it by being the default one.
Synthesia and HeyGen have to sell their product one enterprise contract at a time. Google can switch a feature on inside Workspace, which already sits on the desktops of billions of users and a large share of the businesses these startups are chasing. The pitch writes itself: you already pay for Workspace, so why buy a separate seat at Synthesia when Vids makes the company update video for free.
That is the classic platform-bundling playbook Google has run before, from Meet against Zoom to Workspace against Microsoft. It rarely produces the best standalone product. It reliably produces the one most people end up using because it is already there.
The Business Model Angle
Google does not make money selling Vids. Google makes money keeping you inside Google. Vids is a retention feature for Google Workspace, not a revenue line of its own, which means Google can afford to give away something Synthesia has to charge for to survive. When your core business is a $402.8 billion advertising and cloud machine, a video avatar tool is a moat-widener, not a P&L.
That asymmetry is the whole threat. Synthesia’s $4 billion valuation assumes it can keep charging enterprises premium prices for AI presenters. HeyGen’s lean model assumes the same demand at a lower price. Google bundling a good-enough version into a subscription businesses already own attacks the price both models depend on. You do not have to beat a startup’s product to damage its pricing power. You just have to make the category feel like a feature instead of a purchase.
The counter-case, and it is real, is that enterprise buyers do not pick tools on price alone. Synthesia’s value sits in 90%-of-the-Fortune-100 workflows, compliance, avatar libraries, and localization at scale, the boring integration depth that a bundled Workspace feature will not match for years. Google’s history of shipping and then quietly abandoning products does not help its enterprise credibility either. Bundling pressures the low end of a market. It does not automatically capture the high end.
The Risk
The near-term risk is not that Google kills Synthesia. It is margin compression across the category. Once “make a talking avatar” is a checkbox in Workspace, the standalone tools have to justify their subscriptions on depth, quality, and trust rather than on access to the capability itself. That is a harder, lower-margin sale.
For Google, the risk is reputational. Avatars are a deepfake vector, and the SynthID watermark plus likeness-locking is Google trying to avoid Sora’s fate. If a Google-made avatar is misused at scale, the blast radius touches the whole Workspace brand, not just one app. And there is the genuinely strange governance question of Google competing with a company its own venture arm helped value at $4 billion. Alphabet has run investor-and-competitor conflicts before, but rarely this directly, and rarely this fast after writing the check.
Quick Questions
Is Google Vids free? Vids is part of Google Workspace, so it is bundled into existing Workspace subscriptions rather than sold separately. Access to the personal avatar feature is limited to users 18 and older in select regions.
Does this kill Synthesia or HeyGen? Unlikely in the short term. Both have deep enterprise workflows Google will not match quickly. The bigger effect is pricing pressure as the basic avatar capability becomes a bundled feature rather than a standalone purchase.
Why did Google invest in Synthesia and then compete with it? Google Ventures operates as a financial investor, and Alphabet frequently backs companies in markets its product teams also enter. It creates an obvious conflict, but it is a familiar pattern for large platform companies.
What is Gemini Omni? Google’s multi-modal AI model that turns text, images, and audio into video. Inside Vids it powers prompt-to-video generation, background swaps, lighting fixes, and step-by-step editing.
The Business Model Analyst Take
The headline is “Google lets you star in AI videos.” The real story is a platform owner deciding a $350-million-ARR category is worth absorbing as a free feature. That is the move that should worry Synthesia and HeyGen far more than any single product spec.
This is the oldest pattern in Google’s playbook, and one of the reasons it keeps showing up in our Google SWOT analysis under both strengths and antitrust threats. Google wins adjacent markets not by building the best tool but by making its version the one already installed. Distribution beats features when the feature is good enough, and “good enough” is a low bar for an internal company update video.
The independents are not dead, but their pitch just got harder. “Buy our AI presenter” competes with “use the one you already have.” The winners in this category will be the tools that are so deep in enterprise workflows that bundling cannot touch them, and the losers will be everyone selling a capability that Google just turned into a checkbox. Watch Synthesia’s next enterprise renewal cycle. That is where you will see whether a $4 billion valuation survives its own lead investor becoming its competitor.