
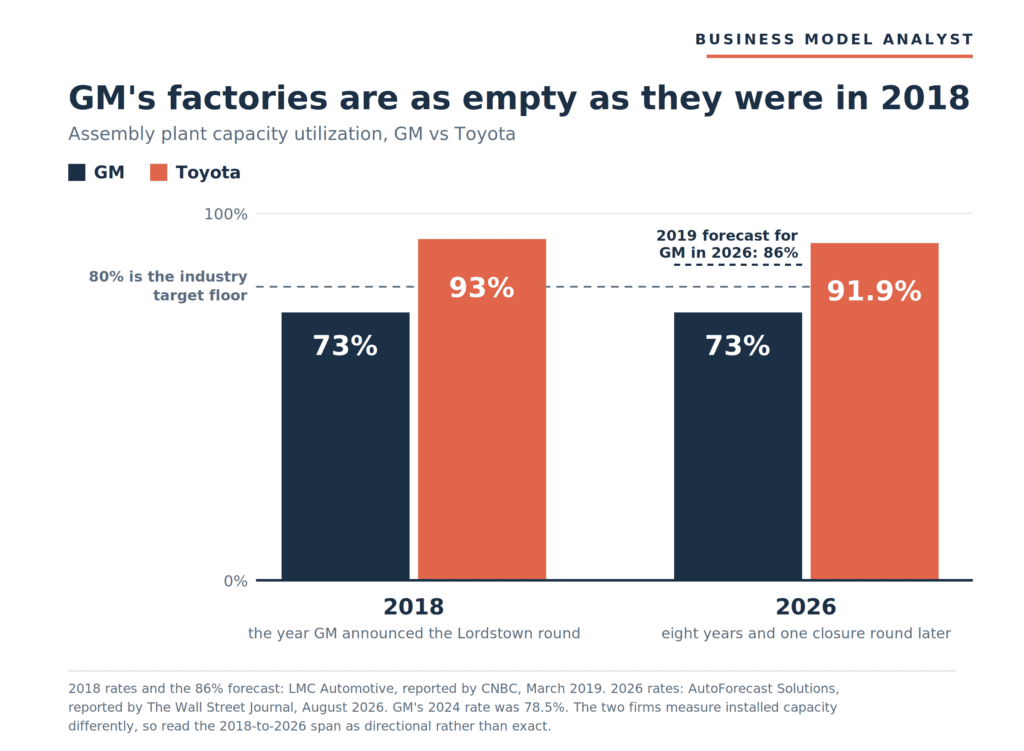
GM’s assembly plants run at 73% of capacity, the same rate that triggered the Lordstown closures in 2018. Toyota’s run at 91.9%. The sales race everyone is watching is the smaller of the two stories.
Toyota has cut GM’s US sales lead to just over 100,000 vehicles through July, and GM’s answer is that market share is only one measure of success. GM is right, and the numbers back it up: on its own 2026 guidance GM earns roughly $3,800 of adjusted operating profit per vehicle against Toyota’s forecast of about $2,000. The trouble sits one level below that. GM raised margins by removing losses rather than by filling factories, and its capacity utilization has not improved since 2018.
Michigan Governor Gretchen Whitmer put on a safety vest this week and cut the ribbon on a battery plant in Lansing. GM built that plant. GM also sold it. The cells coming off the line now go to Toyota.
What Happened
The Lansing site started life in January 2022 as the third factory of Ultium Cells, the GM and LG Energy Solution joint venture meant to carry GM’s $35 billion push toward 30 electric models. GM announced in December 2024 that it would sell its roughly $1 billion stake. LG bought the assets outright and kept building. In February 2025 Toyota agreed to move an existing $1.5 billion battery order to the site. Michigan transferred the $186 million in state and local incentives from GM to LG.
The plant that opened this week runs three product lines GM does not have. It builds nickel-manganese-cobalt cells for Toyota, including the 2027 three-row Highlander EV that Toyota assembles in Georgetown, Kentucky. It builds lithium iron phosphate cells for grid storage. From 2027 Tesla takes prismatic LFP cells from the same building for its Megapack line. LG has put more than $2 billion into the 226-acre site, employs about 900 people there today and expects roughly 1,700 at full run.
The sales picture behind the ribbon-cutting: GM sold 1,338,976 vehicles in the US in the first half of 2026, down 6.9%, for 16.9% of the market. Toyota sold 1,243,389, up 1.4%, for 15.7%. Buick and Cadillac each fell more than 20%. Cox Automotive economist Charlie Chesbrough, who has been telling reporters since June that Toyota could take the top spot by year end, points out that GM would already be second if the redesigned RAV4 were not in short supply.
GM’s financials are moving the other way. Second-quarter revenue came in at $48.03 billion on 990,000 wholesale units, with EBIT-adjusted of $3.94 billion, up 29.8%, at an 8.2% margin against 6.4% a year earlier. North America hit 8.6%. Average transaction price reached $52,000. GM raised full-year guidance for the second time, to $14 billion to $16 billion of EBIT-adjusted. The stock trades at record highs.
The Backstory
GM has run this play before, and the scoreboard has not moved.
In 2018, GM’s North American capacity utilization sat at 73%, the worst among the big automakers, according to LMC Automotive. Ford was at 82%, Fiat Chrysler at 90%, Honda at 91%, Toyota at 93%. GM responded with the closure round that killed Lordstown, along with Oshawa, Warren Transmission and Baltimore. LMC’s Jeff Schuster forecast at the time that GM would climb back to roughly 86% by 2026.
Eight years and one closure round later, AutoForecast Solutions puts GM at 73%. Toyota is at 91.9%. Automakers generally aim for 80% to 85%. GM was at 78.5% as recently as 2024 and has given the improvement back.
The two firms measure installed capacity differently, so the span deserves a caveat. The direction does not. GM shut plants, sold battery joint ventures, walked away from robotaxis, Europe and India, killed its sedans, and arrived back at the number that started the process.
The Plan
GM says utilization improves from here. The company committed $4 billion in June 2025 to move production of the Chevrolet Equinox and Blazer out of Mexico and into Fairfax, Kansas and Spring Hill, Tennessee, and to convert Orion Assembly to gas-powered full-size SUVs and light-duty pickups from early 2027. Barra’s target is more than two million US-built vehicles a year. A separate $888 million goes into Tonawanda for sixth-generation V-8s. Capital spending guidance runs $10 billion to $12 billion, including battery joint ventures.
Toyota is spending on a different axis. It operates 11 US plants, employs about 50,000 people here and has invested close to $60 billion since it started building in America. Its $13.9 billion battery plant in Liberty, North Carolina opened in November 2025, its first outside Japan, with up to 5,100 jobs. Toyota committed up to $10 billion more over five years the same day. In March 2026 it put $1 billion into Kentucky and Indiana, $800 million of it at Georgetown to prepare for battery-electric production while raising Camry and RAV4 output.
Read the two plans side by side and the difference is what each dollar buys. GM’s $4 billion relocates vehicles it already sells across a border to dodge tariffs. Toyota’s spending adds units in categories GM exited.
The Business Model Angle
There are two ways to raise profit per vehicle. Lift the price, or spread the fixed cost across more vehicles. GM has been doing the first for a decade and has stopped doing the second.
The first one worked. GM’s 2026 guidance implies an adjusted operating margin near 8% on revenue of roughly $190 billion. Toyota forecasts ¥3.4 trillion of operating income on ¥54 trillion of revenue, which is 6.3%. Per unit, GM guides to about $3,800 of adjusted operating profit on roughly four million wholesale vehicles, while Toyota’s ¥3.4 trillion across 10.5 million consolidated vehicles works out to about $2,000 at Toyota’s own ¥160 assumption. Mary Barra won the per-car argument.
Two caveats, both real. GM’s EBIT-adjusted excludes the $10.9 billion of EV realignment charges it has booked since the second half of 2025, $7.2 billion of which cost cash. Toyota carries no equivalent add-back. And GM’s wholesale count leaves out its Chinese joint venture vehicles. Treat the comparison as directional.
Even directionally, it inverts the usual telling. GM’s problem is not that it makes too little per car. It makes almost twice what Toyota makes per car and still earns half as much money, because Toyota moves nearly three vehicles for every one GM ships. The entire gap is volume.
Volume is also the denominator under GM’s factory overhead. A plant costs what it costs whether it runs one shift or three. At 73% utilization, better than a quarter of GM’s assembly cost has no vehicle attached to it, and every Silverado carries the difference. That is why the $52,000 transaction price and the 42% full-size pickup share have to work as hard as they do. They are covering for the lines that are dark.
Lansing shows the design flaw underneath. GM built captive capacity for one customer, itself, sized against a forecast it later abandoned. When the forecast broke, the asset had nowhere to go, so GM sold it and took the charge. LG turned the same building into merchant capacity serving an automaker, a grid-storage buyer and a battery-electric program, and filled it. The plant was never the problem. GM’s claim on it was.
Selling assets to protect margin is a legitimate strategy. It also has a floor. Each cut, Cruise, Europe, India, the sedans, the battery joint ventures, removes a loss exactly once. Absorption compounds. Toyota’s 91.9% is what lets it price a Corolla at $24,000 and a Camry at $30,000, post double-digit gains on both this year, and still fund an $800 million retooling at Georgetown.
The Risk
Erik Gordon at Michigan’s Ross School put the counterargument plainly to the WSJ: if GM has decided it does not need to be the biggest, selling fewer vehicles at a higher margin is a defensible strategy. He is right, and the case is stronger than the utilization number alone suggests.
GM is on track for near-record operating profit. Free cash flow guidance rose to $9.5 billion to $11.5 billion. The company bought back $2.8 billion of stock in the first half and holds $19.7 billion of automotive cash. Its 42% share of full-size pickups sits more than 10 points clear of the nearest rival, and nobody has taken that franchise in forty years. GM’s finance chief Paul Jacobson calls the company structurally sounder than at any point in its history, and on cash generation he has the receipts.
Toyota’s own quarter argues the same way. Operating income for April through June fell 8.8% to ¥1,063.4 billion. The ¥400 billion raise to the annual forecast came mostly from moving the yen assumption from ¥150 to ¥160, with the dollar line alone contributing ¥420 billion to the bridge. Net income jumped 75.6%, lifted by selling down part of the Toyota Industries stake and deconsolidating Hino rather than by selling cars. Tariffs cost Toyota roughly $9 billion in its last fiscal year against GM’s $3.1 billion. Toyota’s China share keeps sliding, which is a large part of why it needs America to grow at all.
And GM’s own fix is scheduled. Orion, Fairfax and Spring Hill all come online in 2027. If they land as planned, GM builds more than two million vehicles a year in the US, utilization climbs, and this article ages badly.
The bet, then, is on timing. GM has to hold $52,000 transaction prices and 42% pickup share through 2027 while the industry sells about 15.8 million units into an affordability squeeze. If truck mix cracks first, the fixed cost is still there and the entry-price products that would absorb it are not.
Quick Questions
Is Toyota about to pass GM in US sales? Possibly this year. The gap through July was just over 100,000 vehicles on roughly 1.5 million each, the tightest since 2021. Cox has flagged a year-end flip as plausible. Toyota’s constraint is RAV4 supply, not demand.
Doesn’t GM’s higher margin mean it is winning? On profit per dollar of revenue, yes. On profit per vehicle, yes. On total profit, no, because Toyota sells nearly three vehicles for each one GM ships. Volume is the whole gap.
What is capacity utilization and why does it matter more than share? It measures how much of an installed plant footprint actually produces vehicles. Assembly costs are largely fixed, so a plant running at 73% spreads the same overhead across fewer cars. Utilization sets the cost floor that pricing has to clear.
Did GM lose money on the Lansing plant? GM sold its stake for roughly $1 billion and booked EV-related charges of $10.9 billion across the wider realignment. The plant itself is running, employing about 900 people and supplying Toyota, grid storage customers and Tesla from 2027.
Was 2021 the same situation? No. Toyota briefly outsold GM in 2021 because the chip shortage capped GM’s supply. The current gap comes from decisions GM made about what to build and what to stop building.
The Business Model Analyst Take
The horse race is the wrong scoreboard, and both companies are quietly telling you so.
GM’s margin story is real, and Wall Street has priced it correctly. What it does not price is the difference between a margin produced by pruning and a margin produced by throughput. Pruning is a stock of one-time gains. Barra has spent them well and has a few left. Throughput is a flow, and Toyota’s 91.9% keeps regenerating it: full plants make cheap cars, cheap cars keep plants full, and full plants pay for the next model.
The tell is the eight-year freeze. GM closed factories in 2019 specifically to raise utilization, was forecast to reach 86% by now, and sits at 73%. The plants did not get more productive. The company got smaller around them, which flatters margin and does nothing for absorption.
If you run a business with heavy fixed assets, Lansing is the lesson worth stealing. GM sized a single-customer plant against its own forecast, and when the forecast moved the asset was worthless to it. LG took the identical building, sold its output to three unrelated buyers in two industries, and filled it. Capacity built for one customer is a bet on that customer. Capacity built for a market is inventory.
The number to watch is not the August or December sales tally. It is whether GM’s utilization is above 80% when Orion, Fairfax and Spring Hill are running in 2027. If it is, Barra converted a shrinking company into a productive one. If GM is still at 73% with a fuller product plan, then the last eight years bought discipline without buying scale, and the volume it gave up will have been the cheaper thing to lose.