
How Berkshire Hathaway’s capital turns growth into an option, why record profits followed a policy count that fell 18%, and what the 2026 numbers cost.
GEICO makes money by servicing policies more cheaply than anyone else in American auto insurance and handing the difference back to drivers as price. That part of the story is 90 years old and every competitor page repeats it. The part nobody runs: GEICO’s cheapest years are the years it stops buying customers, and its owner is the only one in the industry rich enough to let that happen. Between the end of 2021 and the end of 2024, GEICO shed roughly 18% of its private passenger auto policies and swung from a $1.9 billion underwriting loss to $7.8 billion of underwriting profit. No shareholder-owned insurer could have survived doing that. Berkshire Hathaway barely noticed.
In 2026 the bill arrived. GEICO’s underwriting expense ratio has climbed 4.9 points since 2024, its premiums written grew 1.1% in the second quarter, and its private passenger auto book went into premium decline. Progressive grew policies 8% over the same stretch. The cost advantage still exists. It stopped translating into customers.
What Is the GEICO Business Model?
GEICO is a wholly owned Berkshire Hathaway subsidiary that sells private passenger automobile insurance direct to consumers in all 50 states and the District of Columbia, with smaller books in motorcycle, ATV, RV, boat and commercial vehicle coverage. It removes the independent or captive agent from the transaction, replaces agent commission with national advertising and in-house claims handling, and converts the resulting cost gap into lower quoted prices. It also runs an insurance agency that brokers homeowners, renters, condominium, life and identity protection policies written by third parties, earning commission on products it does not underwrite. Berkshire reports GEICO as an underwriting-only segment. The investment income on the float GEICO generates sits at the parent, not in GEICO’s own result.
GEICO at a Glance
| Metric | Figure | Period |
|---|---|---|
| Premiums written | $45.2B | FY2025 |
| Premiums earned | ~$44.5B | FY2025 |
| Pre-tax underwriting earnings | $6.824B | FY2025 |
| Combined ratio | 84.7 | FY2025 |
| Loss and LAE ratio | 72.3 | FY2025 |
| Underwriting expense ratio | 12.4 | FY2025 |
| Combined ratio | 91.2 | Q2 2026 |
| Pre-tax underwriting earnings | $994M | Q2 2026 |
| Premiums written growth | +1.1% | Q2 2026 |
| US private passenger auto market share | ~11.6%, third largest | 2024 data, A.M. Best |
| Distribution | Direct response, internet and telephone, plus limited agency | Current |
| CEO | Nancy Pierce, appointed December 2025 | Current |
| Parent | Berkshire Hathaway Inc. | Since 1996 |
Where the Money Comes From
Three lines determine everything. GEICO collects premium, pays claims, and pays the cost of running the operation. Whatever survives is underwriting profit.
In 2025 those lines read $44.5 billion of earned premium, $32.1 billion of losses and loss adjustment expenses, and $5.5 billion of underwriting expenses, leaving $6.824 billion. The loss line moves with medical inflation, repair costs, litigation and how many miles Americans drive. GEICO influences it through rate filings and risk selection, but slowly, because rates need regulatory approval in every state and policies renew on six or twelve month cycles.
The expense line is different. GEICO controls it, and it controls it quickly. Advertising is the largest discretionary component, and GEICO can move a billion dollars of it inside a single budget year. Berkshire never demands a specific combined ratio from GEICO the way Progressive’s investors have come to expect 96 from Progressive, so the expense line is a dial rather than a constraint. Berkshire’s own filing puts the standard loosely: the group expects an underwriting profit over time, across all of its insurance operations, with no target attached to any one of them.
What that permits is unusual. GEICO can decide, in any given year, that acquiring the marginal customer costs more than the customer is worth, turn the acquisition spend down, accept a smaller book, and report a better number. Progressive cannot do that without breaking a compensation system built on a growth and profitability matrix. State Farm cannot do it without stranding 19,200 agent offices whose economics assume volume, a constraint we worked through in the State Farm business model breakdown.
The $9.7 Billion Swing Came From Shedding Customers
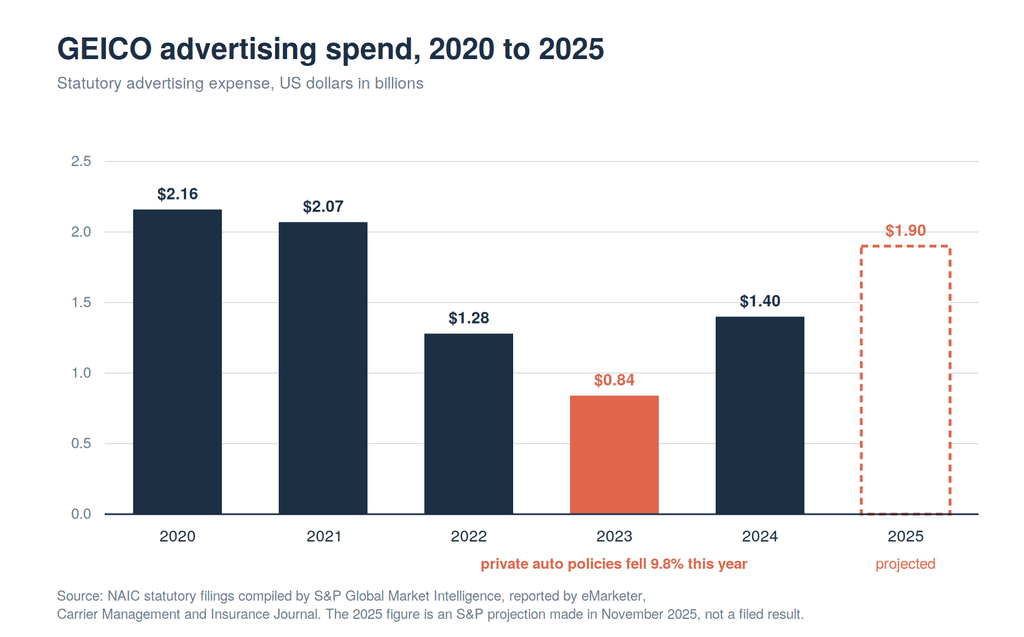
Run the sequence. GEICO cut advertising from $2.07 billion in 2021 to $1.28 billion in 2022, then to $838.2 million in 2023, a two-year reduction of about 60% on NAIC statutory filings compiled by S&P Global Market Intelligence. Private passenger auto policies in force fell 8.9% in 2022 and 9.8% in 2023, then another 0.5% in 2024. Compounded, that is a decline of about 18% in the policy base across three years, a figure we calculate from the three disclosed annual changes.
Over the same window pre-tax underwriting earnings went from a loss of $1.9 billion in 2022 to $3.635 billion in 2023 to $7.813 billion in 2024. A swing of $9.7 billion.
Two forces produced it. Rate increases carried the loss ratio from 81.0% in 2023 to 71.8% in 2024, helped by average written premium per auto policy rising 7.8% in 2024 alone. And the expense ratio collapsed to roughly 9.7 in 2024, a figure we derive by subtracting the disclosed loss ratio from the disclosed combined ratio of 81.5. Compare that to Progressive and State Farm, both of which run companywide expense ratios near 20.3.
Competing pages treat the 9.7 as proof of a structural moat. It was partly a snapshot of a company that had stopped selling. Advertising is the cost of new business. Suspend new business and the ratio falls, because the denominator keeps earning premium from customers who signed up in prior years while the numerator loses its largest variable line. Buffett called the 2024 result spectacular in his final shareholder letter. He also noted the work was incomplete, which reads differently once you know what the improvement was made of.
The Expense Ratio Has Moved 4.9 Points Since 2024
GEICO turned the spending back on. Advertising rose about 67% in 2024 to roughly $1.4 billion, and S&P Global Market Intelligence projected in November 2025 that the 2025 figure could approach $1.9 billion, another 35% increase. That projection predates the filed result, so treat it as an estimate rather than a number.
The expense ratio followed: 9.7 in 2024, 12.4 in 2025, 13.4 in the first quarter of 2026, and 14.6 in the second. Berkshire attributes the increase to commissions and advertising.
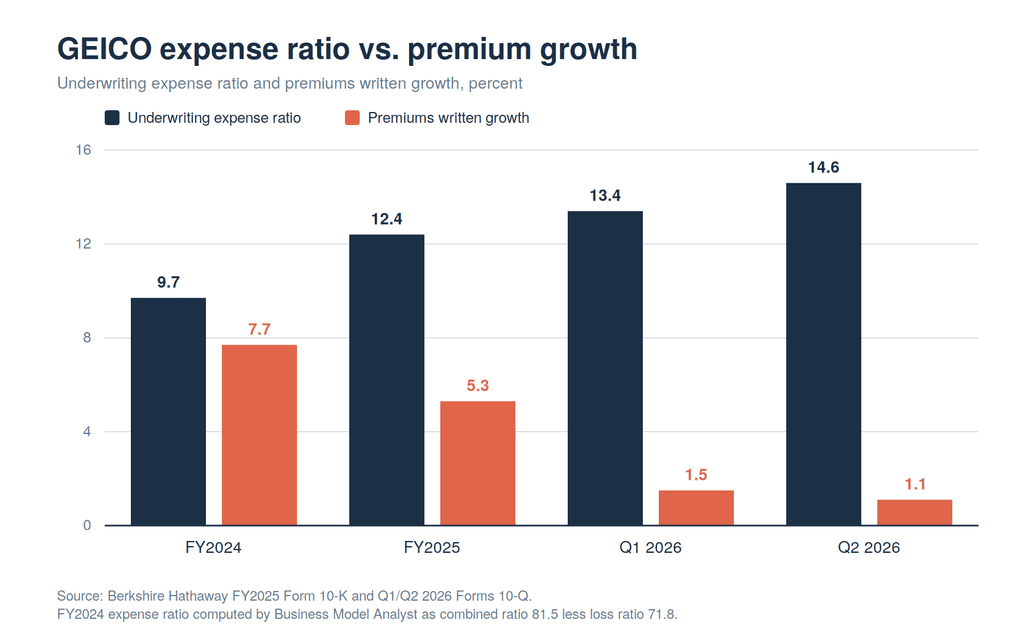
On first half 2026 earned premium of about $22.5 billion, annualizing to roughly $45 billion, each point of expense ratio costs about $450 million. So the move from 9.7 to 14.6 represents about $2.2 billion of annualized spending that was not there two years ago.
Set that against what it bought. Premiums written grew 7.7% in 2024, 5.3% in 2025, 1.5% in the first quarter of 2026 and 1.1% in the second. The two lines cross.
Now the honest caveat, because the lazy version of this argument is wrong. Some of the flat premium reflects a deliberate price cut, not failed advertising. Berkshire says the Q2 2026 increase came from commercial auto growth offset by lower average premiums per policy in private passenger auto, and Greg Abel reported policies in force up about 2% year over year as of March 2026. GEICO is not failing to sell. It is selling at lower prices, which is what Progressive is also doing.
The comparison that matters is per unit of effort. Both companies raised acquisition spending in 2026. Both cut rates. Progressive’s personal lines policies grew 8% in the second quarter and its direct auto book grew 10%. GEICO’s grew about 2%. The gap is not a cost gap. GEICO is still the cheapest operator in the category by a wide margin. The gap is reach and segmentation, which is the argument we ran in the Progressive business model teardown from the other side.
The Lowest Expense Ratio in Auto Insurance Is Reported Net of a Revenue Line
Berkshire’s 10-K states that earnings from GEICO’s insurance agency, meaning third-party commissions net of operating expenses, are “included as a reduction of underwriting expenses.”
GEICO brokers homeowners, renters, condominium, life and identity protection policies written by other carriers. It earns commission on those sales. That commission income does not appear as revenue. It is netted against the cost line that produces the most-quoted number in the business.
The amount is never disclosed. We are not going to estimate it, and neither should anyone else. But the direction is certain: GEICO’s gross cost of running its insurance operation is higher than 12.4% of premium, by an undisclosed margin. The industry’s benchmark low-cost ratio is a net presentation, and the trade press, the comparison sites and the canvas-template pages all quote it as if it were gross.
The Growth Is Coming From a Line Under 5% of the Book
GEICO’s headline first quarter 2026 growth of 1.5% conceals a split. S&P Global Market Intelligence found commercial auto premiums up 68.6% in the quarter against a 0.6% decline in private passenger auto, the first negative print in the core line since private auto growth peaked at 11% in mid-2024.
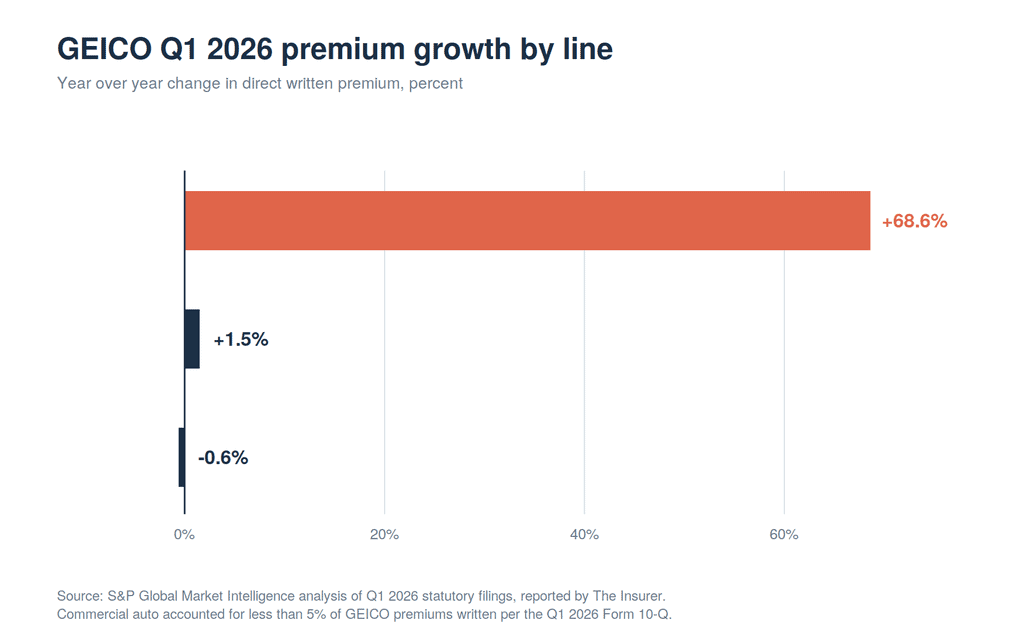
GEICO’s direct commercial auto premium reached $536.6 million in the first quarter of 2026, against $32 million in the same quarter of 2023. Berkshire as a group moved to third place in US commercial auto in 2025 from fifth in 2024, passing Old Republic and Liberty Mutual. The Q1 2026 10-Q describes commercial auto as currently less than 5% of GEICO premiums written.
Read the strategy in that. Facing a personal auto market where reacquiring customers costs 4.9 points of expense ratio, GEICO opened a second front where its base is small enough that percentage growth is cheap. It works arithmetically. It also puts GEICO into direct competition with the carrier that has led US commercial auto since 2015, in a longer-tail line where pricing errors take years to surface rather than months.
GEICO Sells the Bundle It Cannot Build
The single largest structural constraint on GEICO gets almost no coverage. GEICO does not underwrite homeowners insurance. It brokers it.
That has consequences the commission income does not offset. GEICO cannot price auto and home as one economic unit, cannot hold the reserves and float that the home policy generates, cannot use home renewal as an anchor against auto shopping, and cannot decide to lose money on home in order to keep the household, which is exactly what State Farm does on purpose. Progressive spent the last decade building a property book specifically so it could climb into the bundled segment, and its own second quarter 2026 disclosure sizes that segment at $229 billion of premium with Progressive holding 3.9%. Captive agents control $120.7 billion of it.
GEICO’s answer to the bundled household is a referral fee. That is a materially different business from owning the customer, and it caps the ceiling on lifetime value per household in a way no amount of advertising fixes. The retention priority Nancy Pierce named on taking the CEO job in December 2025 runs straight into it.
Market Position and the Claims Environment
On NAIC data for 2025, GEICO wrote $42.905 billion of direct private passenger auto premium for 11.56% of a $371.0 billion market, third behind State Farm at 18.64% and Progressive at 18.60%. Berkshire’s 10-K reports the same ranking on A.M. Best 2024 data, third at approximately 11.6%, with the five largest carriers holding 63.6% combined.
Worth carrying the caveat we attach to every piece in this cluster: the top of that table is unsettled. S&P Global Market Intelligence puts Progressive ahead of State Farm on a trailing-twelve-month basis through March 2026, but its own methodology note concedes the figure includes estimates for two New Jersey-domiciled Progressive subsidiaries that file no public quarterly statements, and that published data still shows State Farm slightly ahead. On published NAIC annual data for 2025, State Farm remains number one. Third place is not in dispute.
The 2026 deterioration is not all self-inflicted. Berkshire disclosed that private passenger auto bodily injury claim frequency rose 5% to 7% in the first half of 2026, with property damage and collision frequency up 3% to 5%. Bodily injury severity rose 10% to 12%. No significant catastrophe losses hit the first half, so the damage is operating rather than weather.
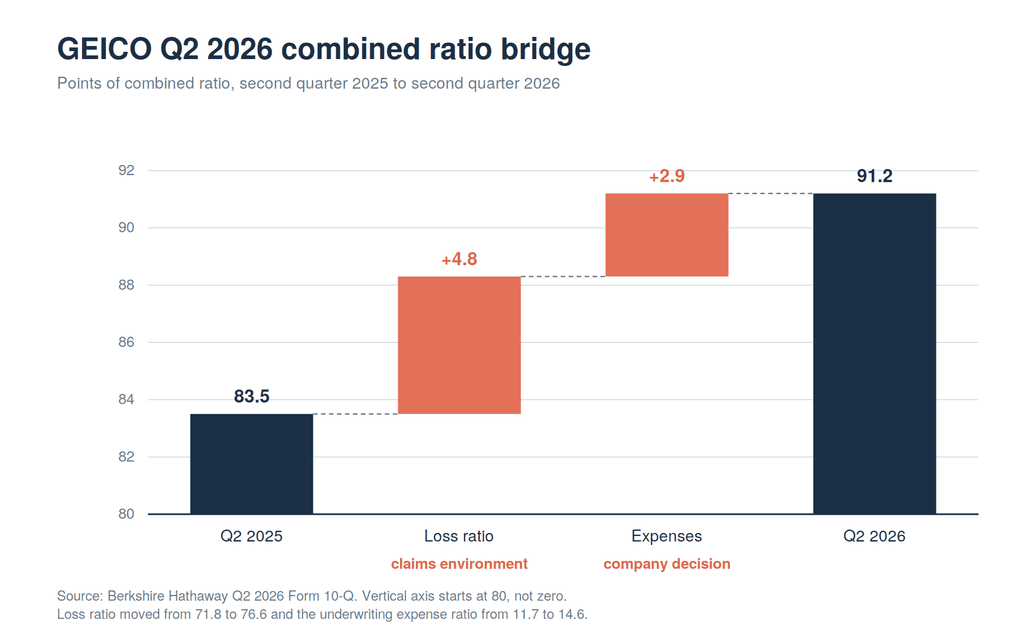
Decompose the 7.7-point move in the second quarter combined ratio and 4.8 points came from the loss ratio and 2.9 points from underwriting expenses. So about 62% of the deterioration reflects a claims environment every carrier faces and 38% reflects a spending decision GEICO made. The second number is the reversible one, and reversing it means going back to not growing.
What the Model Adds Up To
Berkshire’s US insurers held approximately $333 billion of combined statutory surplus at the end of 2025 and its major insurance subsidiaries carry A++ from A.M. Best and AA+ from Standard & Poor’s. Progressive held $28.4 billion of statutory surplus against $83.2 billion of net premiums written. Berkshire’s insurance capital runs roughly 11.7 times Progressive’s while GEICO writes a little over half of Progressive’s premium.
That ratio is the model. Capital that deep removes the requirement to grow, and removing the requirement to grow is what lets GEICO price for margin, cut acquisition spending to the bone, watch a fifth of the book walk out, and post the best underwriting years in its history while it happens. Float compounds at the parent regardless, having gone from about $138 billion at the end of 2020 to $177.5 billion at the end of June 2026. The float mechanics sit in our Berkshire Hathaway business model breakdown and we will not re-run them here.
The catch is that the maneuver works once per cycle. Customers who left between 2022 and 2024 went to a company with better segmentation and 40,000 independent agencies alongside its direct arm. Buying them back in a soft market, against rivals cutting rates in most of the country, costs 4.9 points of expense ratio for about 2% policy growth. Abel has set a three-year objective that balances combined ratio, retention and policy growth, which is a polite way of saying GEICO can no longer optimize for one of them at a time.
Frequently Asked Questions
How does GEICO make money? Through underwriting profit on auto insurance premium. In 2025 GEICO earned $44.5 billion of premium, paid $32.1 billion in losses and loss adjustment expenses and $5.5 billion in underwriting expenses, producing $6.824 billion of pre-tax underwriting earnings. Investment income on the float GEICO generates is reported at Berkshire, not inside the GEICO segment.
Why is GEICO cheaper than other insurers? It removes agent commission from the cost stack and replaces it with national advertising, which spreads across the whole book rather than attaching to each policy. In 2024 that produced an underwriting expense ratio near 9.7 against roughly 20.3 at Progressive and State Farm. The advantage narrowed to 14.6 by the second quarter of 2026 as GEICO raised acquisition spending, and the reported figure is stated net of commissions GEICO earns brokering other carriers’ policies.
Is GEICO owned by Warren Buffett? GEICO is a wholly owned subsidiary of Berkshire Hathaway, which completed the acquisition in 1996. Buffett first bought GEICO stock personally in 1951. Greg Abel became Berkshire’s CEO in January 2026 and delivered his first shareholder letter alongside the 2025 results.
Why did GEICO lose so many customers? GEICO raised rates hard to restore margin after a $1.9 billion underwriting loss in 2022 and cut advertising from $2.07 billion in 2021 to $838.2 million in 2023. Private passenger auto policies fell 8.9% in 2022 and 9.8% in 2023, roughly 18% cumulatively through 2024. Berkshire’s own filing linked the advertising reduction to the policy decline.
Is GEICO bigger than Progressive? No. On NAIC 2025 data GEICO wrote $42.905 billion of direct private passenger auto premium for 11.56% share against Progressive’s $69.006 billion and 18.60%. GEICO has held third place since Progressive passed it, and the gap has widened rather than closed.
Does GEICO sell homeowners insurance? Not as an underwriter. GEICO operates an insurance agency that places homeowners, renters, condominium, life and identity protection policies written by third-party carriers and earns commission on them. It carries none of the risk and none of the reserves, which is why it cannot price a bundled household the way State Farm or Progressive can.
What happened to GEICO in 2026? Underwriting earnings fell 45.4% in the second quarter to $994 million as the combined ratio worsened 7.7 points to 91.2. Bodily injury claim frequency and severity both rose, and the underwriting expense ratio climbed to 14.6 on higher commissions and advertising. Premiums written grew 1.1%, with commercial auto supplying the growth and private passenger auto premium turning negative in the first quarter.
The Business Model Analyst Take
GEICO is the only large US auto insurer whose owner does not need it to grow, and that single fact explains more of its behavior than the direct-distribution story everyone tells. The low expense ratio is real, but it is a throttle setting as much as a structure: it drops when GEICO stops buying customers and rises when GEICO wants them back. From 2022 to 2024 GEICO ran the throttle all the way down and produced a $9.7 billion underwriting swing on a book that shrank 18%. Berkshire’s balance sheet made that survivable. Nothing else in the category could have absorbed it.
The 2026 results are the invoice on that trade. GEICO is spending about $2.2 billion a year more on acquisition than it did in 2024 and buying roughly 2% policy growth where Progressive buys 8%. Third place at 11.6% share is stable, defensible and profitable at a 91.2 combined ratio that most carriers would sign for today. The ceiling is what changed. Without a homeowners book of its own, GEICO cannot reach the bundled households that carry the longest tenure, and referral commission is a thin substitute for owning the second policy. Nancy Pierce inherited a company that can afford almost anything except the one thing it needs, which is a reason for a driver who already left to come back.
Watch two numbers over the next four quarters. If the expense ratio keeps climbing while policies in force stay near 2%, the acquisition spending is not clearing its hurdle and Berkshire will turn it down again, because it can. If commercial auto keeps compounding from a base under 5% of premium, GEICO has quietly changed what kind of insurer it is.