
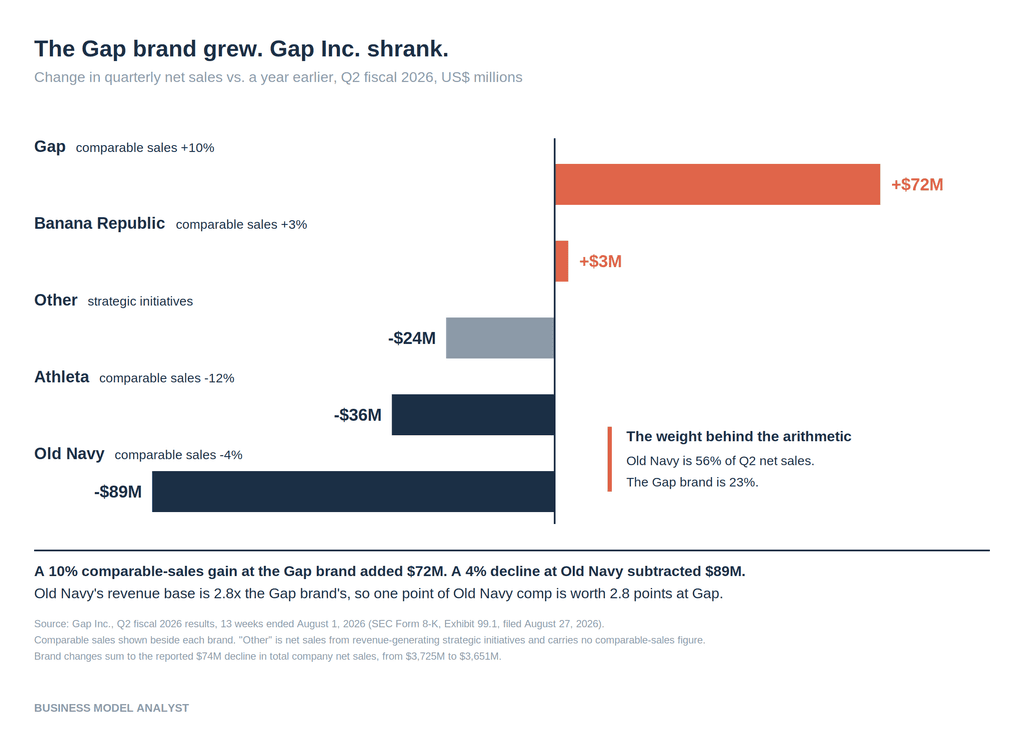
The namesake brand added $72 million in the quarter. Old Navy gave back $89 million. Gap Inc.’s one working growth lever cannot reach the brand that sets its profit and loss.
Gap Inc. reported second quarter fiscal 2026 results on August 27. Comparable sales at the Gap brand rose 10%, the best number in the portfolio. Old Navy fell 4%. Because Old Navy’s revenue base runs 2.8 times the size of the Gap brand’s, one point of Old Navy comp carries as much money as 2.8 points at Gap, and total company net sales fell 2% to $3.65 billion. The stock rose 15% the next morning. The brand reinvigoration playbook that Richard Dickson brought from Mattel works on the two brands with cultural memory to reactivate, and those two together are 36% of the company.
The two sentences
Richard Dickson said two things about his own portfolio this week. In the earnings release he described himself as “particularly proud of the momentum at the Gap brand” and another quarter of double-digit comparable sales there. On Old Navy, he told The Wall Street Journal: “We made some assortment and pricing decisions that impacted our value equation.”
Both are true. The first describes 23% of Gap Inc. The second describes 56%.
What Happened
Gap Inc. sold $3,651 million of merchandise in the 13 weeks to August 1, against $3,725 million a year earlier. Company-wide comparable sales came in at negative 1%. Store sales fell 3%, online sales fell 1%, and online held at 35% of the total.
The brand split is where the quarter lives:
| Brand | Q2 net sales | Change vs. Q2 2025 | Comparable sales | Share of Q2 net sales |
|---|---|---|---|---|
| Old Navy | $2,061M | -$89M | -4% | 56.5% |
| Gap | $844M | +$72M | +10% | 23.1% |
| Banana Republic | $478M | +$3M | +3% | 13.1% |
| Athleta | $264M | -$36M | -12% | 7.2% |
| Other | $4M | -$24M | n.a. | 0.1% |
| Gap Inc. | $3,651M | -$74M | -1% | 100% |
The Gap brand grew 9% in net sales and 10% on a comparable basis, driven by denim, fleece, and kids and baby. It added $72 million. Old Navy lost $89 million on what Dickson called expected pressure in women’s seasonal categories plus an unanticipated traffic slowdown. Athleta lost another $36 million and has now printed negative comps against a year in which it also printed negative comps. The “Other” line, which Gap Inc. defines as net sales from revenue-generating strategic initiatives, shrank from $28 million to $4 million.
The profit line tells a separate story. Reported gross margin hit 52.8%, up 1,160 basis points. Of that, 1,140 basis points came from a net recovery of tariffs collected under the International Emergency Economic Powers Act. Strip the refund out and gross margin rose 20 basis points. Reported operating income was $676 million; adjusted operating income was $259 million. Reported diluted earnings per share came in at $1.38, of which $0.86 traces to the refund. The customs money accounts for 98.3% of the gross margin expansion and 61.7% of reported operating income.
Two details inside that refund deserve attention. Gap Inc. booked approximately $512 million of IEEPA refunds but collected only $95 million in cash during the quarter, with the rest expected in the third quarter. You can see the receivable on the balance sheet: other current assets climbed $437 million year over year, against $417 million of refunds recorded and not yet banked. And the company voluntarily committed roughly $95 million of the windfall to certain vendors, calling it a commitment of appreciation, which prices its own view of who absorbed the duty at about 19 cents on the dollar. We covered the entitlement mechanics in Everyone Paid the Tariffs. Only the Importer of Record Gets a Refund.
Investors bought it. The Wall Street Journal reported shares up 15% Friday morning to $23.95, the biggest single jump in more than a year. On roughly 360 million shares, that move added about $1.1 billion of market value, or 4.3 times the entire quarter’s adjusted operating income.
The Backstory
On February 28, 2019, the Gap Inc. board approved a plan to split the company in two, spinning Old Navy out as a standalone public company. Eleven months later the board killed it. Interim chief executive Robert Fisher blamed cost, complexity and softer performance. He then described how the remaining company would be run, naming “our growth brands, Old Navy and Athleta” and saying the focus for Banana Republic and Gap brand would be profitability.
Read that classification against the quarter Gap Inc. reported this week. The two designated growth brands fell 4% and 12%. The two brands set aside for profitability rose 10% and 3%. The growth brands are 63.7% of net sales; the profitability brands are 36.2%. Gap Inc.’s board sorted its own portfolio into engines and harvest assets, and six years later the sort has inverted.
Dickson arrived in August 2023 from Mattel, where he ran the Barbie revival that turned a 64-year-old doll into a billion-dollar film. At Gap he applied the same instruments: celebrity partnerships with Victoria Beckham and Hailey Bieber, a creative director in Zac Posen whose designs reached the Met Gala and the Oscars, and marketing built around what the company calls big ideas and culturally relevant storytelling. The Gap brand responded. It had material to work with, having spent the 1990s defining how a generation of Americans dressed, from swing-dancing khaki commercials to Sharon Stone wearing a Gap T-shirt to the 1996 Oscars.
Old Navy opened in 1994 as Gap Warehouse. By the company’s own account it reached $1 billion in sales faster than any retailer before it, and it did so on price.
The Plan
Gap Inc. is replacing Old Navy’s leadership. Haio Barbeito, president and chief executive since 2022, moves to an advisory role on November 2. Michael Francis takes over. Francis spent 26 years at Target, more than a decade of it as chief marketing officer, where he built the cheap-chic positioning that let Target charge more than a discounter should. He then spent eight months as president of JCPenney under Ron Johnson, advised Walmart’s board for a decade, and joined Gap Inc. earlier this year as Old Navy’s chief customer officer and head of marketing shared services for the group.
Dickson praised him as one of retail’s most respected commercial and customer leaders, and framed the appointment as a step “into this operating role.” The word choice matters, because Francis arrives from the marketing seat to fix a problem the chief executive has diagnosed as assortment and pricing.
Around that, the company narrowed its full-year sales outlook to growth of 1% to 1.5%, cut its Old Navy comp assumption to flat-to-down-1%, raised its Gap brand assumption to high-single to low-double digits, and lifted adjusted operating margin guidance to 7.4% to 7.6%. Adjusted earnings per share guidance went up a nickel, to $2.35 to $2.45.
That nickel is worth pausing on. The prior guide paired $2.30 to $2.40 of adjusted earnings with roughly 375 million diluted shares. The new one pairs $2.35 to $2.45 with roughly 367 million shares. Multiply the midpoints and the implied adjusted net income moves from $881.2 million to $880.8 million, a change of five hundredths of one percent. The raise is the buyback. Gap Inc. returned $726 million to shareholders in the first half, $601 million of it in repurchases.
The Business Model Angle
Treat brand reinvigoration as what Gap Inc. sells it as: a repeatable capability, a playbook that travels from brand to brand. Then look at the quarter, which is close to a controlled experiment. One chief executive, one supply chain, one marketing organization, one consumer, one 13-week window, four brands. The results ran from +10% to -12%.
Rank the four brands by how much stored cultural memory each one holds, and the comps sort in the same order. Gap, founded 1969, culturally central for two decades, +10%. Banana Republic, founded 1978, a safari-catalog cult that became aspirational office wear, +3%. Old Navy, founded 1994 as a price format, -4%. Athleta, acquired in 2008 and never dominant in its category, -12%.
That ordering suggests the playbook is not a capability. It is a withdrawal from an account that somebody else funded decades ago. Collaborations, a creative director and cultural storytelling raise willingness to pay for a brand whose problem is relevance. They do nothing for a brand whose promise is arithmetic. Old Navy’s customer does not need to be reminded that Old Navy exists. She needs the price to be right, and Dickson said the price was not right.
Gap Inc.’s structural problem follows from the weights. The brands that respond to the only lever management has proven it can pull are 36% of revenue. The brand that does not respond is 56% of revenue and 66% of company-operated square footage, 19.6 million square feet across 1,241 North American stores against 6.0 million for the whole Gap brand. Old Navy carries two-thirds of the lease book and generates a bit more than half the sales, which means fixed-cost absorption for the entire company runs through the brand that marketing cannot repair.
The arithmetic is unforgiving. One percentage point of Old Navy comparable sales carried $21.5 million of revenue last year. One point at the Gap brand carried $7.72 million. To cover Old Navy’s decline on its own, the Gap brand needed to grow net sales 11.5%; it grew 9%. To cover the whole portfolio’s declines, it needed 18.9%. A brand posting double-digit comps at the top of its guided range still did not get the company back to flat.
For an operator, the lesson sits in how you classify your own assets. Gap Inc.’s board looked at four brands in 2020 and decided the young ones were the future and the old ones were the cash. It had the direction of causation backwards: the old brands were carrying the only asset the company could not buy, and the young brands were carrying the volume. If you run a portfolio, the question is not which unit grows fastest. It is which unit your one repeatable capability can reach, and how much revenue sits outside its range.
The Risk
Several honest arguments cut against this reading.
Old Navy’s quarter may be cyclical rather than structural. Dickson named a specific cause, women’s seasonal assortment in dresses, shorts and swim, plus marketing that failed to drive traffic. Merchandising misses get fixed. Management says August improved, and the brand grew comps as recently as last year’s second quarter. If Old Navy prints a positive comp in the fourth quarter, the heritage argument looks like an overfit to one bad print.
The Athleta datapoint may not belong in the ranking at all. Athleta is losing share to Lululemon, Alo Yoga and Vuori in a category that has attracted enormous capital, a competitive story more than a brand-memory story. Our Lululemon competitor teardown and the Lululemon SWOT both describe a premium athleisure market where well-funded specialists are taking the middle. Athleta might be losing on product and price, not on heritage.
Banana Republic weakens the case from the other side. It has posted five consecutive quarters of positive comps, but at 3%, not 10%. If stored heritage were the mechanism, a brand with almost fifty years of it should be closer to the Gap number.
The earnings quality carries its own risk. The $417 million still owed to Gap Inc. is a receivable from a defendant that has appealed. The Justice Department filed notice with the Federal Circuit on June 2 contesting the government’s obligation on finally liquidated entries. Across the full year, $0.63 of a credit-card interchange settlement, $0.89 of tariff refunds and a $0.10 charitable offset add to $1.42 of the $3.82 reported earnings-per-share midpoint. More than a third of Gap Inc.’s fiscal 2026 reported earnings come from a lawsuit and a customs refund.
And the tape may be reading something we are not. Adjusted operating margin guidance rose while the sales guide came down, which means management believes it can hold profit through a soft top line. On an $8.6 billion market capitalization against $15.4 billion of annual revenue, buyers were not paying for growth on Friday. They were paying about ten times adjusted earnings for a portfolio in which one brand has proven it can still move. As Burberry showed in July, the tape and the press release disagree often enough that neither one settles the question alone.
Quick Questions
Did Gap Inc. beat expectations? On profit, yes. On sales, no. Dickson said top-line results came in modestly below expectations while gross margin strength pushed profit past them. Almost all of that gross margin strength was the tariff refund.
How much of the quarter was the tariff refund? The net IEEPA recovery contributed 1,140 basis points of the 1,160-basis-point gross margin expansion, $417 million of the $676 million reported operating income, and $0.86 of the $1.38 reported diluted earnings per share.
Is the Gap brand turnaround real? The revenue is real. Gap brand net sales rose 9% to $844 million, and the company raised its full-year expectation for the brand. The question is scale, not authenticity. The brand is 23% of the company.
Why did the stock rise if sales fell? Investors bought the direction of the namesake brand, the margin beat, and a raised earnings-per-share outlook. The Wall Street Journal put the move at 15%, to $23.95.
Why is the earnings-per-share raise not a profit raise? Gap Inc. raised adjusted earnings-per-share guidance by five cents and cut its expected share count from about 375 million to about 367 million. Implied adjusted net income at the midpoint moves from $881.2 million to $880.8 million.
What has to happen for Gap Inc. to grow? Old Navy has to grow. At 56% of net sales, it sets the company’s direction regardless of what the other three brands do.
The Business Model Analyst Take
Gap Inc. has spent three years proving that Richard Dickson can make an old American brand interesting again. That is worth crediting. Turning the Gap brand from a mall relic into a business with double-digit comps and red-carpet placements is hard work that most of his predecessors failed at, and buyers paid a billion dollars for the evidence on Friday.
The trouble is the shape of the company underneath. Gap Inc. owns one repeatable skill and two brands it can use on. The other 64% of revenue sits in a value brand and an activewear brand where the customer decides on price and product, and where storytelling changes very little. The board saw this backwards in 2020 and put its growth chips on exactly the two brands that would go on to shrink.
Watch one number over the next two quarters. If Old Navy returns to positive comparable sales under Michael Francis, the playbook travels further than we think and Gap Inc. is an earlier-innings story than the tape suggests. If Old Navy keeps sliding while Gap and Banana Republic keep climbing, the company has a great brand attached to a bigger business that its best tool cannot touch, and the 2019 spin-off logic deserves another hearing.
Any operator running more than one brand meets this test sooner or later. Your best capability has a range. Measure how much of your revenue sits inside it before you decide which unit is the growth story.