
The agency says disclosure fixes the problem. Read the draft and it doubles as a compliance recipe for retailers who already own the data.
On August 19, 2026, the FTC published a proposed enforcement policy statement on personalized pricing and opened a 30-day comment window. The agency says Congress never gave it power to ban the practice, so it will police disclosure instead: retailers must say a price is personalized, say why, and say which data drove it. The draft also names a version that would likely pass. That version runs on a retailer’s own logged-in purchase history, which hands an advantage to whoever already owns a loyalty file.
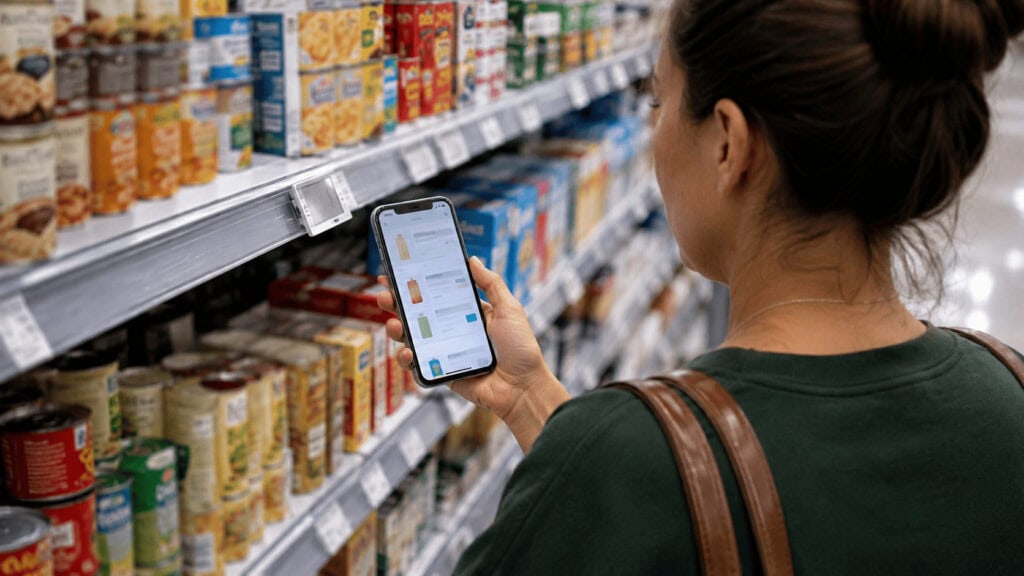
You are standing in a Kroger aisle with the app open. The shelf tag says $6.49. The app says $5.99, and it says so because the store has watched your basket for eleven years. Nobody is going to make Kroger stop doing that. What the FTC proposed today is that the app has to tell you.
That distinction sounds procedural. It reorders the retail data business.
What Happened
The Federal Trade Commission released a draft enforcement policy statement on personalized pricing and asked for public comment over the next 30 days. Chairman Andrew Ferguson framed the core expectation plainly: shoppers assume a listed price is the same one their neighbor sees, not an estimate of what they personally will tolerate.
The commission concedes it cannot outlaw the practice. Congress gave it no authority to prohibit personalized pricing “in all circumstances,” so the agency is routing the problem through Section 5 of the FTC Act, which covers unfair or deceptive acts. Under the draft, a retailer that personalizes a price and hides it commits a likely Section 5 violation. Three disclosures satisfy the duty: that the price is personalized, the basis for the personalization, and the categories of data feeding it.
Two details the coverage will skip. First, this is a draft, and the document says so in its own text: it confers no rights, binds nobody, and in any enforcement action the commission still has to prove a violation of some existing statute or rule. Second, the trigger is not the algorithm or the data. It is whether shoppers reasonably expect the price to be static. That choice does more work than anything else in the document.
The Backstory
The FTC opened a 6(b) study into what it called surveillance pricing in July 2024, ordering documents from Mastercard, Accenture, PROS, Bloomreach, Revionics and McKinsey. Staff published interim findings in January 2025 under Lina Khan, reporting that retailers could feed cursor movements and abandoned carts into individual price offers. Ferguson, then in the minority, objected to the timing and to the loaded term, while agreeing the practice deserved study. He now owns the file.
The pattern since then has been consistent, and it favors the argument below. In July 2025, Delta’s president had told investors the airline was moving toward an available price for the individual passenger. Within two weeks of that becoming a political story, Senators Ruben Gallego, Richard Blumenthal and Mark Warner wrote to CEO Ed Bastian, and Delta answered that its fares never touch personal data and never will. Transportation Secretary Sean Duffy promised investigations. No rule existed. No enforcement action landed. Publicity alone reversed the roadmap.
Instacart ran the retail version. Consumer Reports and Groundwork Collaborative put more than 400 shoppers on the platform at the same moment in December 2025, and three quarters of items came back at more than one price. Instacart called the gaps randomized experiments and shut them down. It also paid $60 million in December 2025 to settle unrelated FTC claims about deceptive delivery pricing, which is how it ended up cited in a footnote of today’s draft.
States moved first and moved harder. New York’s Algorithmic Pricing Disclosure Act mandates a scripted, all-caps label on affected prices, survived a National Retail Federation First Amendment challenge in the Southern District of New York, and has been enforceable since November 2025. Maryland banned personalized food pricing outright in April 2026, effective October 1. We covered the full state wave and the fifty-plus bills behind it in June, so this piece stays on what the federal draft changes.
The Plan
Read the draft as a compliance document rather than a warning and it becomes specific.
The legal test is consumer expectation. The FTC says personalized pricing is a long-established norm in insurance and credit and an alien one at the grocery shelf, and that difference is what makes concealment deceptive. To justify the approach, the commission points at the Fair Credit Reporting Act, which forces lenders to disclose the basis for an adverse decision, and at state insurance rules that do the same for premiums. The agency is importing the credit-pricing regime into general retail.
Then it describes what compliance looks like. Telling a shopper they were “specially selected” fails, because the phrase omits the mechanism. A disclosure that the price reflects an estimate of willingness to pay, derived from that shopper’s prior purchases at that same retailer under that same login, would likely be enough. The commission wrote the safe harbor into the record.
The seven illustrative scenarios point the same direction. A food delivery app charging more to someone who cannot leave the house. A grocer raising the milk price because the household has several children. A hotel pricing off a funeral trip. A rideshare charging more for a run to the emergency room, or because the passenger has no competitor app installed. A retailer marking up a security camera after finding a court filing showing the buyer was robbed, or because the shopper is standing in its parking lot.
Count them and the theory sharpens.
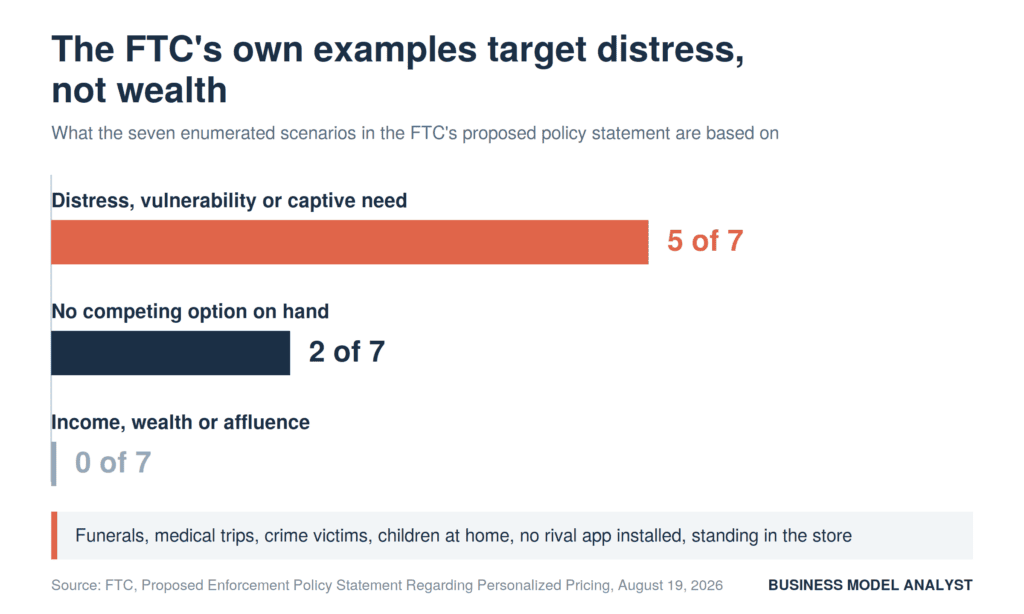
Five of seven rest on distress or captive need. Two rest on the absence of a rival option. None involve charging a rich shopper more for being rich. The FTC is not prosecuting price discrimination. It is prosecuting the monetization of a bad day.
The Business Model Angle
First-party loyalty data acquired a regulatory moat this morning. The safe harbor the FTC sketched requires data the shopper handed over, at that retailer, under a login they control. That describes a loyalty program and excludes almost everything a data broker sells. Kroger tells investors that roughly 95% of its transactions attach to a loyalty card, that it reaches about 63 million households, and that twenty years of this history powers an alternative-profit business it calls fast-growing and high-margin. Kroger Precision Marketing profit grew more than 20% in the first quarter of fiscal 2026. Every rival that rents third-party behavioral data now carries disclosure risk that Kroger and Target’s Roundel operation do not. Regulation of a data practice usually costs the incumbent. This one pays them.
The rule shrinks as the practice spreads. Because deception turns on reasonable expectation, the duty is heaviest in categories where personalization is new and disappears where it becomes ordinary. Nobody sues an insurer for quoting a personal premium. If enough grocers personalize openly for long enough, shoppers stop expecting a static shelf price, and the Section 5 hook loosens. The FTC has drafted a rule that weakens itself every year it goes unenforced, which turns compliance into a race to normalize the practice loudly rather than a reason to abandon it.
The compliant architecture is high-low pricing. A disclosed markup invites a screenshot. A disclosed discount reads as a reward. Maryland’s ban carves out promotions and loyalty programs by statute, New York’s law carves out coupons, and the FTC’s own draft distinguishes a shopper who believes a personalized price is a discount from one being quietly charged more. Set a real list price and personalize downward and the whole apparatus keeps running on the right side of every one of these regimes. The catch sits in a footnote of the FTC draft, which cites the 1965 Colgate-Palmolive decision holding that inflating a reference price to stage a discount is itself deceptive. So the anchor has to be genuine, meaning someone actually pays it. Retailers who want to keep personalizing have a reason to raise shelf prices and widen the gap between the tag and the offer. That is high-low pricing rebuilt by regulation, and it runs directly against the everyday-low-price model Walmart spent decades converting into an ad business.
The Risk
The strongest case against all of this is that the document does nothing. The FTC wrote that it binds no one, the comment window is open until roughly late September, and the NRF spent last summer arguing in federal court that a compelled pricing label is unconstitutional speech. That challenge failed in one district. It has not been tested against a federal statement, and the retail industry has both the money and the motive to try.
The safe-harbor moat also depends on the FTC keeping the login-account example in the final text. The commission explicitly declined to say whether some personalized pricing stays unfair even when disclosed in full, which leaves room to close the door it opened today. Comment periods change documents.
The economics are genuinely unsettled, and the FTC’s own footnotes admit it. The research it cites, including work by Dubé and Misra and by Buchholz, finds welfare effects that cut both ways: personalization funds discounts for hesitant buyers as readily as markups for captive ones. Strip it out and the list price becomes the highest price anyone pays. The commission’s conclusion, that sophistication reduces consumer benefit, is a reading of thin literature rather than a settled finding.
Watch three things. Whether any large retailer publishes a personalized-pricing disclosure rather than quietly retiring the feature, which would tell you the practice was widespread. Whether the login-account example survives to the final statement. And whether shelf prices in grocery start climbing while app-exclusive offers deepen, which is what the high-low prediction looks like from the checkout line.
Quick Questions
Does this make personalized pricing illegal? No. The FTC says Congress never gave it authority to ban the practice, and the draft states outright that it creates no rights and binds nobody. Concealing personalization is what the agency will pursue, under existing unfair-and-deceptive-practices law.
What disclosure would satisfy the FTC? Three elements: the fact that the price is personalized, the basis for it, and the types of data used. The draft’s own example of an adequate disclosure describes a price built on estimated willingness to pay, derived from prior purchases at that same retailer under the same login.
Do loyalty discounts count? Maryland’s ban and New York’s disclosure law both carve out coupons, promotions and loyalty programs, and the FTC’s illustrative scenarios all involve raising a price rather than lowering one. A discount off a genuine list price sits outside every current regime. Manufacturing a fake list price to stage that discount does not.
Who does this hit hardest? Third-party pricing intermediaries and data brokers. The safe harbor the FTC described runs on data a shopper gave one retailer under one account, which is the one input a broker cannot supply.
The Business Model Analyst Take
Ferguson gave up the ban and kept the leverage. Delta proved in 2025 that this category dies on exposure rather than on enforcement: a president describes individualized fares to investors, three senators write a letter, and the airline swears off the roadmap inside a fortnight. Requiring the disclosure produces the same effect at scale, without a rulemaking anyone can challenge as ultra vires.
What the commission also did, probably without meaning to, was write down the terms on which personalized pricing survives. Own the relationship, collect the data yourself, keep it behind a login, disclose the arithmetic, and personalize downward from a price you are willing to defend. Retailers with mature loyalty files can meet all five conditions this quarter. Everyone renting behavioral data from a broker now has a compliance problem attached to a product they were already struggling to justify.
The consumer question is whether that trade is worth taking. A world where prices are personalized in the open, off data you handed over, from a posted price you can see, beats one where the same thing happens invisibly. It also means the posted price goes up.