
On Tuesday, July 14, France and Spain meet at Dallas Stadium in Arlington for the first semifinal of the 2026 World Cup, with a place in the July 19 final in New York on the line. Kylian Mbappé against Lamine Yamal. Two-time world champions against reigning European champions. Both sides arrived here unbeaten. Most neutrals think this is the real final.
Run the same fixture as an economic contest and the pre-match graphics tell you the result before kickoff. France is the seventh-largest economy on the planet. Spain is somewhere around fourteenth. France is 72% bigger and 27% richer per head. This should be a rout.
It is not. And the reason it is not is sitting in a credit rating file at S&P Global, where these two countries now carry the exact same score.
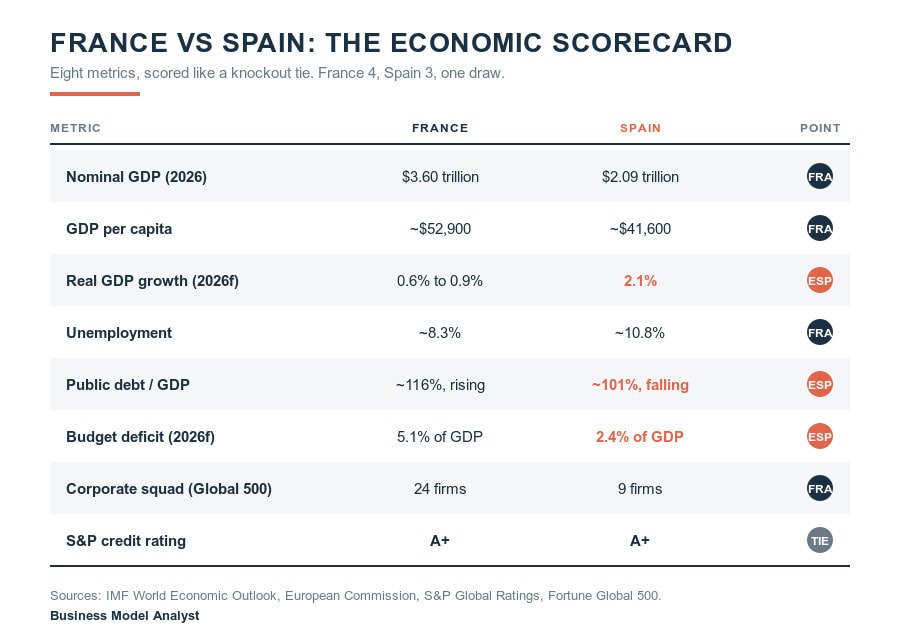
What this is: A head-to-head economic comparison of France and Spain, staged as their real 2026 World Cup semifinal and scored across the metrics that decide whether an economy is actually winning rather than just how big it is: total output, wealth per person, growth, jobs, public finances, corporate depth, and creditworthiness. Figures come from the IMF World Economic Outlook, the European Commission, national statistics agencies, and S&P Global Ratings.
The verdict: France wins the match 4 to 3, with one category drawn. But every category France wins measures something it already owns. Every category Spain wins measures something that is currently moving. That is the whole game.
The Tale of the Tape
First Half: France Scores Early
Total output: France
France produces roughly $3.60 trillion a year against Spain’s $2.09 trillion. That is not a rounding error. It is an entire Netherlands-plus-Belgium of extra output. Scale is not a vanity metric either. It buys a domestic market big enough to incubate national champions, a tax base big enough to fund a nuclear deterrent and a carrier group, and a shock absorber deep enough that a bad quarter is an inconvenience rather than an emergency.
France also sits inside the G7. Spain does not. In the rooms where the rules get written, one of these countries has a chair.
Wealth per person: France
Adjusting for the size of the roster, the gap narrows but does not close. The average French resident generates about $52,900 a year. The average Spanish resident generates about $41,600. France is roughly 27% richer per head.
This is the number that actually shows up in living standards, and it is the harder gap to close. It reflects forty years of accumulated capital stock, infrastructure, and productivity. Spain has been narrowing it, but arithmetic is brutal here: at current growth differentials, closing a 27% gap takes more than a decade of Spain outrunning France every single year, with no recessions and no reversals.
Jobs: France, with an asterisk
French unemployment is heading toward 8.3% in 2026 and 8.7% in 2027 on European Commission forecasts. Spain’s sits around 10.8%. On the raw number, France wins.
The asterisk is the direction of travel. Spain is coming down from a structural problem that once had one in four working-age Spaniards out of a job, and it is doing it while absorbing one of the largest migration inflows in Europe. France’s rate is going up. The IMF now expects Spanish unemployment to stay below 10% across 2026 and 2027, which would be its best sustained run in a generation.
Spain still has the worse number. France still has the worse trend. We give France the point because the point is for the score, not the story.
Corporate squad depth: France
This one is not close. France places 24 companies in the Fortune Global 500. Spain places 9.
More to the point, look at what the two benches actually contain. France fields LVMH, Hermès, L’Oréal, TotalEnergies, Sanofi, Airbus, Schneider Electric, Danone. That is global luxury pricing power, big pharma, aerospace, and industrial electrification. Spain fields Santander, BBVA, Iberdrola, Repsol, ACS, Telefónica, and Inditex. That is banking, utilities, construction, and one genuinely world-class retailer.
The French squad has more players who can win a match on their own. The Spanish squad is more dependent on macro conditions staying favorable, because banks and utilities are leveraged bets on rates and energy respectively.
Second Half: Spain Takes Over
Growth: Spain, and it is not remotely close
The IMF expects Spain to grow 2.1% in 2026 and 1.8% in 2027. It expects France to grow 0.6% in 2026 and 0.9% in 2027. The euro area as a whole is running around 0.9%.
Spain is the fastest-growing major economy in the eurozone and is growing at roughly three and a half times France’s pace. It came off a 2.8% year in 2025. It is running closer to the United States than to its own neighbors. Domestic demand is doing the work, supported by employment growth, sustained inward migration, and household balance sheets that carry less leverage than they have in decades.
France, meanwhile, is not just slow. It briefly contracted. Growth of 0.6% in an economy carrying 116% public debt is the macroeconomic equivalent of trying to walk uphill while your bag gets heavier.
The balance sheet: Spain
Here is the category that will decide the next decade, and it is a slaughter.
French public debt was around 116% of GDP in 2025 and the European Commission expects it to reach roughly 120% by 2027. The 2026 deficit is forecast at 5.1% of GDP, the largest in the European Union and nearly double the EU’s 3% target. Debt servicing has become one of the largest line items in the entire French budget.
Spanish public debt was around 101% of GDP at the end of 2025 and is forecast to drop below 100% and keep falling. Its 2026 deficit is projected at 2.4% of GDP, already inside the EU ceiling.
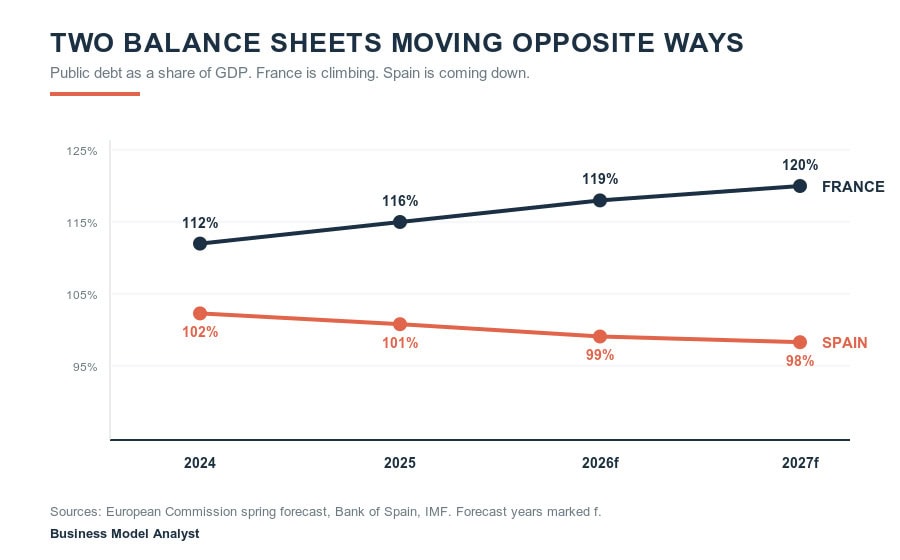
Twenty years ago the assumption in every European finance ministry was that Spain was the fiscal risk and France was the anchor. That assumption is now inverted, and it inverted while nobody was looking.
External balance: Spain
France runs a current account deficit of roughly 0.3% of GDP. Spain runs a surplus of roughly 2.9%, worth around 48.7 billion euros in 2025, and posted its largest monthly surplus on record in October of that year.
The engine underneath it is worth naming. Spain welcomed 96.8 million international visitors in 2025, a record, and they spent 134.7 billion euros. Tourism is now roughly 12.6% of Spanish GDP. Crucially, spending is growing faster than arrivals, which means the country is finally monetizing each visitor better rather than simply cramming more of them onto the same beaches.
Spain is also earning its way out of trouble on the export side. When S&P upgraded the country in September 2025, it explicitly cited a private-sector-driven improvement in Spain’s external financial position, supported by high savings and robust exports.
The Category Nobody Wins
Read those two sentences again. Within five weeks, the same agency moved these two economies onto the exact same rung. France, the G7 member, the seventh-largest economy in the world, the one that is 72% bigger and 27% richer per person, is now priced at the same long-term credit risk as Spain.
S&P’s reasoning on France was blunt: political fragmentation, an inability to pass meaningful consolidation, and a debt path headed to 121% of GDP by 2028. Its reasoning on Spain was the mirror image: a strengthening external position, robust exports, and a private sector doing the heavy lifting. Moody’s and Fitch both lifted Spain days later, citing strong growth and falling unemployment.
Markets noticed before the agencies did. The IBEX 35 gained close to 50% in 2025, its second-best year on record, driven by a banking sector that makes up over 40% of the index. Foreign direct investment into Spain rose 15% in 2024 while it fell 14% in France.
The Final Score
France wins on total output, wealth per person, employment, and corporate firepower. Spain wins on growth, public finances, and external balance. They tie on the one number that represents what the market thinks of both of them combined.
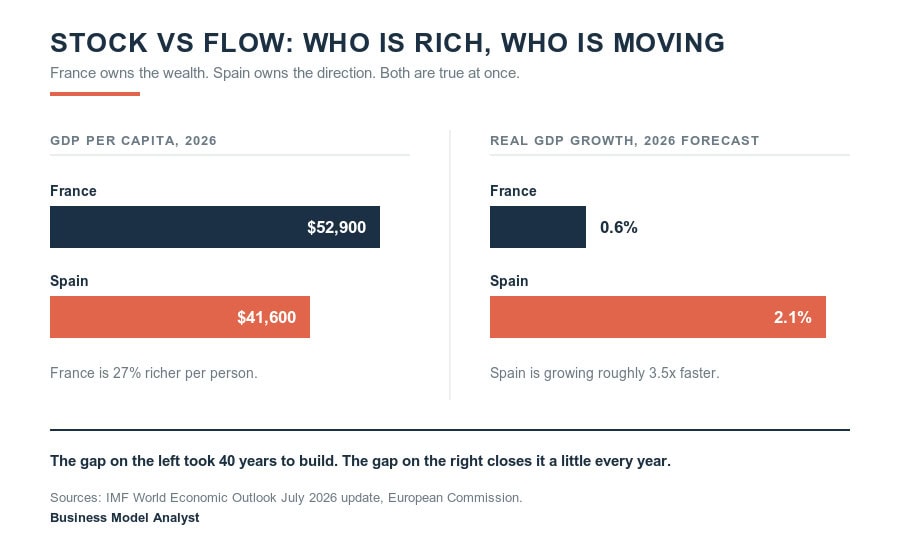
Now look at the shape of that scoreline, because it is the entire point of the exercise.
Every category France wins is a stock. It measures something France accumulated in the past and still owns: a bigger economy, a richer population, a deeper corporate bench. Stocks are durable. Nobody takes them away from you quickly.
Every category Spain wins is a flow. It measures what is happening right now and what will still be happening next year: faster growth, improving debt, money coming in from abroad. Flows are what turn into stocks.
France is a business with a magnificent balance sheet and a deteriorating cash flow statement. Spain is a business with a thinner balance sheet and a cash flow statement that is compounding. Ask any investor which one they would rather own for ten years and watch how long they hesitate.
There is one caveat that cuts against Spain, and it is a serious one. Spain’s fiscal watchdog projects that pension, health, and long-term care spending will rise by around 4% of GDP between 2030 and 2050, one of the largest increases among advanced EU economies. Spain is winning the current decade partly because it has not yet paid for the next one. Its window to fix that is exactly the window it is enjoying now.
FAQ
Which economy is bigger, France or Spain? France, comfortably. French nominal GDP is around $3.60 trillion in 2026 versus roughly $2.09 trillion for Spain, making France about 72% larger. France ranks seventh in the world by nominal GDP; Spain ranks around fourteenth.
Is France richer than Spain per person? Yes. GDP per capita is roughly $52,900 in France versus roughly $41,600 in Spain, a gap of about 27%.
Why is Spain growing so much faster than France? Spain is forecast to grow 2.1% in 2026 against 0.6% to 0.9% for France. The drivers are domestic demand, employment growth, sustained inward migration, low household leverage, a record tourism sector, and a high share of renewables in its electricity mix that has softened the impact of the energy shock. France is weighed down by a 5.1% deficit, political gridlock in a fragmented parliament, and weak private consumption.
Do France and Spain have the same credit rating? From S&P Global, yes. Both carry a long-term rating of A+ following Spain’s upgrade in September 2025 and France’s downgrade in October 2025. Moody’s still rates France above Spain, but the gap has closed dramatically.
Which country has more public debt? France, by a wide margin in both level and direction. French public debt sits around 116% of GDP and is forecast to reach roughly 120% by 2027. Spanish debt is around 101% and falling below 100%.
Which country has more large companies? France, with 24 firms in the Fortune Global 500 against Spain’s 9. France’s corporate roster is also more diversified, spanning luxury, pharmaceuticals, aerospace, and energy, while Spain’s leans heavily on banking, utilities, and construction.
The Business Model Analyst Take
If you handed a founder these two companies without the country names attached, this would not be a hard call.
Company A: $3.6 billion in revenue, market-leading brands, a legendary product portfolio, growing 0.6% a year, burning 5.1% of revenue annually with no credible plan to stop, and carrying debt worth 116% of annual revenue that is still climbing. The board is deadlocked and cannot pass a budget.
Company B: $2.1 billion in revenue, less glamorous, growing 2.1%, cash flow positive, paying down debt, and generating a surplus with customers abroad. Less prestige. Better trajectory.
You would not confuse Company A for a failing business. It has assets that took a century to build and it is not going anywhere. But you would know exactly which one is being run better right now, and you would know which one the market has already started to reprice. That repricing has a date on it: October 17, 2025, the day S&P put them on the same line.
The operator lesson here is old and keeps getting relearned. Scale is a moat, not a strategy. France has spent two decades assuming its size would compensate for its inability to balance a budget, and it is discovering that creditors eventually stop giving credit for heritage. Spain spent the same two decades getting humiliated by a debt crisis, fixing its external position, and rebuilding its cost base. The one that got punished is now the one being upgraded.
The match on Tuesday will be decided in ninety minutes and France goes in as the favorite, deservedly. The economic match has no final whistle. It just keeps running, and on current form, the team that is losing on the scoreboard is the one playing better football.
For more economies scored the same way, see our breakdowns of Portugal vs Spain, Spain vs Austria, France vs Sweden, Paraguay vs France, and Norway vs England. For the money powering the tournament itself, start with the FIFA business model and how money actually flows through soccer.