
Its 100-hour iron-air system is the cheapest storage in the world per kilowatt-hour. The grid buys kilowatts.
Form Energy closed a $750 million round on Tuesday, pushing lifetime fundraising past $2 billion, and reported that its commercial backlog jumped from 20 gigawatt-hours to 80 gigawatt-hours this year. Divide that backlog by the 100-hour duration Form sells and you get 800 megawatts of dispatchable power, roughly one mid-size gas plant. Form’s cost advantage lives in the energy dimension. Almost every buyer in American power still writes checks against the power dimension. Closing that gap, not the chemistry, is what the $750 million has to pay for.
Mateo Jaramillo calls the product an “e-peaker,” an electric version of the gas turbines utilities fire up a handful of days a year. The comparison flatters the wrong number. A simple-cycle gas turbine is cheap to buy and expensive to run. Form’s battery is the reverse: cheap to run, expensive to buy. Borrowing the peaker’s name means competing on the peaker’s metric, and on that metric Form loses by a factor of two or more.
What Happened
Form Energy, the Somerville and Weirton company commercializing a rechargeable iron-air battery, raised $750 million in a round that brings total capital raised above $2 billion. Investors include T. Rowe Price, Sequoia Capital, Janus Henderson, Franklin Templeton, TPG Rise Climate, Coatue, GE Vernova, and Dustin Moskovitz and Cari Tuna. Form will spend the money scaling its Weirton, West Virginia plant and funding its first wave of commercial projects.
The chemistry works on what Form calls reversible rusting. The cell takes in oxygen and converts iron to rust while discharging, then reverses the reaction while charging. Iron, water and air cost almost nothing, which is why Form targets system costs under $20 per kilowatt-hour against $130 to $176 per kilowatt-hour for a conventional four-to-six-hour lithium system. The tradeoff sits in efficiency: round-trip efficiency runs under 50 percent, against roughly 85 to 90 percent for lithium-ion. Form must buy about two kilowatt-hours to sell one.
The backlog quadrupled to 80 gigawatt-hours. The anchor is a 300 megawatt, 30 gigawatt-hour installation for Xcel Energy at Pine Island, Minnesota, supporting a new Google data center. Crusoe, which builds AI data centers for Oracle and Meta, has signed for 12 gigawatt-hours starting in 2028. FuturEnergy Ireland plans a system in the northwest of Ireland by 2029.
The Backstory
Jaramillo and Yet-Ming Chiang founded Form in 2017. Jaramillo built Tesla’s Powerwall business and worked on early Tesla powertrains; Chiang, an MIT professor, co-founded lithium pioneer A123 Systems. The company spent seven years on research before declaring the product ready for serial production in late 2024, alongside a $405 million Series F led by T. Rowe Price.
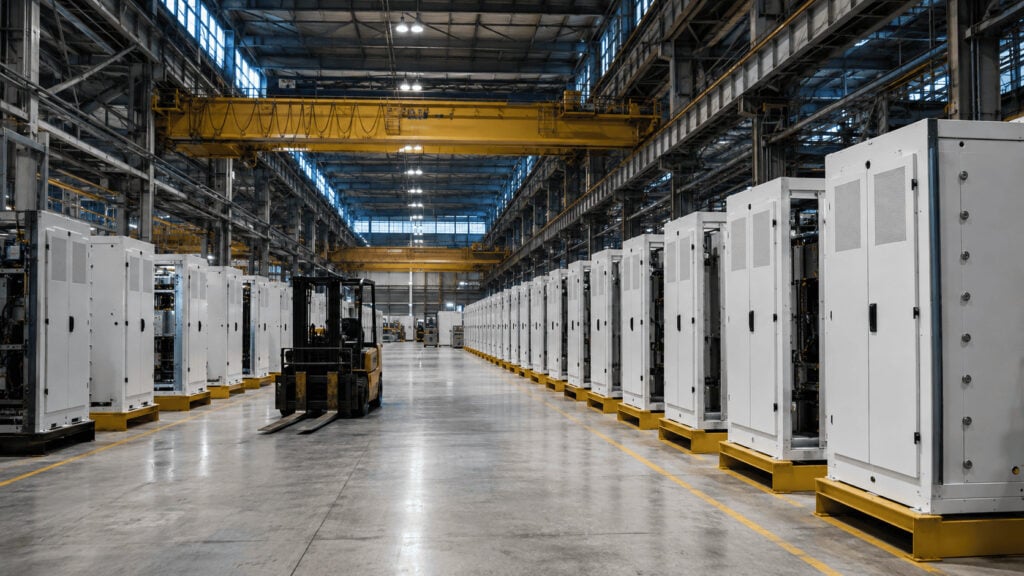
Weirton was a bet on the Rust Belt, and the pun was deliberate. Form put an 800,000 square foot factory on 55 acres of the former Weirton Steel site, backed by up to $290 million in asset-based performance financing from West Virginia and a $150 million Department of Energy grant funded by the infrastructure law. The state expects at least 750 permanent jobs. The DOE award was sized to a production line running up to 20 gigawatt-hours a year, staffed by at least 600 people.
That factory is the constraint the backlog now runs into. Form is scaling Weirton toward 500 megawatts of annual production capacity by 2028, the year Xcel deliveries begin. The Pine Island project alone consumes 300 of those 500 megawatts. An 800 megawatt backlog against a 500 megawatt-per-year line that has not yet reached nameplate means the queue stretches past 2029 even if nothing slips.
Ambri, the MIT liquid-metal battery company backed by Bill Gates, filed for Chapter 11 in May 2024 while telling the court its order book equaled three years of planned factory output. Demand was never Ambri’s problem. It raised $223 million, failed to close a $300 million Series F, sold itself to its lenders, and shut down for good in late 2025. Its equipment went to auction that November. ESS Tech, the listed iron-flow company, booked $1.6 million of revenue in all of 2025 against a $63.4 million net loss. A signed order in long-duration storage has a poor track record of converting into a shipped product, a point this site made about the wider AI-power trade in The AI Power Trade Just Split Into Sellers and Storytellers.
The Plan
Form will use the round to lift Weirton output and fund first deployments. The strategic logic runs through three buyers, and all three sit outside a competitive capacity market.
Xcel is a regulated utility recovering costs through a rate case. The Pine Island deal rides on a bespoke tariff Google and Xcel designed called the Clean Energy Accelerator Charge, which funds 1,400 megawatts of wind, 200 megawatts of solar and the 300 megawatts of Form storage, plus a $50 million Google contribution to Xcel’s grid reliability program. Google pays for its own service and grid upgrades. Regulators approve the structure; nobody bids.
Crusoe is vertically integrated and values uptime at whatever uptime costs, because a dark GPU hall has no fallback revenue. FuturEnergy Ireland operates on an island grid with thin interconnection and a real multi-day wind drought problem, and Irish grid operators have already refused new data center connections in Dublin. None of the three clears a merchant auction. Form’s addressable market is the set of buyers who purchase firmness bilaterally, from a regulator, a landlord or a national grid with no alternative.
The Business Model Angle
Grid storage carries two prices. One is dollars per kilowatt-hour, the cost of the reservoir. The other is dollars per kilowatt, the cost of the tap. Lithium-ion is expensive per kilowatt-hour and cheap per kilowatt, which is why it dominates two-to-four hour applications. Form inverts that. Its reservoir is the cheapest anyone has built. Its tap is not.
Run the arithmetic at Form’s own target. One hundred hours at under $20 per kilowatt-hour puts roughly $2,000 per kilowatt into the energy blocks alone, before power conversion, balance of plant or interconnection. The Energy Information Administration put the average simple-cycle turbine entering service in 2023 at $562 per kilowatt. A September 2025 study by GridLab and Energy Futures Group found 2025 in-service projects landing between $728 and $1,544 per kilowatt.
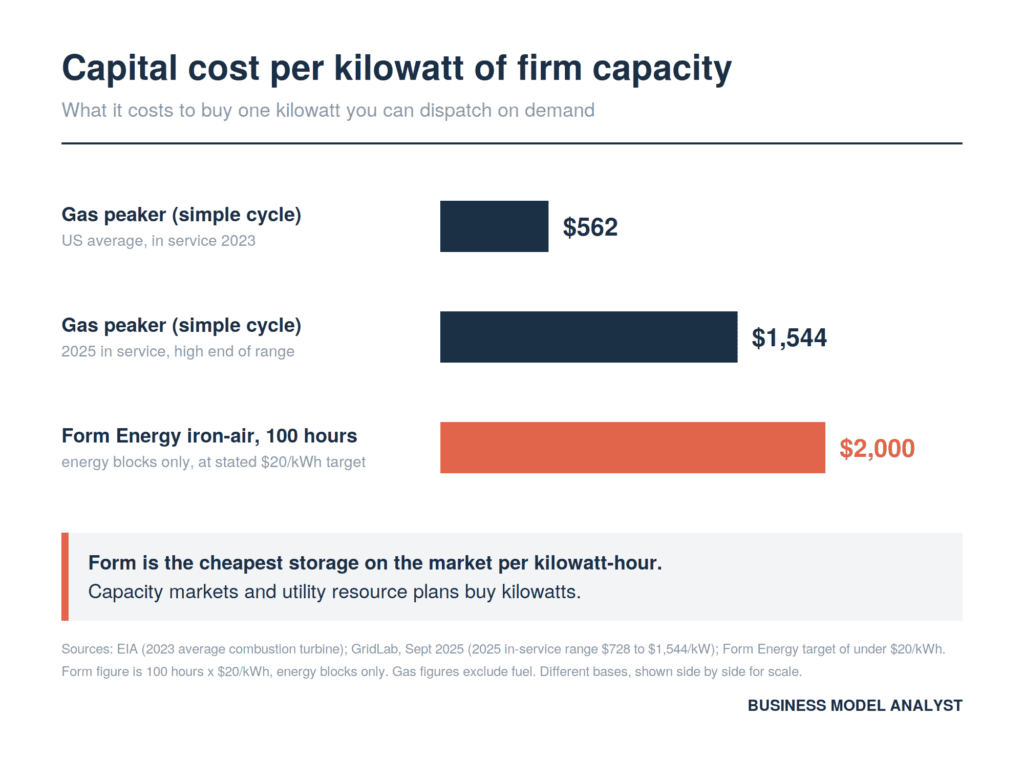
Now price the revenue. PJM’s most recent capacity auction cleared at $333.44 per megawatt-day, the third consecutive record and pinned to the FERC price cap. Annualized, that is about $122 per kilowatt-year. Against $2,000 per kilowatt of capex, a Form system needs roughly sixteen years of record-setting capacity revenue to return capital, before financing cost, operations, or the two kilowatt-hours it must buy for every one it sells. That is why no merchant developer is in Form’s customer list. The economics do not close in a market that pays for kilowatts, and every American capacity market pays for kilowatts. Whether ratepayers or hyperscalers end up funding the difference is the fight tracked in Who Pays for AI’s Power?.
Sequoia’s David Cahn framed the round as venture capital rotating toward hard problems now that AI has made software cheap to build. The rotation is real. Solving a hard engineering problem and solving a hard pricing problem are separate exercises, and Form has only finished one.
The Risk
The efficiency penalty gets worse as the AI buildout succeeds. Form’s business case assumes cheap charging power, ideally curtailed renewables that would otherwise be spilled. Vineet Khanna of T. Rowe Price made exactly this argument, pointing to nuclear plants that keep running through hours when wholesale prices collapse. Data centers are the largest new consumer of precisely those cheap off-peak hours. A sub-50-percent-efficient battery buying power in a grid where AI load has bid up the overnight price is a different business from one charging on free spilled wind.
Three more exposures sit under the round. The 45X manufacturing credit that underwrites Weirton phases down starting in 2030 and ends in 2033, which is the same window Form’s current backlog delivers into. Jaramillo’s line that Form has “zero reliance on China” is doing tax work as well as marketing: the foreign entity rules added by the 2025 budget law disqualify 45X claims where a prohibited entity provided material assistance, measured by a cost-based formula that Treasury only began clarifying in February 2026. Form reports about 80 percent US content with the remainder from Europe and Asia, and the composition of that remainder decides the credit.
Then there is the concentration. Xcel represents 30 of 80 backlog gigawatt-hours and 300 of the 500 megawatts Weirton hopes to produce annually by 2028. Xcel’s own build phases run 2028 through 2031. One regulatory delay in Minnesota moves most of Form’s near-term revenue.
Quick Questions
Is 100 hours actually useful? For a four-day winter storm or a European wind drought, yes. American grid planners have not built a payment category for it. Capacity accreditation rules and resource plans were written around four-hour lithium.
Why is GE Vernova investing in a competitor? Because GE Vernova cannot build turbines fast enough. It is running toward 20 gigawatts of annual gas turbine output with more than 100 gigawatts already contracted, effectively sold out through 2030. Funding the substitute is a hedge on its own bottleneck.
Does the round imply a rising valuation? Form disclosed the round size, not the valuation. The $750 million adds to about $1.2 billion previously raised.
How does this compare to lithium? Roughly one tenth the cost per kilowatt-hour stored, roughly half the round-trip efficiency, and about ten times the discharge duration.
The Business Model Analyst Take
The strongest argument for Form is one its own marketing keeps burying under the gigawatt-hour headline. Compare Form to a gas peaker on price and it loses. Compare it to a gas peaker you cannot buy and it wins on the only variable that matters, which is whether the megawatt exists in 2029. GE Vernova, Siemens Energy and Mitsubishi are the entire Western supply of heavy-duty turbines and all three are booked out past 2028. A hyperscaler that needs firm capacity before 2030 does not face a menu. Scarcity, not chemistry, is Form’s real moat, and scarcity is the kind of moat that closes when three industrial companies finish expanding their factories, which all three have announced they will.
That reframes the $750 million. It is not primarily a bet on iron-air beating lithium. It is a bet that Form can convert an 800 megawatt order book into shipped hardware during the four-to-five-year window when nobody else can sell a dispatchable megawatt. Ambri lost that race with a backlog it thought was a moat. Form has more capital, a finished factory and a signed hyperscaler, which is a materially better position and still the same race.
Watch one number. Not the backlog, which grows on announcements. Watch megawatt-hours shipped out of Weirton per quarter starting in 2027. That is the only figure that distinguishes Form from the graveyard it is walking through.