Ford’s target market is not who its advertising suggests. The company’s most valuable customer is a fleet manager buying twelve Transit vans, not a suburban family shopping for an Explorer. In 2025, Ford Pro, the commercial and government segment, produced $6.84 billion in EBIT. The entire company produced $6.78 billion in adjusted EBIT. Everything Ford sells to consumers, taken together, contributed nothing to the bottom line that year.
That is the single fact most Ford target market analyses miss, and it changes the answer to almost every question that follows.
What Is a Target Market Analysis?
A target market analysis identifies which customer groups a company actually serves, how it divides them, and which of them it makes money on. The last part is where most analyses stop short. Listing demographics is easy. Ranking those demographics by the profit they generate is the part that has strategic consequences.
Why Ford is a useful case: Ford reports its results in three customer-facing segments rather than by geography or product. Ford Blue sells combustion and hybrid vehicles to retail buyers. Ford Model e sells electric vehicles. Ford Pro sells to businesses, governments, and fleets. Because Ford publishes revenue, volume, and profit for each, you can calculate what each type of customer is worth instead of guessing.
Ford Target Market at a Glance (2026)
| Metric | Figure | What it tells you |
|---|---|---|
| Ford Pro 2025 EBIT | $6.84 billion | Commercial buyers out-earned the whole company |
| Ford Blue 2025 EBIT | $3.02 billion | Retail combustion and hybrid, 3.0% margin |
| Ford Model e 2025 EBIT | Loss of $4.81 billion | Retail EV, negative 72.1% margin |
| EBIT per vehicle, Ford Pro (2025) | $4,599 | Calculated from segment wholesales |
| EBIT per vehicle, Ford Blue (2025) | $1,108 | A fleet sale is worth roughly four retail sales |
| US Class 1-7 commercial share | 40.4% | Ford’s position with business buyers |
| Estimated US retail share, June 2026 | 12.3% | Ford’s position with consumers |
| Ford brand average transaction price, June 2026 | $56,826 | Industry average was $49,758 |
| Ford Pro Intelligence paid subscriptions | Over 900,000 | Up roughly 20% in the first half of 2026 |
| EVs as a share of Q2 2026 US sales | 1.8% | Down from 2.7% a year earlier |
Who Is Ford’s Target Audience?
Ford sells to three populations that have almost nothing in common except the badge on the grille.
The first is the commercial operator: plumbers, electricians, general contractors, landscapers, utilities, municipal fleets, police departments, and rental companies. They buy Transit vans, Super Duty trucks, E-Series chassis cabs, and Police Interceptors. They buy in multiples, on a replacement cycle, and they care about uptime and total cost of ownership rather than colour or badge prestige.
The second is the high-trim retail truck and SUV buyer. This customer buys an F-150 Lariat, a Bronco Badlands, an Explorer Platinum, or an Expedition Tremor. They are not buying transport. They are buying capability they may rarely use, which is why off-road performance trims (Raptor, Tremor, Timberline, FX4) accounted for 20.6% of Ford’s US mix in 2025 on sales of 453,433 units, up 17.6% year over year.
The third is the retail electric vehicle buyer, and this group has largely stopped showing up. Electric vehicles were 1.8% of Ford’s US second-quarter 2026 sales, down from 2.7% a year earlier.
The share data alone makes the point. Ford is a minor player among consumers and a dominant one among businesses.
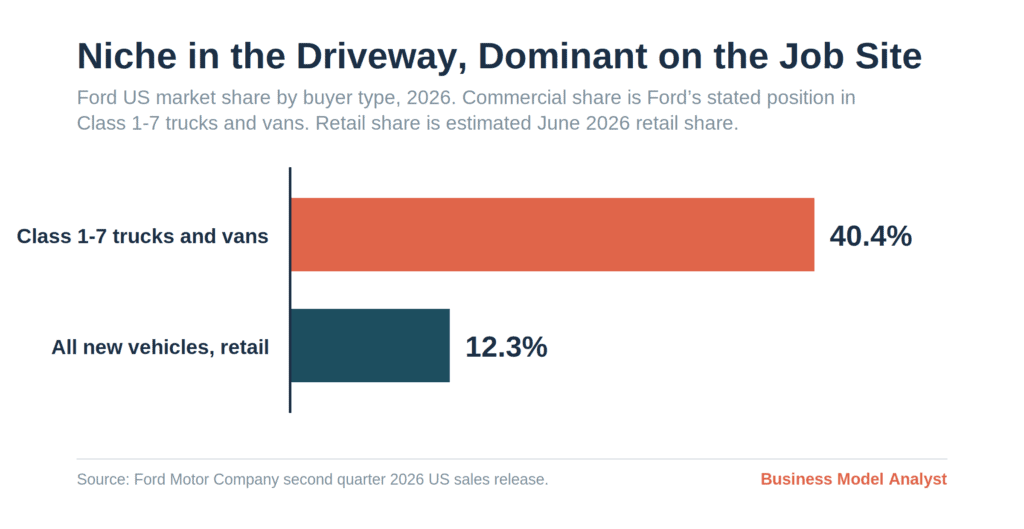
Ranking these three groups by profit rather than by volume inverts the usual picture of Ford as a mass-market consumer brand.
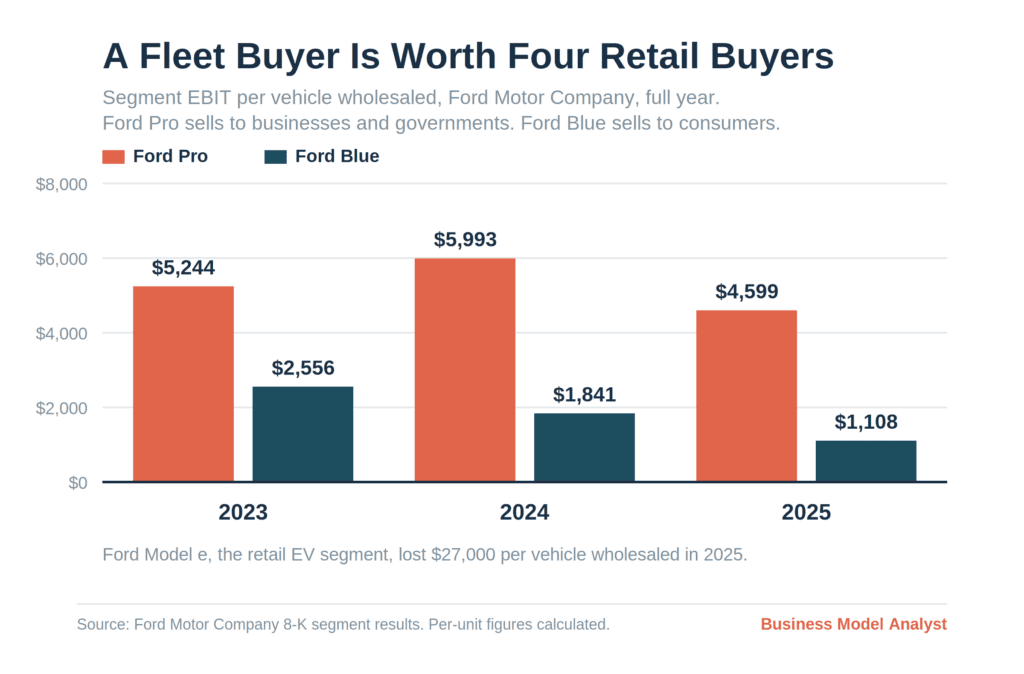
The gap is not new, but it has widened. In 2023 a Ford Pro vehicle earned roughly twice what a Ford Blue vehicle earned. By 2025 it earned more than four times as much. Meanwhile Ford Model e lost approximately $27,000 on every vehicle it wholesaled.
Ford Target Market Segmentation
Ford segments its market in four conventional ways. What is unconventional is how unevenly those segments contribute.
Demographic Segmentation
The demographic story most articles tell about Ford is that it serves middle-income households earning $50,000 to $120,000. The transaction data does not support this.
The Ford brand’s average transaction price was $56,826 in June 2026, against an industry average of $49,758. Ford has run above the market every month of 2026.
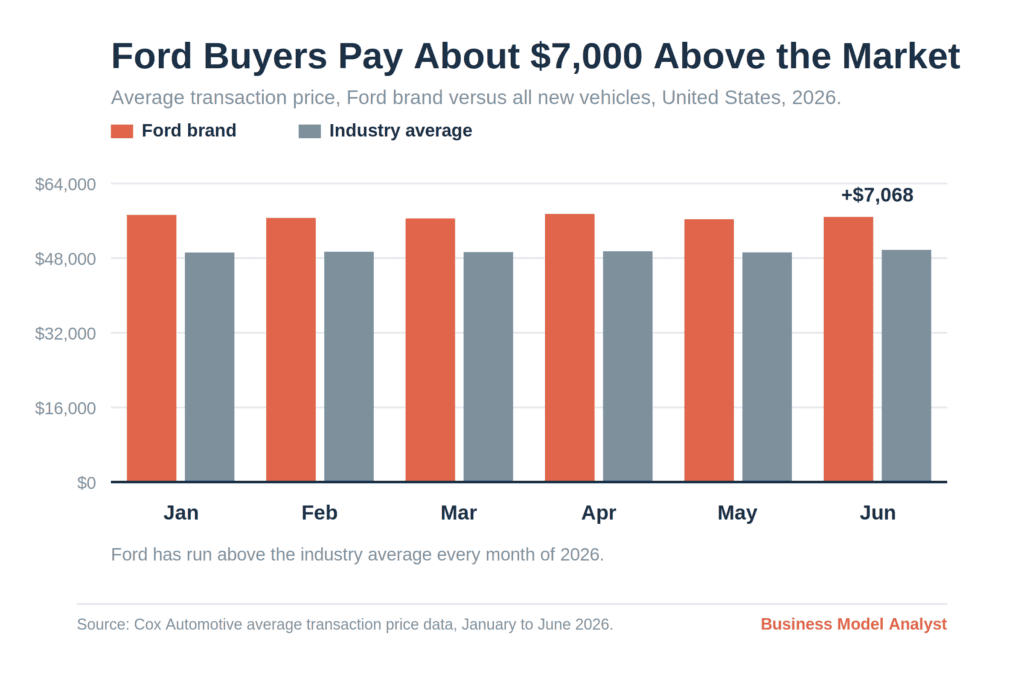
A brand whose average buyer spends roughly $7,000 more than the average new-car buyer is not competing on affordability. It is competing on capability and trim, and it has deliberately shed the cheap end. Ford discontinued the Escape and the Lincoln Corsair, and second-quarter 2026 daily rental sales fell 69%. Total Q2 sales dropped 10.3% to 549,200 vehicles as a result, and Ford’s estimated June retail share still rose 0.2 points.
That is the demographic strategy in one line: fewer buyers, richer buyers.
The one genuine entry point is the Maverick, which starts near $27,000 and sold a record 155,051 units in 2025, up 18.2%. Maverick Hybrid set a quarterly record in Q2 2026 with 29,457 units. It exists to bring buyers into the brand who would otherwise never enter a Ford showroom, and to hold a price rung Ford’s own roadmap says it intends to defend with a roughly $30,000 electric pickup arriving in 2027.
Geographic Segmentation
Ford’s US strength is concentrated in truck and SUV geographies, which is to say most of the country outside dense coastal metros. Its weakness shows up where electrification policy is strongest. Ford sold 4,685 EVs in California in the first half of 2026, down 48.5% year over year, and its share of the state’s EV market fell from 5.0% to 3.4%.
Internationally, the geographic segmentation is really a product segmentation. Europe is a commercial vehicle market for Ford, led by Transit and the Ranger, where Ford Pro has held the leading commercial brand position for years. The Ranger, meanwhile, grew 53.6% in the US in 2025 to 70,960 units, borrowing a global platform to fill a domestic midsize gap.
Behavioral Segmentation
This is where Ford’s business model has changed most and where the old target market framing is most out of date.
Ford is no longer trying to sell a vehicle and wait four years for the next one. It is trying to convert the purchase into a subscription. Ford Pro Intelligence paid software subscriptions passed 900,000 in the first half of 2026, up roughly 20%, and total paid subscriptions across the company reached about 1.6 million, up roughly 50%.
The behavior Ford is segmenting on is no longer “how often do you buy” but “how deeply are you embedded.” A contractor running telematics, scheduled maintenance, and financing through Ford Pro faces real switching costs. A retail buyer choosing between an Explorer and a Highlander faces none.
Psychographic Segmentation
Ford’s retail psychographics are stable and well understood: capability, durability, and a self-image built on work even among buyers who do not work in trades. The off-road trim mix is the cleanest evidence. One in five Ford vehicles sold in the US carries a trim designed for terrain most of them will never see.
The psychographic segment Ford spent the most money chasing is the one that shrank. The environmentally motivated early adopter was the centre of Ford’s product plan for half a decade. Then the $7,500 federal tax credit expired on 30 September 2025.
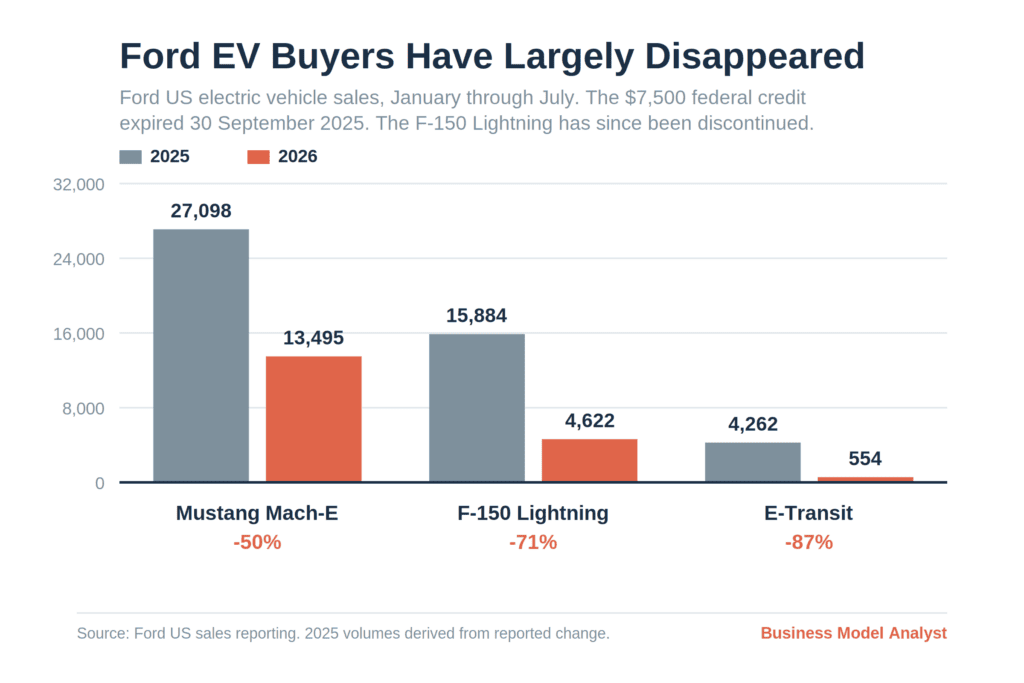
Ford’s US EV sales fell 57.4% in the first half of 2026 to 16,606 units, fewer than the Mustang Mach-E alone sold in the same period a year earlier. The F-150 Lightning has been discontinued. Model e is guided to lose $4.0 billion to $4.5 billion in 2026 and is not expected to reach profitability until 2029.
The lesson is not that the eco-conscious buyer was imaginary. It is that a large part of that segment was defined by a subsidy rather than by a preference, and subsidised segments are rented, not owned.
How Ford Reaches Each Segment
Ford runs three distinct go-to-market motions, not one campaign with different creative.
Commercial: a dedicated sales organisation with state and local government pricing programs, a GSA contract for federal agencies, municipal lease plans through Ford Pro Credit, upfitting, and a service network built around uptime. Ford Pro extended employee pricing to business customers in 2026, a move aimed at retention rather than acquisition. Alicia Boler Davis runs the segment, and Ford has said 2027 customer contracting was running a month ahead of the prior year’s pace.
Retail trucks and SUVs: experiential marketing (Bronco Off-Roadeo), off-road trim laddering, motorsport association, and dealer-level engagement through FordPass. The mechanism here is trim escalation, moving a buyer from XLT to Lariat to Platinum rather than from one nameplate to another.
Entry and conquest: the Maverick, priced to be found by people shopping crossovers, and the badge extensions. Ford has already run the badge-extension experiment once, with the Mach-E outselling the gas Mustang in both 2024 and 2025, and is reportedly preparing to run it again with a four-door Mustang aimed at a price tier Ford has publicly conceded it cannot reach with a conventional sedan.
Ford vs Competitors: Target Audience Comparison
| Ford | General Motors | Tesla | Toyota | |
|---|---|---|---|---|
| Primary profit customer | Commercial fleets | Full-size truck retail | Retail EV, premium tier | Mass-market retail |
| US commercial position | 40.4% Class 1-7 share | Contesting Ford’s claim | Minimal | Limited |
| Entry price rung | Maverick, near $27,000 | Trax and Trailblazer | Model 3 | Corolla and Corolla Cross |
| Powertrain hedge | Hybrid, record 228,072 US units in 2025 | EV-forward, hybrid catching up | EV only | Hybrid-led for two decades |
| Switching costs | Software and service embedding | Weaker | Charging network and software | Resale value and reliability |
Ford and General Motors genuinely disagree about who leads commercial sales, because they count differently. GM counts businesses operating five or more vehicles. Ford counts every Class 1-7 truck or van registered to a business, which includes the two-van plumbing outfit. Ford’s definition is the one that matches how it monetises: a two-van business still pays for telematics.
The comparison with Tesla is less useful than it was in 2021. Tesla and Ford are barely competing for the same buyer any more. Ford’s electric volume is roughly a rounding error against its truck business, and its EV strategy has shifted from competing on product to competing on cost structure with the Universal EV platform.
Where Ford’s Positioning Is Strong
- A profit pool competitors find hard to attack. Commercial relationships are slow to build and slow to lose. Fleet buyers do not switch on a rebate, and Ford has been embedding software into those relationships for five years.
- Powertrain optionality. Ford’s 228,072 US hybrid sales in 2025 let it absorb the EV collapse without a demand hole. Hybrids sit exactly where the market went when the subsidy left.
- Pricing power in trims, not nameplates. The off-road trim ladder lets Ford raise average transaction prices without launching new vehicles, which is capital-efficient.
- A badge with unused capacity. The Mustang name currently monetises one body style. Ford has evidence, from the Mach-E, that it travels.
Where the Positioning Is Exposed
- The consumer half of the company barely earns. Ford Blue and Model e combined lost money in 2025. A commercial business subsidising a consumer business is a workable arrangement only while the commercial business keeps growing, and Ford Pro’s EBIT fell from $9.0 billion in 2024 to $6.8 billion in 2025.
- Concentration risk in one customer type. Commercial demand is cyclical and tied to construction, utilities, and municipal budgets. A downturn hits Ford’s profit pool harder than its volume.
- Price ladder depends on trust. Charging $7,000 above the market average requires customers to believe the product justifies it. Recall performance is the obvious pressure point, and it is covered in more detail in the Ford SWOT analysis.
- The affordable rung is thin. With the Escape gone, Maverick is doing a great deal of work as the only genuine entry point until the Universal EV platform truck arrives in 2027.
Frequently Asked Questions
Who is Ford’s target market in 2026? Ford serves three groups: commercial and government fleet operators, retail buyers of high-trim trucks and SUVs, and a much-diminished retail EV audience. Commercial buyers generate the majority of the company’s profit despite being a minority of its volume.
What is Ford’s most profitable customer segment? Ford Pro. In 2025 it produced $6.84 billion in EBIT on $66.3 billion in revenue, a 10.3% margin, versus 3.0% for Ford Blue and a negative 72.1% margin for Ford Model e.
Is Ford an affordable brand? Not by transaction price. The Ford brand averaged $56,826 in June 2026 against an industry average of $49,758. The Maverick, starting near $27,000, is the exception rather than the rule.
Who buys the Ford Maverick? Ford designed the Maverick as a conquest vehicle for buyers new to trucks and new to Ford, positioned against compact crossovers rather than full-size pickups. It set a record 155,051 US sales in 2025.
Why did Ford’s EV sales fall so sharply? The $7,500 federal tax credit expired on 30 September 2025. Ford’s US EV sales fell 57.4% in the first half of 2026, and the F-150 Lightning has been discontinued.
How does Ford make money from fleet customers beyond the vehicle? Through Ford Pro Intelligence software subscriptions, telematics, service contracts, upfitting, and financing through Ford Pro Credit. Paid Pro subscriptions passed 900,000 in the first half of 2026.
The Business Model Analyst Take
Most target market analyses treat a customer segment as a description. Ford’s numbers make the case for treating it as an asset with a return.
Weighted by volume, Ford looks like a consumer truck company with a commercial side business. Weighted by profit, it is a commercial vehicle and fleet software company that also runs a large, roughly break-even consumer operation and an electric vehicle division that has cost it billions. Both descriptions use the same data. Only one of them explains why Ford spent 2025 and 2026 discontinuing consumer nameplates, cutting daily rental volume by 69%, and raising prices into a soft market while its commercial subscription count kept climbing.
The strategic question is whether Ford can keep running this arrangement. Ford Pro’s EBIT fell by $2.2 billion in 2025 and the segment is guided to $6.5 billion to $7.5 billion in 2026, roughly flat. The consumer side is being repaired but is not yet carrying itself. The transfer between the two works while the commercial business grows and stalls if it does not.
For anyone studying segmentation, the useful takeaway is narrower and more portable. Ford spent years and roughly $20 billion targeting a segment defined by a government incentive, and lost most of it within nine months of the incentive expiring. The segment it barely markets to, and which nobody writes profiles about, paid for the whole experiment.
Segments held together by a subsidy are borrowed. Segments held together by switching costs are owned. That distinction is worth more than any demographic table.