
The profit upgrade came from big trucks selling near $50,000. The spending is going into a $30,000 pickup and a battery business with no drivers as customers. Ford is funding its next buyer with its current one.
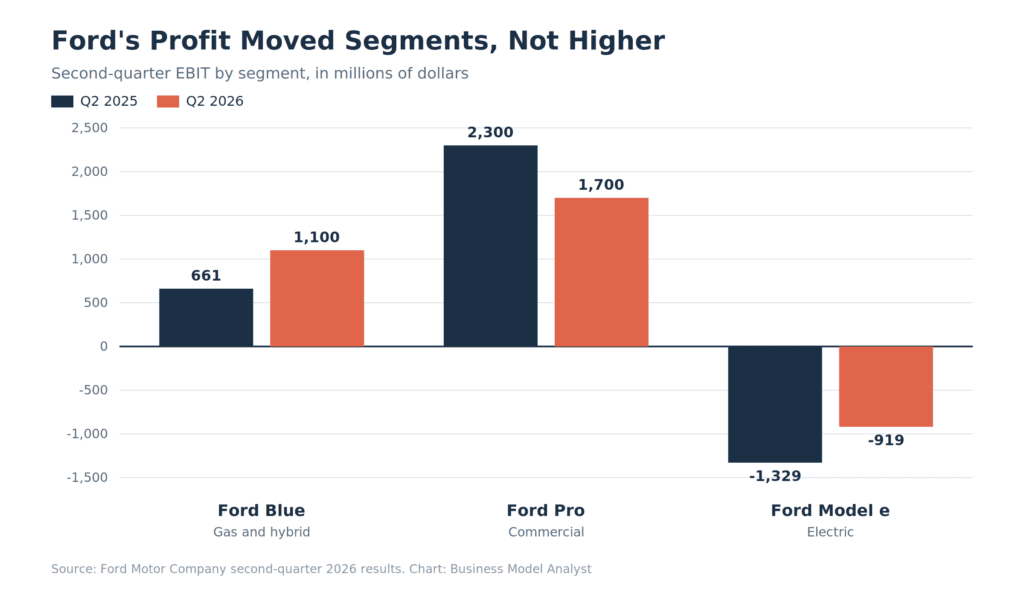
Ford raised full-year adjusted EBIT guidance to $10 billion to $11 billion on July 28, up from $8.5 billion to $10.5 billion, even though second-quarter revenue fell 4% to $48.3 billion and U.S. sales dropped 10.3%. The upgrade came from mix and pricing, not volume. Ford Blue, the gas and hybrid business, earned $1.1 billion in EBIT against $661 million a year earlier. Model e, the electric segment, booked $1.0 billion of revenue and a $919 million EBIT loss, and Ford is routing about $1 billion of incremental 2026 investment through that segment into the Universal EV platform and Ford Energy. The customers paying for the upgrade and the customers Ford is building for are two different groups.
Sherry House told reporters on Tuesday that Ford buyers have stayed resilient through inflation and interest rates. She has the receipts. Larger off-road SUV and truck variants made up close to a quarter of Ford’s U.S. sales in the quarter, and those trim levels carry the fattest margins in the lineup. Jim Farley framed the discipline in one line on the analyst call: every dollar, he said, must earn “durable returns.”
Read the rest of the same quarter and the picture gets harder. More than a million people who normally buy new vehicles have left that market. Average transaction prices sit around $50,000. Kelley Blue Book counted subcompact SUV sales up more than 23% last month while full-size pickups moved 2.5%. Ford’s own product plan agrees with the cheap end: a $30,000 electric pickup in 2027. Ford is guiding on the rich half of the market and building for the poor half, and only one of those two shows up in the numbers investors bought on Tuesday.
What Happened
Ford beat and raised. Adjusted earnings came in at 42 cents a share against a consensus near 35 cents. Adjusted EBIT rose 17% to $2.5 billion on a margin of 5.2%, up 90 basis points. Adjusted free cash flow guidance moved to $6 billion to $7 billion from $5 billion to $6 billion. Capital spending guidance did not move, holding at $9.5 billion to $10.5 billion. Shares climbed about 7% after hours.
Underneath the beat, Ford posted a $1.3 billion net loss on $4.2 billion of special charges. The largest piece was a $3.6 billion largely non-cash write-down tied to unwinding the BlueOval SK battery joint venture with SK On. Another $500 million came from the EV program cancellations Ford announced in December 2025.
The three segments moved in different directions. Ford Pro, the commercial arm and the company’s profit anchor, earned $1.7 billion on $17.8 billion of revenue, down $600 million year over year as the Novelis aluminum fire held back F-Series output. Ford now expects roughly $1.5 billion of full-year cost from that disruption, with about $800 million already absorbed in the first half. Ford Blue picked up the slack. Model e narrowed its loss for a third straight quarter.
Volume fell on purpose in places. Ford sold 549,200 vehicles in the U.S. in the quarter, and daily rental sales dropped 69%. Trimming the retail base like this is a lever Ford’s SWOT profile has long flagged as double-edged. Discontinuing the Escape removed another block of units. Farley said F-Series inventory sits near a 45-day supply, with total U.S. retail inventory at 52 days against a 55-to-65-day target.
The Backstory
Ford spent the first half of this decade building battery capacity for a demand curve that never arrived. The EV transition sat at the center of Ford’s marketing strategy for years. The BlueOval SK venture with SK On was the centerpiece. By December 2025 Ford had cancelled EV programs and announced it would convert battery plants toward storage for data centers. Days earlier it had started unwinding the SK partnership.
In May 2026 Ford formalized the pivot as Ford Energy, a wholly owned subsidiary run by Lisa Drake out of a repurposed 4-million-square-foot plant in Glendale, Kentucky. Ford committed roughly $2 billion to convert the site for cell manufacturing through containerized system assembly, targeting at least 20 GWh of annual output with first customer deliveries in late 2027. The flagship product is the Ford Energy DC Block, a 20-foot container built on 512 Ah lithium iron phosphate prismatic cells. EDF Power Solutions signed a five-year framework in May to buy up to 20 GWh, with deliveries starting in 2028.
Ford opened a second non-consumer line the week before earnings. The U.S. Army awarded prototype contracts to Ford, GM Defense and BC Customs for the Infantry Squad Vehicle-Heavy, a 606-vehicle program spec’d around exportable power for drones and command systems. Ford is bidding a militarized F-Series Super Duty. We covered why that bid sits awkwardly against Ford’s own product decisions.
Both new lines sell power rather than transportation. Neither sells to a retail car buyer.
The Plan
Ford’s earnings deck lays out three pillars: strengthen the core automotive business, grow software and physical services, and build adjacent businesses that use manufacturing capacity Ford already owns. Standing up Ford Energy as a wholly owned subsidiary rather than a division is itself a change to Ford’s organizational structure. Paid subscriptions across the company reached about 1.6 million, with Ford Pro software subscriptions above 900,000 in the first half and up roughly 20%. BlueCruise has logged more than 12 million hands-free driving hours.
Segment guidance shows where management expects the money. Ford Blue moves up to $5 billion to $5.5 billion. Ford Pro narrows to $7 billion to $7.5 billion. Model e improves to a loss of about $4 billion, and that improved figure still absorbs roughly $1 billion of incremental spending on the Universal EV platform and Ford Energy.
The full-year outlook assumes U.S. light-vehicle sales of 16 million to 16.5 million units, commodity headwinds a little above $2 billion, and industry pricing about 50 basis points positive for the year. Every one of those assumptions rests on the same consumer holding.
The Business Model Angle
Ford is running two businesses with opposite customer economics inside one P&L, and the profitable one is paying for the unprofitable one.
The first business harvests. Ford sells fewer vehicles at higher prices to buyers who have absorbed a decade of price increases. It kills low-margin volume on purpose: the Escape, 69% of daily rental sales, first-generation EV builds. Margin expands because the denominator shrinks faster than the numerator. That is a well-run harvest, and every dollar of the guidance raise came from it. House told analysts the enterprise-level increase reduces to mix and pricing.
The second business builds. The Universal EV platform aims at a $30,000 pickup for buyers who left the market. Ford Energy aims at utilities and data centers, customers who sign multi-year framework agreements rather than walking into a dealership. Neither reaches revenue at scale before 2027, and both sit inside a segment that lost 92 cents for every dollar of revenue it recognized last quarter.
The transfer between them is the actual business model event. Ford has converted a stranded balance-sheet asset into an income-statement story by writing down $3.6 billion of battery joint-venture value in the same quarter it raised profit guidance. The write-down cleared the failed configuration. The mix gains fund the replacement. What Ford has not yet proven is that the replacement earns anything.
Battery cell capacity turns out to be more fungible than vehicle assembly capacity. A stamping line built for the Escape makes Escapes. A cell line in Kentucky can serve cars, the grid or a data center, and Ford discovered that only after the car demand failed to materialize. That optionality is real, and it is worth less than the $3.6 billion Ford wrote off to get to it.
Compare the two adjacencies on time horizon. Ford Energy has a plant, a product, a president, a customer framework and a 2027 delivery date. The Army program has three prototypes due by March 2027 against 606 potential vehicles, which rounds to nothing on $185 billion of revenue. Farley grouped them together as adjacencies close to the core. Only one of them has enough scale to matter to the model.
The Risk
The guidance raise prices a consumer who is already leaving. Ford’s outlook needs industry pricing up 50 basis points and 16 million to 16.5 million units of U.S. demand while more than a million habitual new-car buyers sit the cycle out. Kelley Blue Book’s split last month, subcompact SUVs up 23% against full-size pickups up 2.5%, describes buyers trading down inside the same showroom. Ford’s margin engine is concentrated in exactly the segment growing slowest.
Ford Pro is the deeper exposure. Commercial vehicles and attached software carry the highest quality earnings in the company, and that segment lost $600 million of EBIT year over year to a single supplier fire. Jefferies analyst Philippe Houchois reads the second quarter as the volume trough and expects Ford to recover the lost units. If the Novelis restart slips, the segment guided at $7 billion to $7.5 billion carries the miss alone.
Ford Energy enters a market with a scaled incumbent. Tesla’s Megapack output runs more than twice Ford’s 20 GWh target, and storage is one of the few arenas where Tesla’s rivals have barely dented its lead, and Ford’s first deliveries land in late 2027 against U.S. utility-scale storage additions of roughly 24 GW during 2026. Arriving late to a fast-growing market is survivable. Arriving late with a cost structure inherited from an automotive joint venture is a different question, and Ford has published no margin target for the segment.
The affordability bet also has a competitive problem Ford has not addressed. A $30,000 electric pickup in 2027 competes against used vehicles, against Chinese-built models in every market outside the U.S., and against Ford’s own Maverick. Ford’s tie-up with Geely to lift production at a Spanish plant helps volume in Europe. It also deepens a dependency on the manufacturer most likely to price against Ford at the low end.
Higher gas prices from the continuing Iran war would help truck economics not at all. House said the conflict had not dented U.S. sales so far. So far is doing real work in that sentence.
Quick Questions
Did Ford actually make money in the second quarter? On an adjusted basis, yes: $2.5 billion of EBIT and 42 cents a share. On a GAAP basis Ford lost $1.3 billion after $4.2 billion of special charges, most of it a non-cash write-down of the BlueOval SK battery venture.
Why did the stock rise on falling revenue? Investors bought the margin, not the volume. EBIT margin expanded 90 basis points while revenue fell 4%, and Ford raised both profit and free cash flow guidance.
Is the EV business getting better? Less bad. Model e improved EBIT for a third straight quarter and is guided to roughly a $4 billion full-year loss. It generated $1.0 billion of revenue last quarter against a $919 million loss.
What is Ford Energy? A wholly owned subsidiary launched in May 2026 that builds containerized battery storage systems for utilities, data centers and industrial customers from a repurposed Kentucky battery plant, targeting 20 GWh a year from late 2027.
What breaks the guidance? A slip in the Novelis aluminum recovery, or U.S. industry pricing turning negative. Ford’s raise assumes both mix and price hold through the second half.
The Business Model Analyst Take
Ford had a good quarter and told a story about resilience. The arithmetic tells a story about timing.
Everything that produced the guidance raise is finite. You can only discontinue the Escape once. You can only cut daily rentals 69% once. You can only shift mix toward high-trim off-road variants until the buyers who fund those trims stop showing up, and Kelley Blue Book’s month suggests the shift toward cheaper vehicles has already started. Harvesting a mature product line is a legitimate way to run a business, and it produces exactly the pattern Ford printed: revenue down, margin up, guidance raised. The pattern works until the base erodes past the point where mix can offset it.
Everything that would replace it is unproven. The Universal EV platform, a $30,000 pickup, 20 GWh of storage capacity and an Army prototype all arrive in 2027 or later. Ford has committed about $1 billion of incremental 2026 spending to the first two, inside a segment losing $4 billion a year. Ford is spending its harvest on a build, which is the correct thing to do and also the thing that gives it roughly eighteen months of runway before the market asks for evidence.
Watch Ford Energy over the tactical trucks. The Army program generates headlines and rounds to zero. Ford Energy has $2 billion committed, a named customer framework with EDF, and a business model that turns a manufacturing asset Ford already wrote down into recurring industrial revenue. If Drake’s unit posts a margin in 2028, Ford will have converted its worst capital allocation decision of the decade into a second business. If it does not, Ford will be a truck company that spent $3.6 billion learning that battery plants are hard to repurpose.
The tell to watch in the third quarter is not the EBIT number. It is whether Ford’s mix gains survive a full quarter of the affordability shift its own product roadmap is built around.